How to Meet Reserve Requirements on a Luxury Short-Term Rental DSCR Loan
Most files land on a six-month floor, doubling to twelve months for first-time investors.

 Lendmire Research
Most files land on a six-month floor, doubling to twelve months for first-time investors.
It’s a structuring tool, not a fix for a property that doesn’t cash flow — and it comes with a real bill later, when the payment steps up.
How To Fund The Next Rental Using A Short-term DSCR Cash-out: what investors need to know about large-balance DSCR financing, from Lendmire.
The mechanics turn on three things: documented income history, appraised value, and how much cash-out leverage your lender allows on a short-term rental.
Miss any one of those and the file either restructures or stalls.
Interest-only improves coverage on a short-term rental DSCR loan by removing the principal portion of the monthly payment from the qualifying math.
Seasoning — the length of time funds have sat in a personal account before a lender will count them as the borrower’s own money without further explanation.
No — not legitimately, and not for long.
Does A Ski Cabin That Earns One Season Cover Its DSCR Loan Payment — No, not on the strength of one good winter alone.
How DSCR Cash-out Leverage Is Laddered Across An LLC Rental Portfolio — Leverage steps down as your loan balance climbs.
How To Check Resort Rental Rules Before A DSCR Loan Closes: what investors need to know about large-balance DSCR financing, from Lendmire.
That change brings a different loan product, different leverage, and different documentation.
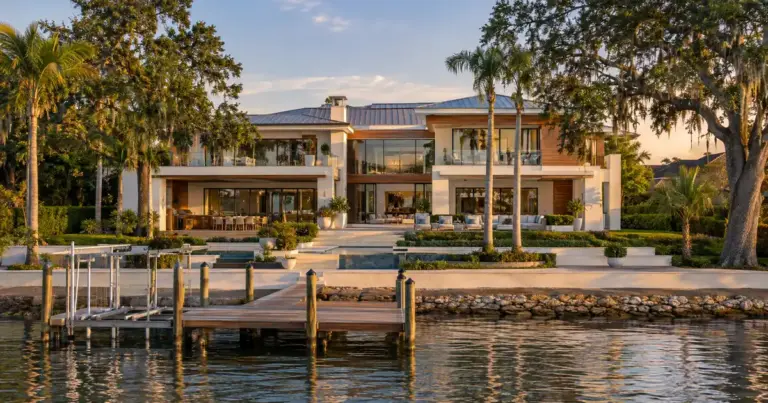
At a Glance: Reserves on a seasonal luxury short-term rental DSCR loan are typically counted as months of PITIA held in liquid, seasoned accounts
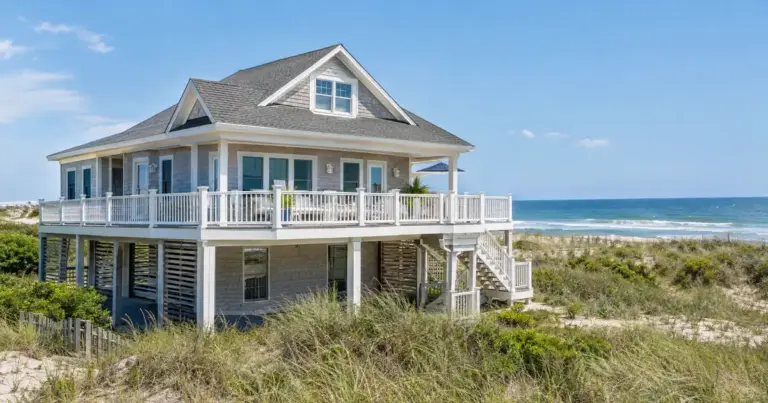
The lender wants trailing booking history, not a nightly rate multiplied by 30.
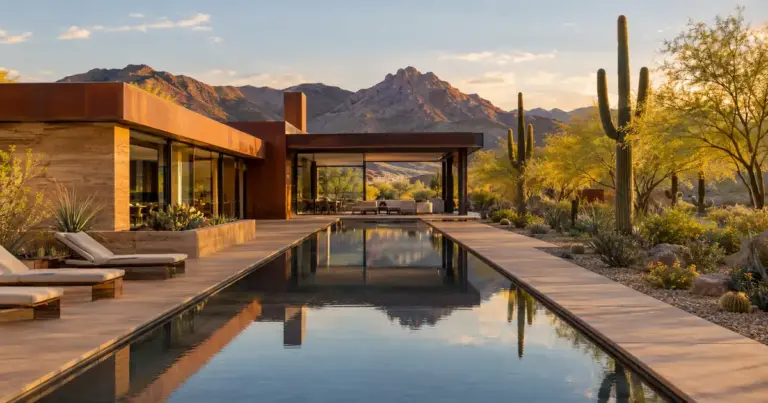
Does Renting Your Vacation Home Void A Second-home Mortgage — Not automatically.