How Much Lenders Hold Back On A Super Jumbo Bank Statement Second Home?
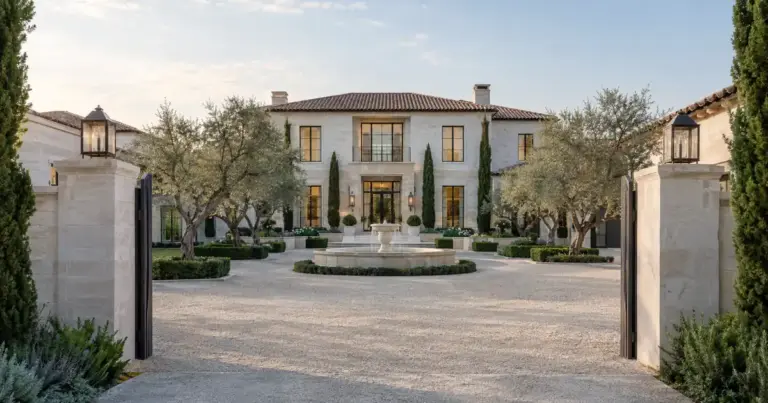
Above roughly $3,000,000, a super-jumbo overlay adds a 700 credit floor and blocks cash-out proceeds from covering the reserve requirement.

 Lendmire Research
Above roughly $3,000,000, a super-jumbo overlay adds a 700 credit floor and blocks cash-out proceeds from covering the reserve requirement.
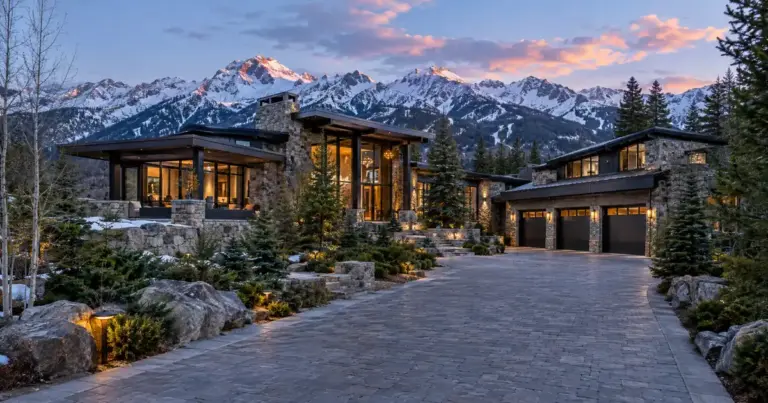
Investors shopping a $1M luxury short-term rental usually walk in assuming the math works the same way it did on their last $400,000 duplex. It doesn’t.
DSCR loans sit outside that framework entirely — the file is underwritten on unit-level rental income and project collateral risk, not GSE checklists.
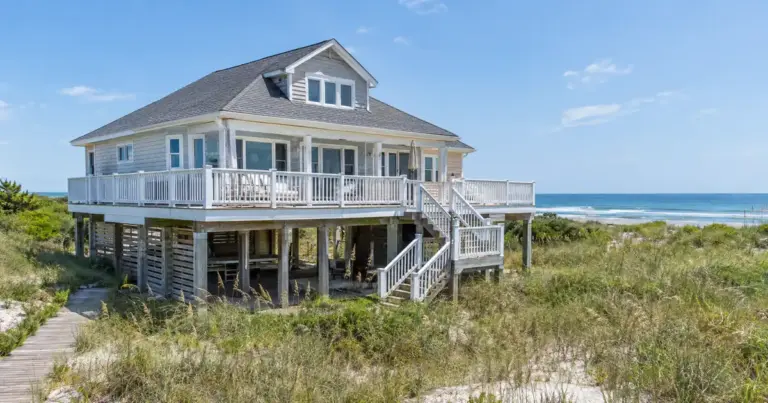
Reserves generally run six months of PITIA on the subject property, doubling to twelve months for a borrower with no prior landlord history.
Short-term Rental DSCR Loan Requirements When Permit Limits Apply — Permit legality gets checked before rental income ever enters the math.
The mechanics below explain why, and what the workaround options actually look like.
It sits right at the top edge of standard DSCR programs and the entry point of what practitioners call “super jumbo” territory.
Cash-Out Rules On A $6M Super Jumbo DSCR — At this loan size, cash-out isn’t tight — it’s gone.
At this loan size, leverage steps down, credit expectations climb, and the underwriting math still runs on one number — does the rent cover the payment.
Credit, seasoning, and reserve rules also step up once a loan crosses into super-jumbo territory.
Cash-out Refinance On A $1M Short-term Rental DSCR Loan: what investors need to know about large-balance DSCR financing, from Lendmire.
DSCR loans are designed for non-owner-occupied investment properties.
Loan amounts on this property type typically top out around $1,500,000, with leverage capped tighter than a standard rental.
Two independent appraisals replace one. Reserve math gets stricter for first-time investors.
Credit, reserves, entity paperwork, and — above a certain size — a second appraisal round out the file.