STR DSCR Vs Conventional Loan For A Luxury Rental Operator
An STR DSCR loan qualifies the property, using documented platform income or an appraisal’s short-term rent analysis, and closes directly into an LLC.

 Lendmire Research
An STR DSCR loan qualifies the property, using documented platform income or an appraisal’s short-term rent analysis, and closes directly into an LLC.
Most DSCR programs accept either vesting, so the real decision comes down to liability tolerance, portfolio size, and how many properties you plan to hold.
For a luxury short-term rental (STR) operator, the real dividing line sits around loan amount and how income gets documented, not a legal definition.
DSCR looks at the property’s rental income, not your personal cash flow — so the lump sum sitting in your account never becomes an underwriting problem.
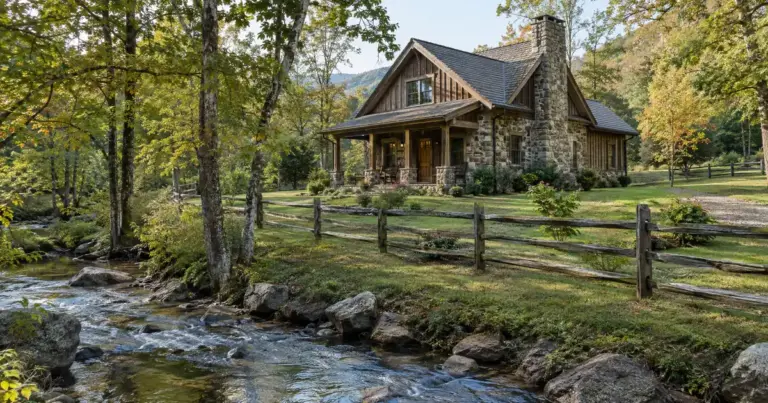
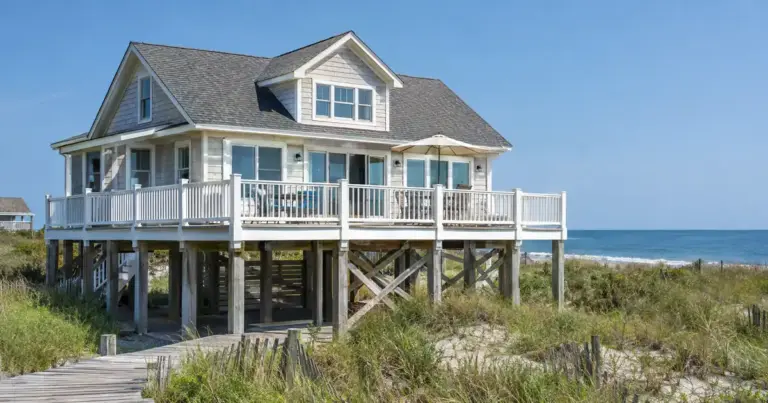
Beach properties add a flood-zone underwriting layer that mountain properties usually skip.
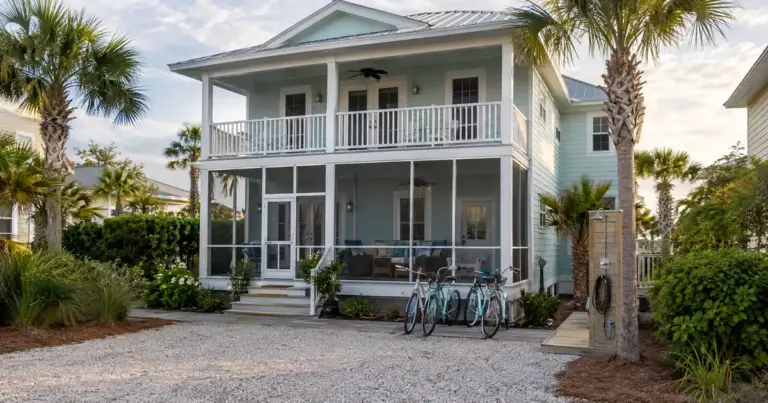
STR DSCR Vs Bank Statement Loan — These two programs qualify a beach house buyer in completely different ways.
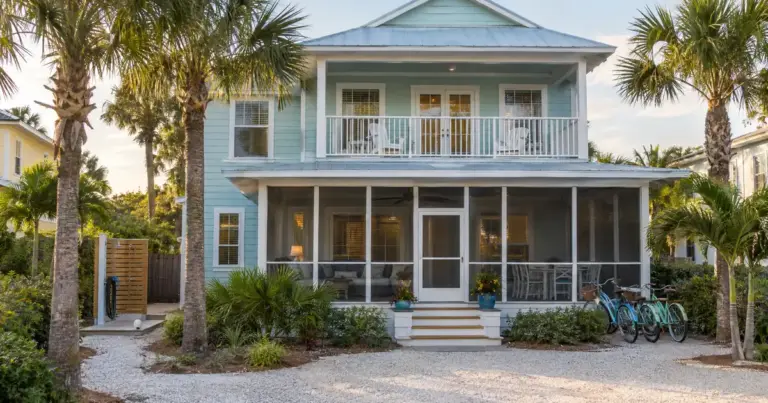
The two products don’t compete for the same file. They serve two different intentions for the same house.
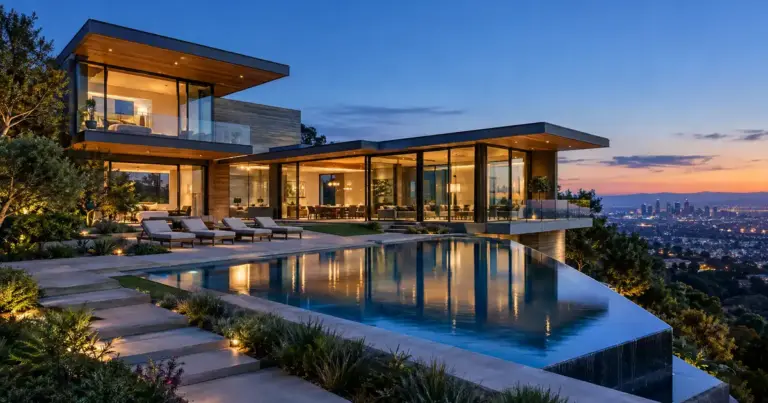
Both paths close through the same programs. The differences show up after closing.
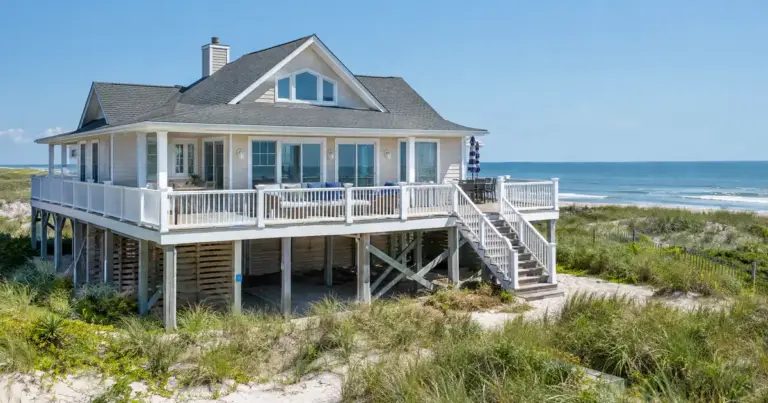
A short-term rental DSCR loan qualifies on the property’s rental income instead, so a windfall that doesn’t show up as ongoing income stops being a problem.
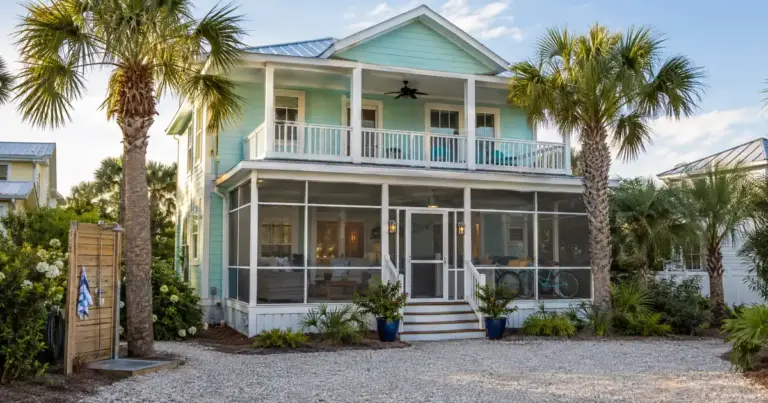
DSCR loans qualify the property’s rental income instead of your tax returns, they vest directly to an LLC, and they don’t stop at ten financed properties.
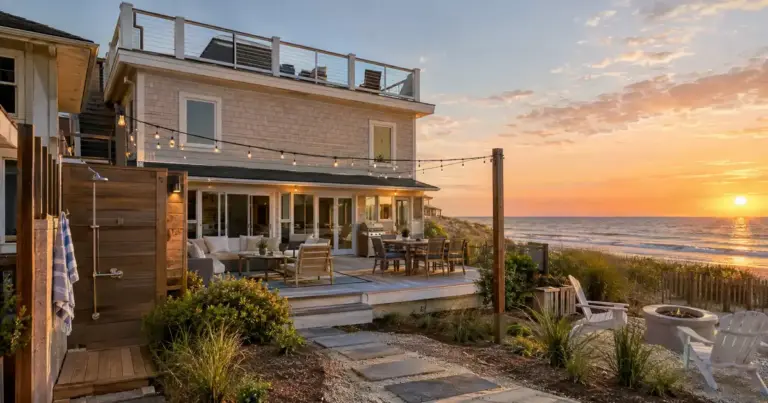
Short-Term Rental DSCR — A DSCR loan fits a retiree who buys the beach house as a true rental and will barely use it personally.
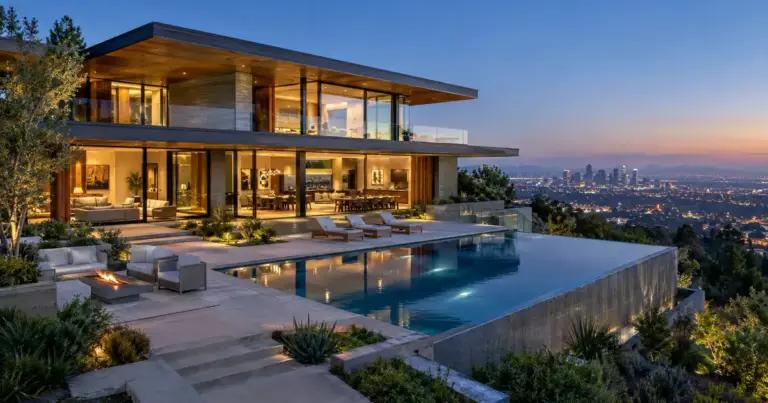
Jumbo Vs Super Jumbo Short-Term Rental — Neither term has a legal definition on the DSCR side of lending.
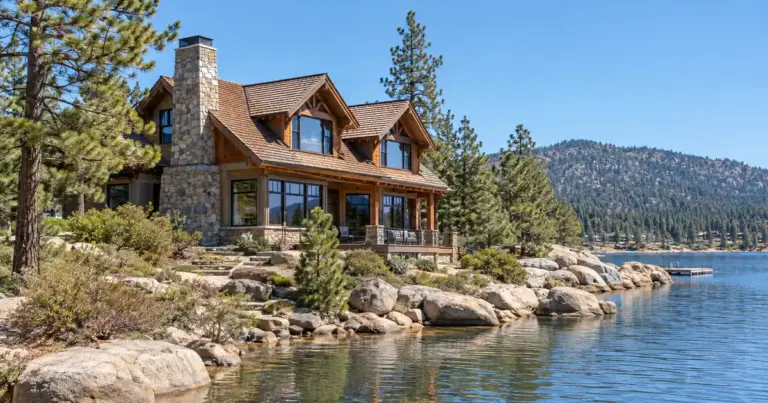
Luxury Rental DSCR Loans in Big Bear Lake — A seasonal luxury cabin doesn’t underwrite on its best month.
A DSCR loan qualifies the property itself, using its rental income to cover the payment, and it requires the home to be a non-owner-occupied rental.
It takes a formed entity, a clean operating agreement, matching names on every document, and a lender willing to underwrite the entity itself.