Super Jumbo DSCR Loans In Southlake
There is no federal line marking where “jumbo” becomes “super jumbo” — it is a lender-defined tier, and every wholesale program draws it differently.

 Lendmire Research
There is no federal line marking where “jumbo” becomes “super jumbo” — it is a lender-defined tier, and every wholesale program draws it differently.
Luxury Rental DSCR Loans in Annapolis — A DSCR loan qualifies a rental property on the rent it produces, not the owner’s tax returns.
The two products solve different problems, and mixing them up is the single most common way a self-employed buyer’s file stalls mid-transaction.
The product exists for one reason: tax-return income and real cash flow often don’t match, especially for high earners running a business.
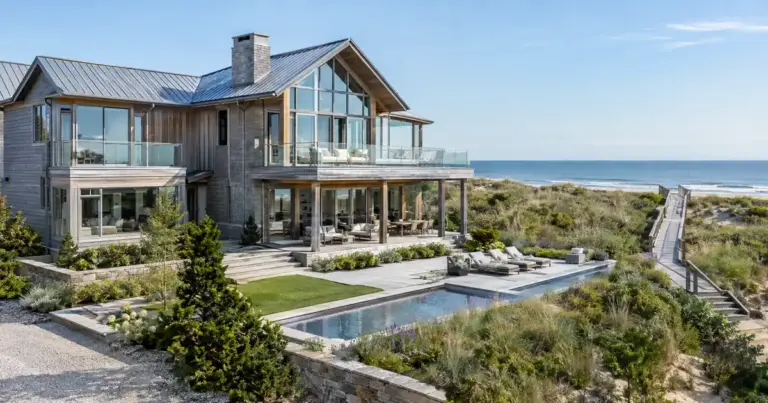
Loan sizes on this path run from $300,000 to $30,000,000 through two separate wholesale programs, each with its own leverage ladder.
A lender divides eligible assets by a set number of months and adds that number to any other income you have.
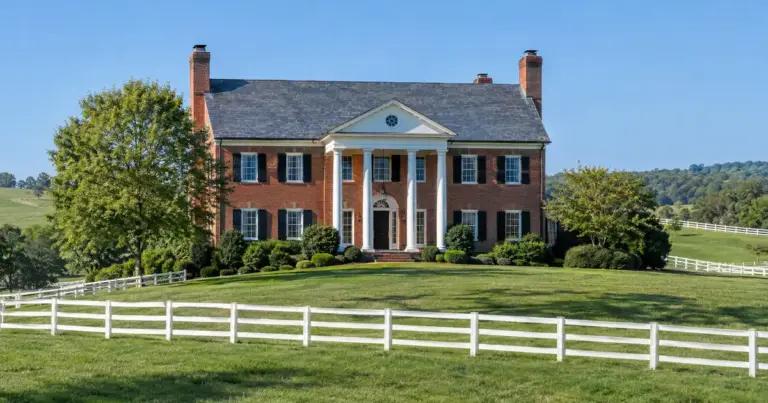
Second Home in Middleburg — A second home doesn’t have to be financed off a tax return.
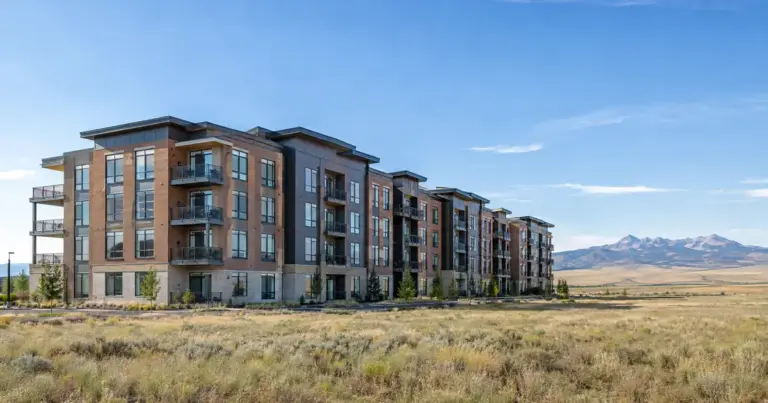
Nothing in this article describes Great Falls, Montana, or any specific city’s rental market.
Leverage steps down and reserve requirements step up as the loan gets bigger.
Bank statement programs solve the qualification problem for self-employed buyers by reading 12 or 24 months of deposits instead of a tax return.
Leverage steps down as the loan gets bigger — 90% on a smaller primary-residence file, down to the 55%-65% range once a loan crosses into eight figures.
What actually gates the loan isn’t the documentation type.
If a business owner plans to use the house personally for part of the year, the file usually runs on personal income or bank statements.
The account balances stay untouched — the math is a qualifying convention, not a withdrawal plan.
That choice can move the coverage ratio by a wide margin, and it usually decides how much leverage the file supports.