Refinancing A Short Term Rental Complete Guide
A conventional mortgage refinance is built around a fixed lease or owner-occupancy — neither of which describes a nightly-rate rental.

 Lendmire Research
A conventional mortgage refinance is built around a fixed lease or owner-occupancy — neither of which describes a nightly-rate rental.
That mismatch is why non-QM, income-based financing — commonly called a DSCR loan — exists as a separate lane for short-term rental buyers.
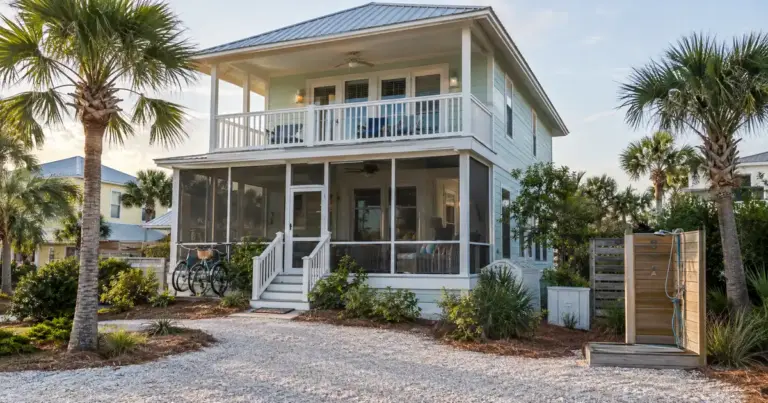
Airbnb Loan Options Explained Airbnb Loan Options Explained — An “Airbnb loan” isn’t a separate loan category.
The rest of this comes down to how the income gets measured, which forms show up in the appraisal, and where the standard playbook breaks down.
Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
This guide walks through how that actually works, where the general rule breaks, and what the decision looks like on a real file.
Approval rests on credit score, equity in the deal, and reserves instead.
Yes — self-employed borrowers qualify for mortgages every day. The path just isn’t identical to a W-2 file.
Points on a rental loan are never deducted in full the year they’re paid — they’re spread across the loan’s life.
Getting statements ready starts 60-90 days before applying, not the week before.
Can You Get HELOC On Investment Property — Yes, but it is a narrow product.
They exist because self-employed borrowers who legitimately write off business expenses often show adjusted gross income far below their actual cash flow.
A duplex, triplex, or fourplex refinances through residential-style DSCR or non-QM channels, qualifying primarily on rent covering the payment.
Self-employed borrowers using a bank statement loan submit 12 to 24 months, because the deposits themselves become the income calculation.