
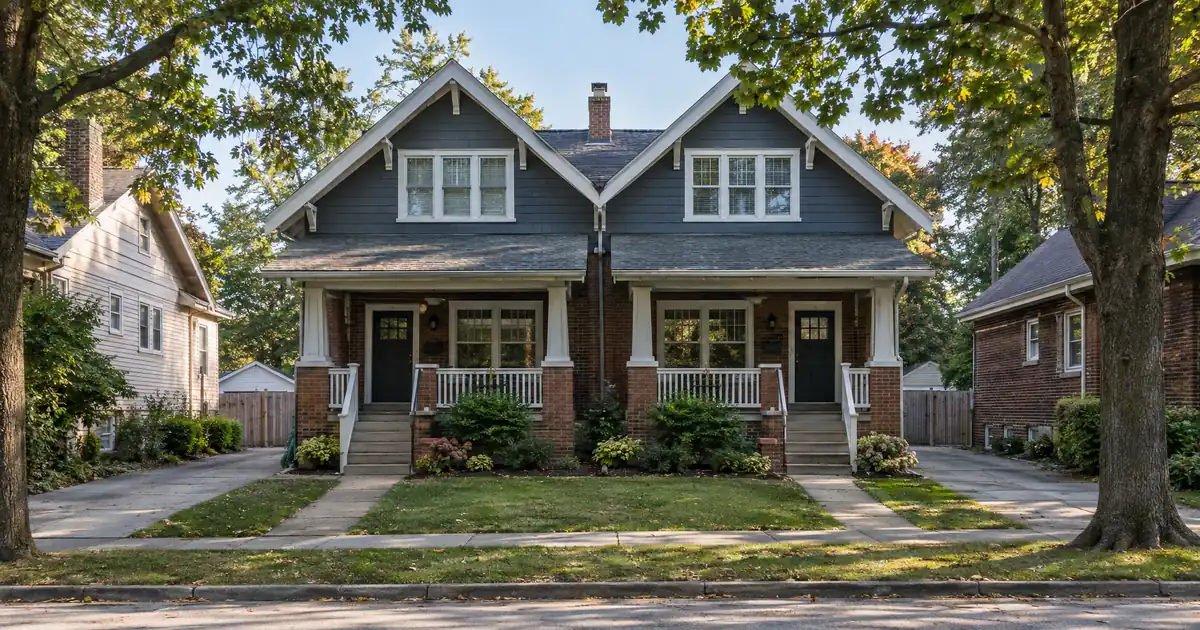
Picture an investor holding a Birdtown double bought a few years back, with both units leased and the mortgage balance well below what comparable sales now suggest. The investor wants to pull part of that equity out and put it toward a second small multifamily building. The first question isn’t “how much can I take?” It’s “what does the building’s rent say once the new, larger loan is on it?”
That question decides how most Lakewood cash-out files go.
DSCR Cash-Out Calculator
Run the cash-out numbers in Lakewood, OH
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 1, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 1, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
TL;DR: A cash-out refinance on a Lakewood, Ohio duplex fits the investor who already owns a small multifamily or single-family rental with built-up equity, because the loan is underwritten primarily on the property’s rental income measured against its full monthly obligation, capped at 75% of appraised value and subject to lender guidelines.
- Median sale price sits near $349K, up 7.5% year over year, per Redfin.
- Duplexes and small buildings make up about 22% of units, per NeighborhoodScout.
- Modeled coverage on an average-priced duplex at full leverage lands near 1.0, taxes and insurance included.
- Cash-out typically needs about 6 months of ownership and a 75% LTV ceiling.
Investors in Lakewood, Ohio work with Lendmire to place DSCR financing through wholesale lenders reaching 41 markets, including D.C. Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker, and the short version of how DSCR qualification works is that the lender looks at the property’s rent, not your paycheck.
Lakewood Market Snapshot
A quick read on the Lakewood investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $350K median listing (Redfin 44107 Multi-Family) |
| Typical rents | $1,070 median (Niche) |
| Recent appreciation | +7.5% yoy (Redfin Lakewood Housing Market) |
How Does Equity Actually Come Out? The Mechanism
A cash-out refinance replaces your current loan with a new, larger one, and you keep the difference after payoff and closing costs. The ceiling is 75% of the appraised value on a DSCR cash-out. Not 80%. The higher purchase-loan figure doesn’t carry over.
Walk through it in percentages. Say the appraisal comes in at 100 “units” of value. The 75% ceiling means the new loan can’t exceed 75 of them. If your existing balance equals 50% of value, the gross room is 25 units, and closing costs and required reserves come out of that. Proceeds are never a guaranteed figure. They depend on the appraisal, the rent and the monthly obligation the new loan creates.
Three other mechanics matter. First, seasoning: lenders typically look for about 6 months of ownership measured from title recording before they’ll treat the appraised value, not your purchase price, as the basis. Second, reserves: on most files, expect to document roughly 6 months of PITIA (principal, interest, taxes, insurance and any HOA dues) in liquid funds. Third, credit: programs typically start around a 620 score, with better terms generally available at higher tiers. All of this is subject to lender guidelines, and the specifics of rate-and-term and cash-out refi details vary by borrower and property.
The ratio itself is simple. Divide the monthly rent by the full monthly obligation. The standard baseline is 1.00x, meaning rent covers the payment. Some lenders review lower ratios, but usually with lower leverage, stronger credit or more reserves.
Why Lakewood Comps Tend to Support the Appraisal
Lakewood’s sale prices are still climbing, which is what a cash-out needs. According to Redfin, the three-month data shows a median sale price of $349K, up 7.5% year over year, with price per square foot at $219, up 12.0%. That second figure matters. Per-square-foot values rising faster than the median suggests smaller and older homes are repricing too, and older doubles are exactly the stock an investor here is likely to own.
The market has cooled from its peak pace, though. Average days on market rose to 27 from 13 a year earlier, according to the same Redfin page, while May sales ticked up to 167 from 156. For a cash-out, that’s mildly good news. An appraiser is less likely to lean on stale bidding-war comps, and roughly 160 sales a month is a deep enough pool to support a valuation.
Here’s the catch. Rising prices pull rent-to-value ratios down. The equity is real, but the rent doesn’t automatically rise with it. That tension between appreciation and cash flow is the defining feature of this market.
Lakewood is also dense. Census Bureau QuickFacts puts it at 50,229 people packed into 5.5 square miles, about 9,062 per square mile. The U.S. Census Bureau shows a July estimate of 49,337, down 3.1% from the 50,941 base. A slightly shrinking population on a fixed footprint isn’t alarming, but it argues against underwriting aggressive rent growth.
Run the Numbers on a Duplex (Before You Pull Cash)
At full leverage, an average-priced Lakewood duplex covers right around 1.0 at best, and often a little under. That’s the honest read.
Realmo’s listing data shows a healthy set of duplexes for sale, with asking prices spanning a wide range and landing at an average near the high-$300Ks. Treat that as listing-based, not a closed-sale median. It sits close to the citywide median for all home types, which means a duplex costs about what a single-family house does and gives you two rent rolls. Redfin’s 44107 multi-family page shows a similar picture, with a comparable number of listings and a median listing price in the same general range.
Now model it. These are assumptions, not sourced market facts. Assume a duplex appraising near that $367K listing average, a 75% LTV cash-out, and two units each renting at a modeled $1,100. Full PITIA, meaning the new loan’s principal and interest plus taxes and insurance, produces a coverage number in the low 0.9s. Swap in RentCafe’s $1,223 citywide average rent per unit and the number moves up to roughly 1.0, rounded down and including taxes and insurance. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
So what happens below 1.00? A lender may review other structures: a sub-1.00 program, an interest-only period, or a smaller cash-out request. Any of these typically comes with lower leverage, stronger credit or heavier reserves, and eligibility depends on lender guidelines, credit approval and property review.
The better lever is often the simplest one. Take less cash. A cash-out at a lower LTV leaves a smaller loan against the same rent, and coverage improves with every point of equity you leave in. If you’re reaching for the full 75% on a building whose rent can’t carry it, treat that as a signal to re-examine the property, not the loan type.
One more consequence of the Realmo inventory: it shows 19 duplexes, 3 apartment buildings, 2 triplexes and 1 fourplex. Duplexes dominate. An investor who plans to roll proceeds into a fourplex-heavy strategy here will find very little to buy.
Where the Equity Sits: Birdtown, the Gold Coast and the Detroit Avenue Corridor
Birdtown is the most natural fit for the strategy. Homes.com describes it as a former factory neighborhood of duplexes and worker’s cottages, and that stock is what small-balance DSCR files are built around. Listing-based rent data puts Birdtown two-bedrooms close to the citywide figure, so coverage math here looks like the duplex scenario above. The caution is comps. Redfin’s Birdtown page rests on only two recent sales, far too thin to quote as a median, and thin comps are what make a cash-out appraisal harder to support. An appraiser may reach beyond the neighborhood, so don’t assume the number will land where a few listings suggest.
The Gold Coast is the opposite story. Lakefront high-rises and condos carry the highest rents in the city on listing data, but the product is mostly condominium, and condo eligibility is a separate lender question. For a duplex investor it’s a place to understand, not to buy.
Clifton Park and Lakewood Park are premium owner-occupant pockets. Redfin’s Lakewood Park page rests on six sales, a sample too small to treat as a price band. High values and modest rents usually mean thin coverage, so appreciation-led owners here may find the cash-out math harder than the equity suggests.
Downtown and the Detroit Avenue corridor carry the supply question. The City of Lakewood says Lakewood Common, a $119 million mixed-use project on the former hospital campus, includes 303 housing units. The hospital had been city-owned for most of the last century before it closed, per the Encyclopedia of Cleveland History. My read, and it’s an inference, not sourced absorption data, is that new Class A units will compete with older apartments right along Detroit Avenue. Older doubles a few blocks off the corridor face less direct competition.
Demand anchors are mostly healthcare and public employment. Cleveland Clinic’s Fairview Hospital sits just outside the city line with 488 licensed beds, and the Clinic’s Lakewood Family Health Center on Detroit Avenue anchors a family medicine residency that has trained more than 100 physicians. I found no verified headcounts, so describe the scale by beds and programs rather than payroll. The point for lenders is steady long-term tenant demand from workers who want a walkable address.
What Do You Do With the Proceeds?
The cash-out thesis depends on the destination. Rolling equity into a second Lakewood duplex works if the next building’s coverage clears on its own, because you aren’t stacking one thin file on top of another. Rolling it into a market where the math doesn’t pencil is a different decision, and one to stress-test first.
There are also flip points. DSCR typically makes sense for the investor who holds properties in an LLC, has several financed doors, or has traditional personal-income documentation that doesn’t show the rental income cleanly. If you’re a high-W-2 borrower with one or two rentals owned personally, conventional financing may carry a lower cost and be worth pricing first. The break-even tends to arrive somewhere around the third or fourth financed property. Conventional vs DSCR on investor loans walks through that comparison. For LLC-titled properties, eligibility is subject to lender program requirements.
Lendmire’s deal desk tends to see the same friction point in dense, older-housing markets like this one. Appraisals come back fine, but the file stalls on coverage after the new, larger loan is layered on, and the cleaner files usually arrive with a current lease for each unit and a tax and insurance estimate already in hand. Investors who choose their cash-out amount after seeing the coverage number, rather than before, generally have fewer surprises. For details on structure, see Lendmire’s DSCR cash-out refinance page.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Lakewood, OH, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
This one’s a genuine toss-up for some owners: pull the maximum while appraisals are strong, or hold equity because 27-day average market times suggest the pace is softening. Neither is wrong. A smaller pull now that preserves coverage and leaves room for a later one is the more defensible middle path.
Rental rules, taxes and insurance vary and change, so confirm current local requirements with qualified local professionals before you buy or refinance.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Lakewood, Ohio?
The property’s rent has to cover its full monthly obligation, typically at a 1.00 baseline, with a 75% LTV ceiling and about 6 months of ownership. Lenders also review credit, with scores starting near 620, and about 6 months of reserves. Exact eligibility depends on lender guidelines and the property.
What are the requirements for an investment property loan in Lakewood, Ohio?
Expect a lease or market-rent appraisal, a credit review, reserves and a property that fits program rules. Duplexes through fourplexes and single-family rentals generally fit. Manufactured homes, log homes and barndominiums fall outside these programs. Loan amounts run up to $3,000,000 on standard programs, with smaller balances placed through select lenders.
Is a duplex or a single-family home better for a Lakewood cash-out?
A duplex usually works better for coverage. It costs about what a single-family home does and produces two rents, so the same loan balance is spread across more income. A single-family rental can still work if the appraisal is strong and you take a smaller cash-out.
Can I pull cash out of a Birdtown duplex I bought recently?
Typically only after about 6 months of ownership from title recording. Before then, lenders usually base value on the purchase price. After seasoning, a fresh appraisal can reflect Lakewood’s rising comps, though thin neighborhood sales may make the appraiser look citywide.
What DSCR terms may lenders review for investors in Ohio?
Lendmire arranges DSCR investor loans, including Ohio. One key feature is that qualification is based primarily on the property’s rental income, subject to lender guidelines. Investors can request a quote or call 828-256-2183.
What a Local Appraiser Would Tell You
Lakewood doubles don’t sit on the market long enough to go stale, and the good ones appraise on their neighbors, not on their lists. Buy the building the rent can carry, pull only the equity the coverage number supports, and the Detroit Avenue grid has been repaying that discipline for a century.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage focused on DSCR investor financing, helping arrange programs through wholesale and investor-lending channels in 41 markets, including Washington, D.C. Lenders evaluate DSCR loans on property cash flow rather than personal income, subject to lender guidelines, which supports LLC closings and investors with four or more financed properties. Lendmire was named a Scotsman Guide Top Mortgage Workplace in both 2025 and 2026. Investors can also review Lendmire’s Ohio DSCR loan page for details on that market.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin: Lakewood Housing Market
2. NeighborhoodScout: Lakewood Real Estate
3. Redfin: 44107 Multi-Family Homes for Sale
4. Niche
5. U.S. Census Bureau QuickFacts: Lakewood city, Ohio
7. RentCafe’s
8. Homes.com
9. City of Lakewood: Downtown Development
10. Encyclopedia of Cleveland History: Lakewood Hospital
11. Cleveland Clinic: Fairview Hospital
12. 2025
13. 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Lakewood, Ohio: Pulling Duplex Equity in Birdtown · DSCR Loans Anna Maria Island & Bradenton: Investor Financing for Holmes Beach, Bradenton Beach, Lakewood Ranch & Real Estate Investors · DSCR Cash Out Refinance in Fairfield, Ohio: Turning Workforce Rental Equity Into Capital
Guides: Investment Property Cash-Out Refinance in Ohio
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.