
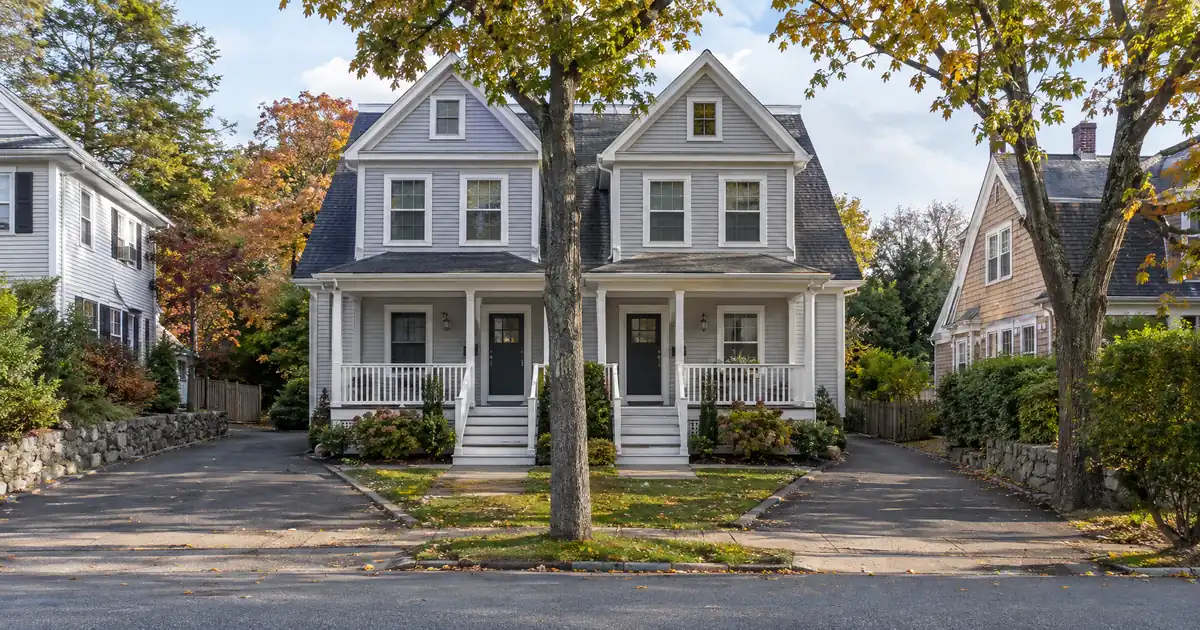
Weymouth has roughly 58,505 residents per Census Bureau QuickFacts, yet Homes.com showed only 3 multi-family homes for sale, priced from $499,900 to $1,499,000. That is the thing to understand before pulling equity here. The town has no downtown. It has four village centers, and the small-multi stock sits in two of them. Owners who already hold a two-family or three-family are sitting on the scarce asset. The file work is proving that asset’s income, and an appraiser may have very few like-kind sales to lean on.
DSCR Cash-Out Calculator
Run the cash-out numbers in Weymouth, MA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 1, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 1, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
At a Glance:
A DSCR cash-out refinance in Weymouth, Massachusetts is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the file runs from title recording and seasoning, through lease and rent documentation and an appraisal that may lean on thin comps, to a reserves check before proceeds are released.
- Cash-out LTV tops out at 75 percent, with seasoning of about 6 months from title recording.
- Weymouth Landing’s median rent is $2,900 per Redfin’s rental data, a thin all-unit sample.
- The town-wide median sale price is about $650K per Redfin.
- A single-family rental at that price models in the mid-0.8s including taxes and insurance.
- Stacked units are the main way to lift coverage above 1.00 here.
Weymouth Market Snapshot
A quick read on the Weymouth investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $650K 3-month median (Redfin, Weymouth housing market) |
| Population | 58,505 population (Census Reporter, Weymouth) |
Weymouth Landing: Where the Rent Is Highest
Weymouth Landing carries the strongest rent in the town data, and it is also the village where two-families show up most often in listings. Redfin puts the median rent at $2,900. Apartments.com shows a Landing average of $2,387 with a range of $2,106 to $3,428, and 2-bedrooms near $3,017.
Read those numbers skeptically. The Redfin figure is an all-unit median from a thin sample. The Apartments.com figures lean on professionally managed complexes and include fees. A 1960s two-family with a dated kitchen does not rent like either one. Underwrite to the rent the unit’s condition earns, not the top of the asking range.
The demand story is commuter-driven. The Landing sits at the commuter rail node on the Braintree line, and the Town of Weymouth notes three MBTA commuter rail stations connecting the town to Boston. Tenants who work in Boston and want a rail platform near home are the plain target. That tenant base is tied to employment and transit, which is what lenders look for in rent support.
An older Redfin read placed the Landing’s median sale near $650K, close to the town-wide median. That page is stale, so treat it as direction only. The point holds anyway: the Landing pairs the town’s highest rents with a price level near the middle of the market. For a cash-out, that is the combination that supports coverage on a refinance of an owned two-family.
East Weymouth (If the Number Holds)
East Weymouth looks cheaper on paper, but one comp should make an investor slow down. Redfin’s East Weymouth housing page shows a $480K median over the last three months, down 26.5 percent year over year. That is an all-types median. It probably reflects a condo-heavy mix, though the source does not say so, and that is a read, not a fact. Do not hand that figure to an appraiser as a two-family comp.
The multi-family listing data is more useful, if tiny. Redfin’s East Weymouth multi-family page showed 3 listings at a $750K median listing price. Listings are asks, not closed sales. Still, the buildings in that sample include a two-unit with a 1-bedroom downstairs and a 2-bedroom upstairs. That is typical of the stock: modest units, mixed bedroom counts, and rents that land below the town’s headline averages.
Redfin’s rental page shows an East Weymouth median rent of $2,300. The village takes in Whitman’s Pond, Jackson Square, and Town Hall, with a longtime resident base and commuter rail at Jackson Square. Demand is steady. The rent ceiling is lower than at the Landing. On a cash-out, that lower ceiling matters more than the price softness, because rent is the numerator in the coverage ratio.
South Weymouth and Union Point: Supply Is the Catch
South Weymouth is where the hospital sits, and it is where the biggest supply question in town lives. The Town of Weymouth calls South Shore Health the largest employer and describes more than 20 medical buildings housing over 100 laboratories, physician groups, and treatment centers. South Shore Health runs South Shore Hospital on Fogg Road, so workforce demand here is tied to a real employment anchor. Apartments.com’s South Weymouth page adds that transit options are very limited. These tenants drive.
Then there is the former Naval Air Station. The Town’s Union Point notice describes a 1,400-acre project spanning Weymouth, Rockland, and Abington. The joint venture’s proposal calls for 6,500 housing units and about two million square feet of commercial and retail space. Other reports cite different unit counts, so “thousands of planned homes” is the safe description. The state has put money behind it: Speaker Ron Mariano’s office announced a $32.4 million award for public infrastructure.
Here’s the catch. New construction sets the rent ceiling for small landlords. Apartments.com’s Weymouth listings show a newer community with studios from $1,970, 1-bedrooms from $2,174, and 2-bedrooms from $2,534, fees included. Redfin’s apartment listings show another at $2,187 and up. An older two-family competes with those. No sourced vacancy or absorption figure exists for Weymouth, so nobody can say how fast new supply is leasing. An investor refinancing against today’s rent should ask what happens to that rent when thousands more units arrive.
Honestly, this one is a toss-up. Union Point could lift the whole town’s profile and appraisals. It could also cap rents on older stock. A cash-out that assumes only the first outcome is underwriting hope.
What Does the Math Look Like on a Cash-Out Here?
At Weymouth prices, a single-family rental struggles to clear 1.00, while a two-family with two decent rents clears it with a margin. The renter pool is also limited: RentCafe counts 8,157 renter households, 32 percent of the total, against 68 percent owner-occupied. Rental is the minority tenure here.
Run the numbers on a modeled single-family at the town median of about $650K, appraised at that value and refinanced at 75 percent LTV. These are assumptions, not market data. Use RentCafe’s 3-bedroom average of $3,414 as the rent. Coverage lands in the mid-0.8s once you include taxes and insurance in the full monthly obligation. The loan is below 1.00 on long-term rent alone.
Now model a duplex appraised near $750K, the East Weymouth median listing price, at the same 75 percent. Stack a 3-bedroom and a 2-bedroom at RentCafe’s averages of $3,414 and $2,645, and coverage models in the low-1.2 to 1.3 range including taxes and insurance. Haircut those rents by 15 percent to reflect older condition, and the number drops to roughly 1.1. The rent source matters because those are averages across all apartment types, not two-family comps. Confirm actual leases and ask the lender how it counts income on 2-4 unit properties.
When a file lands below 1.00, a few structures may apply, all subject to lender guidelines, credit approval, and property review: a sub-1.00 program with lower leverage, an interest-only structure that lowers the monthly obligation, or a smaller cash-out request. None of these is guaranteed. Most standard programs are built around a 1.00x benchmark because rent covers the payment at that level. Some lenders review lower ratios, but that usually means more cash in, lower leverage, or different pricing. The full DSCR explainer covers how the ratio is built. For the dollar conversion on a specific file, run the numbers with Lendmire.
Seasoning, Appraisal, and the Thin-Comp Problem
Seasoning is mechanical. Programs in the network generally look for about 6 months of ownership before cash-out, measured from title recording and documented with the settlement statement. Files that assume seasoning away get kicked back. Clearing title cleanly, with the deed recorded and the settlement statement reconciled to the purchase, avoids the first preventable gap.
The appraisal is where Weymouth files get tested. The zip 02188 data on Redfin shows a $560K median for the three months ending May, down 3.5 percent year over year, with 22 homes sold against 29 a year earlier. With so few multi-family listings, an appraiser may reach for a wider radius or lean on single-family sales. Underwrite the refinance value conservatively. Do not assume a peak-price appraisal.
Working DSCR brokers see a recurring pattern in thin-inventory, small-multi markets like this one: the appraisal comes in on single-family comps, the value lands below the owner’s expectation, and the 75 percent cap cuts the proceeds more than the investor planned. A well-built appraisal reconsideration packet, with recent in-town two-family sales, condition adjustments, and a clean rent schedule, recovers value more often than a bare request does.
On the other side of the ledger, the price trend helps. Redfin’s housing market page shows a town median near $650K, up 3.1 percent year over year, with price per square foot at $436, up 10.4 percent. Homes sell about 2 percent above list on average. Prices are firm. That supports value on a refinance, though the same high entry price is why rents struggle to cover single-family debt. This is an appreciation-led market with thin cash flow.
Documentation is where preventable friction lives:
- Entity documents. LLC-held rentals can be eligible, subject to lender program eligibility, but operating agreements and good standing certificates need to match the vesting on title.
- Leases and rent roll. Signed leases for every unit, with a rent schedule that matches. Mixed-use or owner-occupied units on a 2-3 family need a clear story.
- Reserves. About 6 months of full monthly obligation is typical, about 9 months above $1,500,000, with statements showing the funds.
- Insurance. A complete quote for the subject property, so the monthly obligation in the file matches reality.
Credit tiers generally run 620, 660, 680, and 700, with 620 as the floor, and loan amounts reach up to $3,000,000 on standard programs, subject to lender guidelines. For deeper mechanics, see the guide “The Refi Options”.
Where the Proceeds Go
The equity pulled out of a Weymouth two-family has to land somewhere, and Weymouth itself offers few places to put it. With so few multi-family listings, a buyer hunting the next two-family here is working a thin shelf. Proceeds often make more sense deployed into other Massachusetts markets where small-multi inventory is deeper, or held as reserves that strengthen the next file. The Massachusetts DSCR investor loans page covers that side of the state.
Another option is the existing hold. Some owners refinance not to buy, but to reposition: renovate an older two-family to compete with new supply, then lift rents. That only works if the renovated rent shows up in the numbers an appraiser and lender will accept. Lendmire’s refi programs cover the rate-and-term path too, for owners who want a cleaner structure without pulling cash. And for investors weighing paths, conventional vs DSCR on investor loans lays out the tradeoff.
One caution that applies everywhere in town: verify current local rental rules, taxes, and insurance with qualified local professionals before sizing a cash-out.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Weymouth, MA, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Weymouth, Massachusetts?
Qualification centers on the property’s rental income measured against its full monthly obligation, with a 1.00 ratio as the typical benchmark. The file also needs about 6 months of ownership from title recording, a credit score at or above the 620 floor, and reserves of about 6 months. Final eligibility depends on lender guidelines, credit approval, and property review.
What are the requirements for an investment property loan in Weymouth, Massachusetts?
For cash-out, expect a 75 percent LTV ceiling, seasoning near 6 months, reserves, and signed leases supporting the rent used in the ratio. Entity documents are needed if an LLC holds title. Manufactured homes, log homes, and barndominiums fall outside these programs. Details vary by lender and loan scenario.
Does Union Point construction threaten rents on existing Weymouth two-families?
It can cap them. New communities in town list 2-bedrooms from $2,534 with fees included, and the redevelopment proposes 6,500 housing units over time. Older two-families compete on condition, not amenities. Underwrite to the rent the unit earns today, and stress-test a lower figure.
Can a single-family rental in Weymouth support a cash-out refinance?
Modeled coverage on a town-median single-family lands in the mid-0.8s including taxes and insurance, below the 1.00 benchmark. Lower leverage, a sub-1.00 program, or an interest-only structure may be reviewed, but none is guaranteed. Two-families with stacked rents give much better odds.
Weymouth or Braintree?
Against Braintree, which shares the Landing’s commuter rail corridor, Weymouth gets the edge right now on one count: owners already holding a Landing or East Weymouth two-family have equity to pull, while buyers chasing the next one face a thin shelf. For cash-out, Weymouth. For fresh acquisitions, look past it.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. Eligibility is generally reviewed around property-level rental income rather than personal income, subject to lender and program guidelines, which suits self-employed investors and LLC-owned portfolios. Lendmire was named a top-ranked workplace in 2025 and a 2026 Scotsman Guide Top Workplace. Call 828-256-2183 to talk through a Weymouth file.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Census Reporter, Weymouth profile
2. Homes.com, Weymouth multi-family
4. Redfin, Weymouth housing market
7. Town of Weymouth, About Weymouth
9. Redfin’s East Weymouth multi-family page
10. Apartments.com’s South Weymouth page
11. Town of Weymouth, Union Point notice
12. Speaker Ron Mariano’s office
13. Apartments.com’s Weymouth listings
14. Redfin’s apartment listings
15. RentCafe, Weymouth rent trends
16. Redfin — ZIP 02188 Housing Market
17. Scotsman Guide — Top Workplaces 2025
18. a 2026 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Guides: Investment Property Cash-Out Refinance in Massachusetts
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.