Complete Guide For A 1099-only Loan On Single-family Properties
Underwriting looks at what the 1099s actually show, not the net figure left over after business write-offs.

Underwriting looks at what the 1099s actually show, not the net figure left over after business write-offs.
Twenty-four months of statements smooths out a bumpy income year that twelve months alone might penalize.
That’s a fundamentally different product from a DSCR loan, which sizes the loan around the property’s rental income instead of the borrower’s.
Whether the file runs through consumer disclosure rules or business-purpose rules depends entirely on whether the owner lives in one of the units.
Multifamily 5+ Bank Statement Loan Complete Guide: what borrowers need to know about bank-statement and self-employed financing, from Lendmire.
Whether the file is treated as a consumer mortgage or a business-purpose loan depends entirely on who is going to live in the house.
It solves a real documentation problem — but it’s a narrower tool than most STR owners expect.
Complete Guide For A 1099-only Loan On Multifamily 5+ Properties — what borrowers need to know, from Lendmire.
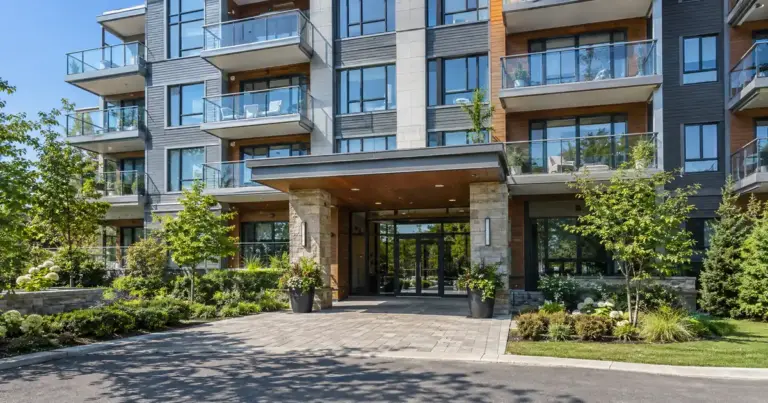
But the condo runs through its own separate review.
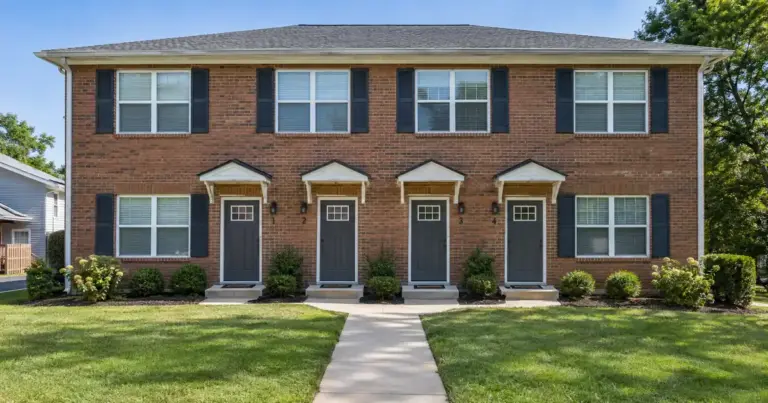
It fits self-employed buyers who earn on 1099s and want a duplex, triplex, or fourplex. Occupancy decides everything.
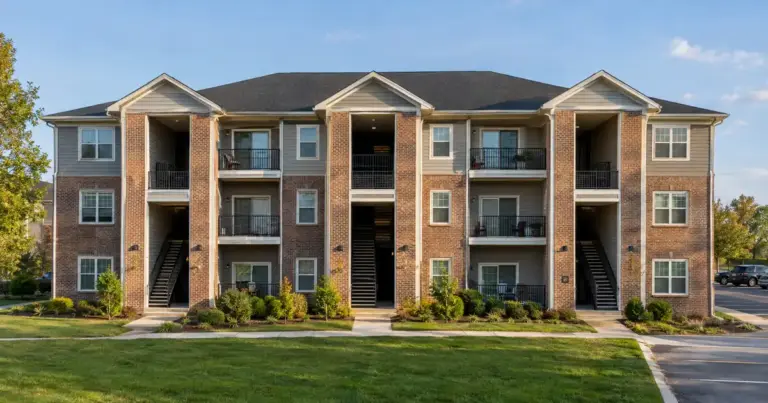
One is the five-unit threshold that reclassifies a property from residential to commercial multifamily.
The longer window smooths that swing into one averaged monthly figure, but it also dilutes a strong recent year with an older, weaker one.
Either file can sink the deal on its own, regardless of how strong the other one looks.
It’s a consumer mortgage, which matters most when one unit is owner-occupied.
Bank statement underwriting solves a consumer-mortgage problem tied to a four-unit ceiling.