Short-term Rental DSCR Loans For Physicians Buying A Resort Property
That matters because physician mortgage programs are built for primary homes only — they won’t touch a vacation rental.

That matters because physician mortgage programs are built for primary homes only — they won’t touch a vacation rental.
It mostly shows up on short-term-rental financing, not standard long-term rental purchases.
Insurance sits inside that denominator. Raise the premium and the ratio drops, even if the rent stays exactly where it was.
Do Seller Credits Affect Leverage On A DSCR Rental Loan — No.
Coverage runs off booking history or an appraiser’s short-term-rent analysis, not a nightly rate multiplied by 30.
Luxury Beach House DSCR Loans — A luxury beach house rarely earns the same income every month, and that’s the whole underwriting problem.
A lender looks at what the property earns, or is projected to earn, on Airbnb or Vrbo, and compares that number to the monthly payment.
Leverage steps down as the loan gets bigger, credit and appraisal requirements get tighter, and cash-out disappears above $3,000,000.
Does The DSCR Coverage Test Use The Interest-only Payment — Yes.
The lender looks at the rental property’s income, not the founder’s K-1s or capital-gains history.
The appraiser pulls comparable rentals, adjusts for condition and location, and lands on a monthly figure that becomes the top half of the coverage ratio.
One rewards speed. The other rewards patience. Picking the wrong one can leave real money on the table.
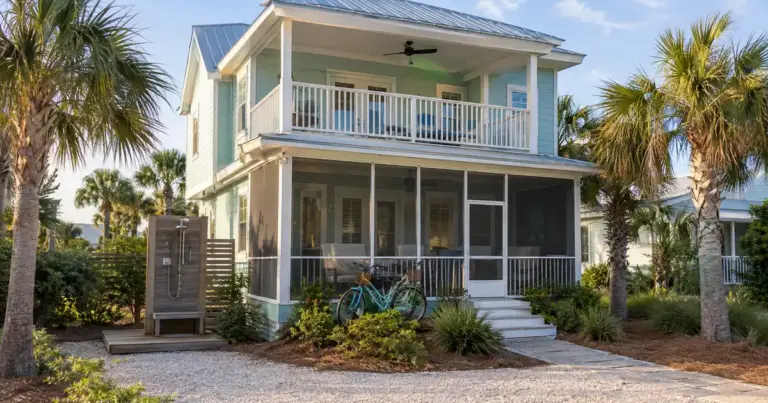
Instead of pulling two years of tax returns, the lender looks at the rental’s own cash flow — bookings, appraisal-based projections, or a blend of both.
If the appraisal lands below your purchase cost, the refinance is capped at the lower number.
Does A Tenant’s Lease Set The Rent On A Jumbo DSCR Purchase — No, not by itself.