Does A Short-term Rental Qualify For A DSCR Cash-out Loan?
Miss any one of those and the file either restructures or stalls.

Miss any one of those and the file either restructures or stalls.
Interest-only improves coverage on a short-term rental DSCR loan by removing the principal portion of the monthly payment from the qualifying math.
Seasoning — the length of time funds have sat in a personal account before a lender will count them as the borrower’s own money without further explanation.
No — not legitimately, and not for long.
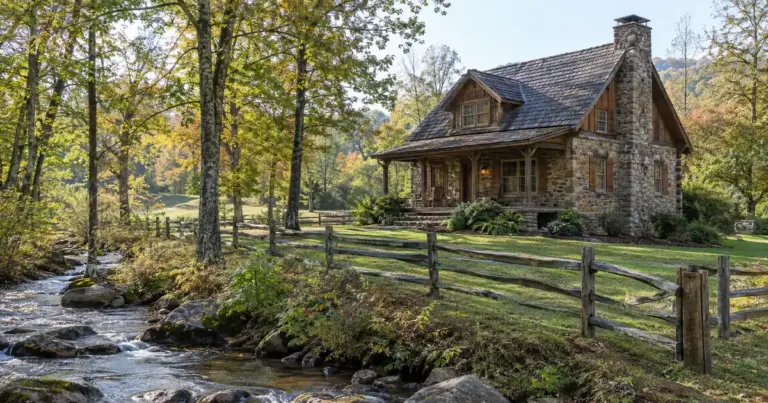
Does A Ski Cabin That Earns One Season Cover Its DSCR Loan Payment — No, not on the strength of one good winter alone.
How DSCR Cash-out Leverage Is Laddered Across An LLC Rental Portfolio — Leverage steps down as your loan balance climbs.
How To Check Resort Rental Rules Before A DSCR Loan Closes: what investors need to know about large-balance DSCR financing, from Lendmire.
That change brings a different loan product, different leverage, and different documentation.
At a Glance: Reserves on a seasonal luxury short-term rental DSCR loan are typically counted as months of PITIA held in liquid, seasoned accounts
The lender wants trailing booking history, not a nightly rate multiplied by 30.
Does Renting Your Vacation Home Void A Second-home Mortgage — Not automatically.
Leverage steps down as loan size climbs, and short-term-rental files cap lower than standard long-term rentals.
That’s not a paperwork technicality — it changes how the loan qualifies you, what income counts, and what you’re allowed to do with the house going forward.
How A DSCR Loan Averages A Ski Cabin’s Seasonal Rent For A Founder — A DSCR loan doesn’t qualify a ski cabin on its best month.
The certification is legally binding — no personal use once the loan closes.