Exit Fee Structure On A DSCR Loan After A Liquidity Event
It triggers when you sell, refinance, or pay off a big chunk of principal early.

It triggers when you sell, refinance, or pay off a big chunk of principal early.
Separate DSCR loans underwrite each property on its own, which keeps a problem on one asset from touching the rest.
Per-property coverage tests each asset on its own, which slows down a weak file but keeps exit flexibility intact.
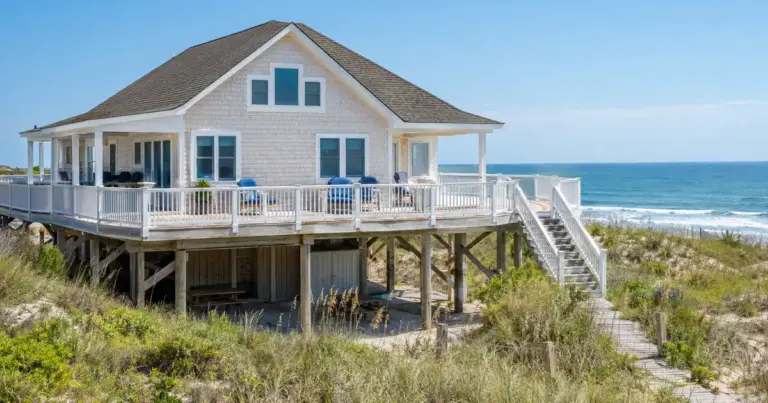
DSCR Vs Asset Depletion For A Business Owner’s Beach House — These two loan types answer completely different questions.
A cash-out refinance pulls proceeds above payoff and closing costs, and that triggers stricter leverage, seasoning, and reserve treatment.
Financing at closing skips that cap and starts the loan on day one, priced off the property’s rental income instead of Social Security or pension paperwork.
Ski Cabin Vs Beach House — Neither wins outright.
Trust titling adds an estate-planning layer — mainly probate avoidance — without changing how a DSCR loan gets underwritten or how rental income gets taxed.
Beach House DSCR Vs Asset Depletion For A Retiree — DSCR loans qualify the property; asset depletion qualifies the person.
Both are business-purpose loans that qualify primarily on the property’s rental income rather than personal tax returns.
Reserves, credit, and entity structure stay the same regardless of who runs the calendar.
Financing at closing gets the loan underwritten before the trustee signs, income documented up front, and leverage locked in on day one.
Managed Vs Co-hosted Luxury Rental — Neither model wins on its own.
The real difference is paperwork and building risk.
Neither choice changes how a DSCR loan gets underwritten, since qualification runs on the property’s rental income either way.