Resort Condo Vs Beach House DSCR For An Asset-rich Retiree
The real difference is paperwork and building risk.

The real difference is paperwork and building risk.
Neither choice changes how a DSCR loan gets underwritten, since qualification runs on the property’s rental income either way.
This article treats the loan question and the tax question as two separate decisions, because they are.
Rent analysis is a projected figure — usually an appraiser’s short-term-rent estimate — used when a property has no operating track record yet.
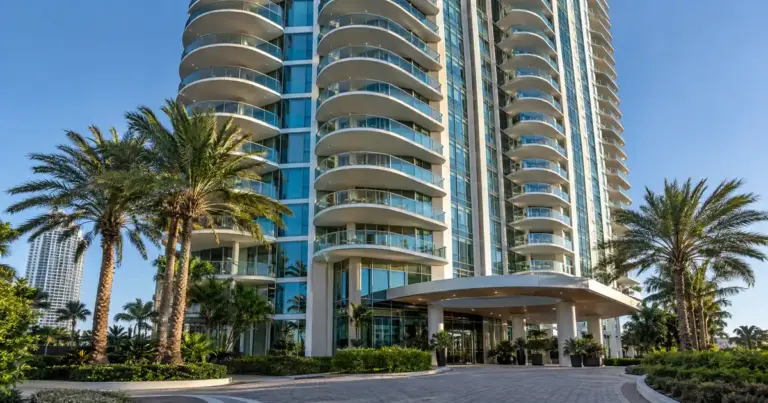
The condo adds a project-level review of the homeowners association — litigation, reserves, delinquencies — that a detached house never faces.
Below the ceiling, leverage runs higher and documentation is lighter.
Amortizing from day one builds equity faster and avoids the payment jump when the interest-only window closes.
A long-term rental is qualified on a signed lease or appraiser market rent, using a standard rent schedule.
One qualifies the loan on the property’s rental income. The other qualifies it on the owner’s personal tax returns and W-2 income.
The lender’s math runs off an appraisal-based market rent, not your operating plan.
Str Dscr Vs Bank Statement Loan For K-1 — A short-term rental DSCR loan qualifies you on the property’s rent, ignoring your K-1 entirely.
A co-hosted listing keeps the platform account in the owner’s name, which usually produces the cleanest, easiest-to-verify income document.
Rate-and-term restructures debt on an existing short-term rental without pulling cash, and it clears underwriting with less friction.
Beach houses concentrate revenue into a summer window and lean hard on flood insurance mechanics tied to federal mapping.
Resort Condo Vs Beach House: How DSCR Underwriting Differs: what investors need to know about large-balance DSCR financing, from Lendmire.