Short-term Rental DSCR Vs Bank Statement Loan After A Liquidity Event
DSCR looks at the property’s rental income, not your personal cash flow — so the lump sum sitting in your account never becomes an underwriting problem.

DSCR looks at the property’s rental income, not your personal cash flow — so the lump sum sitting in your account never becomes an underwriting problem.
Beach properties add a flood-zone underwriting layer that mountain properties usually skip.
STR DSCR Vs Bank Statement Loan — These two programs qualify a beach house buyer in completely different ways.
The two products don’t compete for the same file. They serve two different intentions for the same house.
Both paths close through the same programs. The differences show up after closing.
A short-term rental DSCR loan qualifies on the property’s rental income instead, so a windfall that doesn’t show up as ongoing income stops being a problem.
DSCR loans qualify the property’s rental income instead of your tax returns, they vest directly to an LLC, and they don’t stop at ten financed properties.
Jumbo Vs Super Jumbo Short-Term Rental — Neither term has a legal definition on the DSCR side of lending.
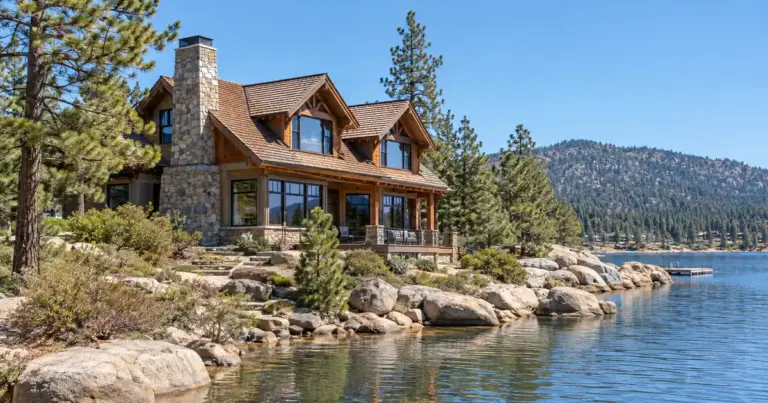
Luxury Rental DSCR Loans in Big Bear Lake — A seasonal luxury cabin doesn’t underwrite on its best month.
It takes a formed entity, a clean operating agreement, matching names on every document, and a lender willing to underwrite the entity itself.
Credit, reserves, and leverage all shift as the loan size grows.
It’s built for higher-value vacation and second-home rentals, where price tags run well past what a standard investor loan covers.
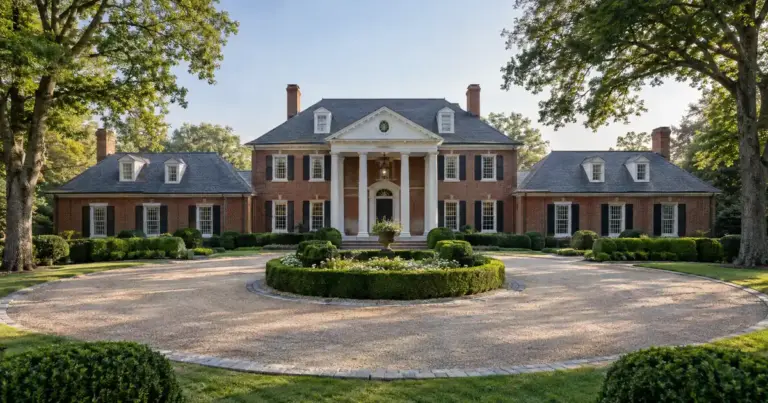
Both terms get thrown around loosely, and that’s the first thing worth untangling before comparing anything else.
The difference only shows up when you read the recorded document, not the marketing brochure.
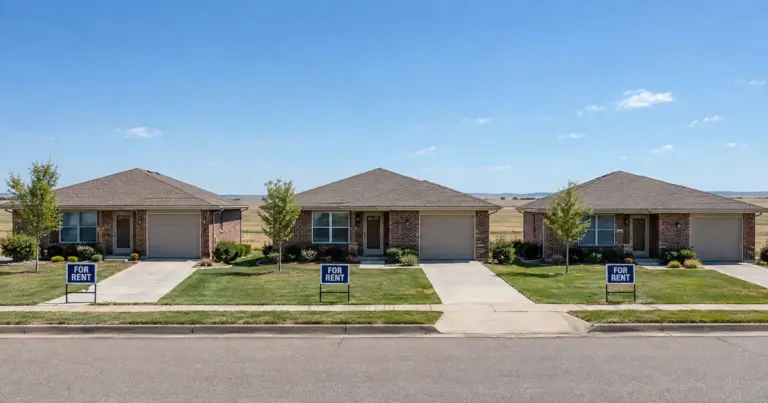
The mechanics matter more than the marketing label. Kansas real property is recorded county by county, not statewide.