Luxury Rental DSCR Loans In Virginia Beach: Seasonality And Coverage
Get the income method right first — the loan size follows from there.

Get the income method right first — the loan size follows from there.
Seasonal income gets discounted and stress-tested before it counts.
The catch here is what “rent” can legally mean.
Underwriters lean on annualized income and build in reserve cushions for the slow months.
Luxury Rental DSCR Loans In Bald Head Island — DSCR loans qualify a Bald Head Island purchase on the property’s projected rental income
Leverage steps down as the loan gets bigger, credit floors rise, and a second appraisal often shows up above $2,000,000.
Below that, the math still works through select programs, but leverage steps down and the file needs more cushion.
The lender compares the rent the property can document against the full monthly obligation — principal, interest, taxes, insurance, and any dues.
For high-rise condos with heavy association dues, that denominator gets bigger fast, and coverage can slip even when the lease looks strong on paper.
For long-term rentals, that number usually comes from an appraiser’s rent schedule.
Luxury Rental DSCR Loans In Palm Desert: How STR Rents Are Read: what investors need to know about large-balance DSCR financing, from Lendmire.
A ratio of 1.00 means the rent exactly covers the payment.
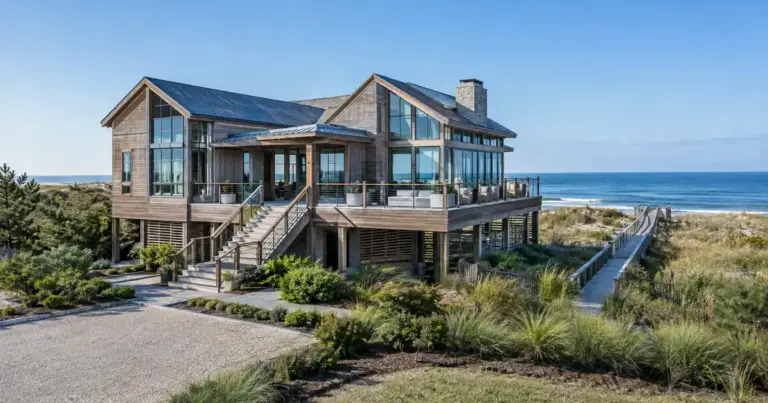
Luxury Rental DSCR Loans in Coronado — A DSCR loan qualifies a rental property on its own income, not the borrower’s tax returns.
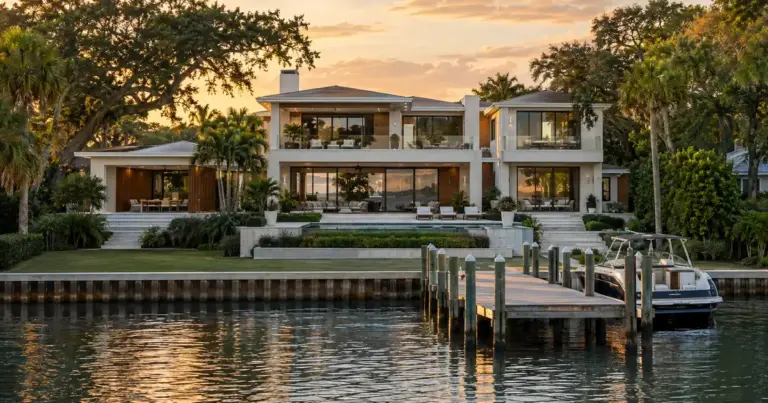
Super Jumbo DSCR Loans In La Jolla — A DSCR loan qualifies on the property’s rent, not the buyer’s tax returns.
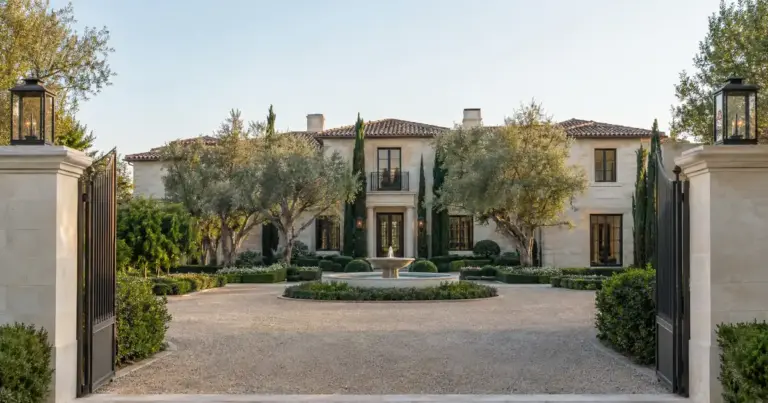
Lenders don’t qualify the file on peak-month cash flow.