How to Meet Reserve Requirements on a Luxury Vacation Rental DSCR Loan
On an interest-only structure, that same six-to-twelve-month test applies to ITIA instead.

On an interest-only structure, that same six-to-twelve-month test applies to ITIA instead.
No bookings history is required to close — the projection stands in for it.
The fix is switching to financing that qualifies the property, not you — DSCR loans size the loan around the rental income the home actually produces.
The math depends on the account type, how long the funds have been sitting there, and how large the loan is.
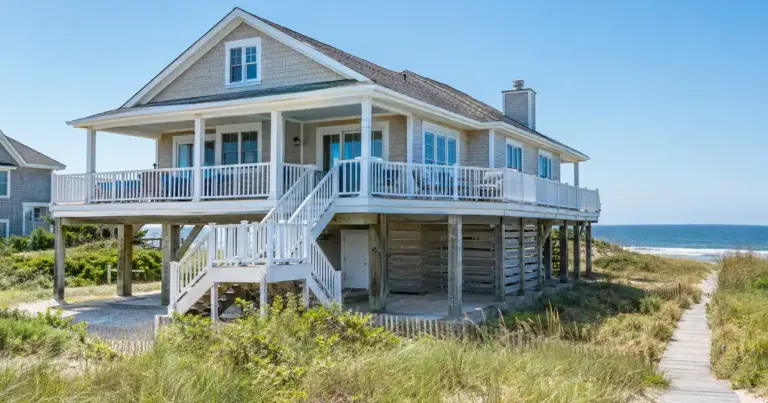
Brokerage accounts, retirement balances, and pledged-asset lines can all fund that cushion, but each comes with its own seasoning rules and discount math.
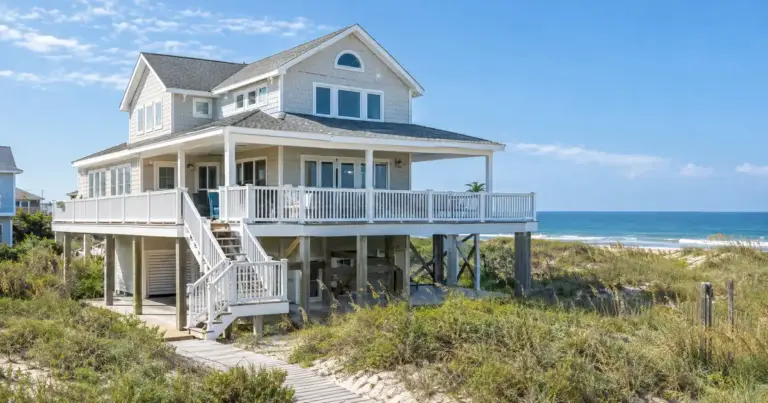
LLC-Held Short-term Rental Qualify for a DSCR Cash-out — Yes.
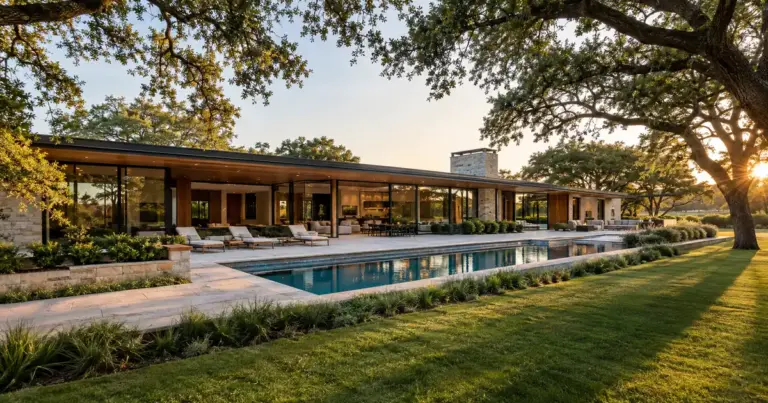
Confirm Rental Rules Before Closing A Resort — No single government body decides whether you can rent out a resort property short-term.
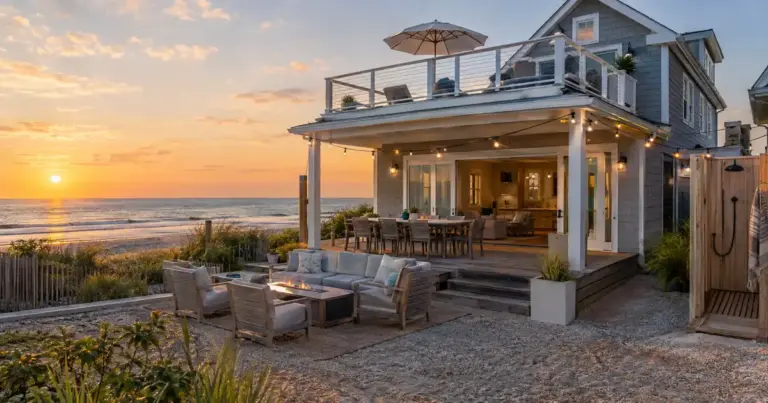
It wants twelve months of platform payout history or an appraiser’s short-term rent analysis, then discounts that gross number before running the ratio.
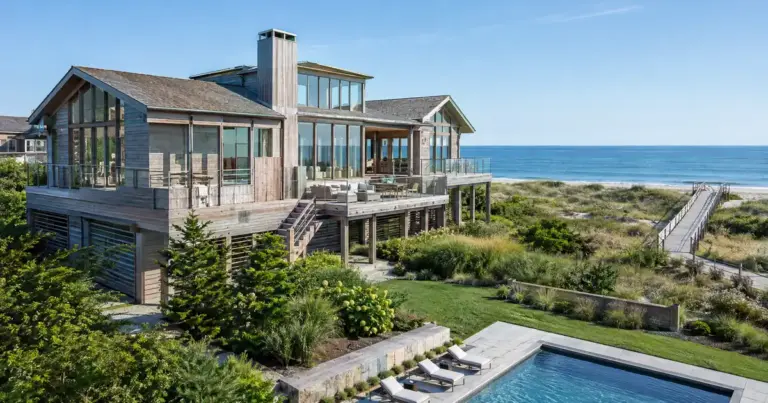
The loan qualifies on the property’s rent, not your personal tax returns, and jumbo DSCR programs can size well above agency conforming limits.
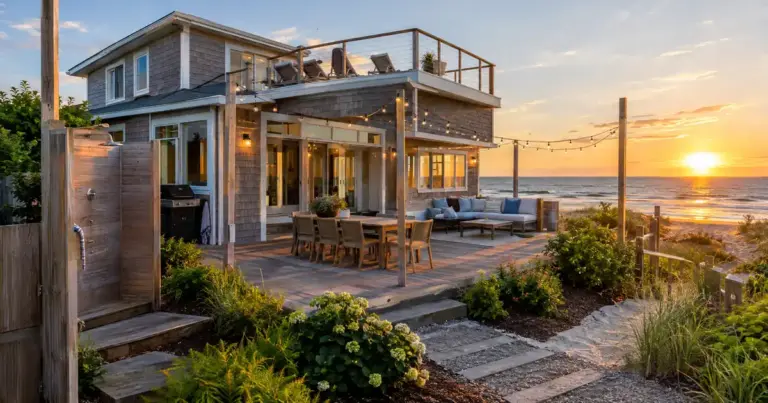
DSCR refinances are business-purpose loans reviewed differently from a standard owner-occupied mortgage.
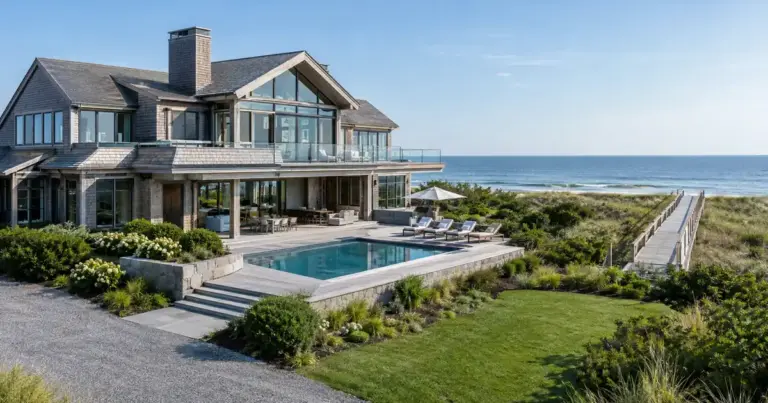
Does Higher Rent Raise Leverage On A Jumbo DSCR Refinance — No, not directly.
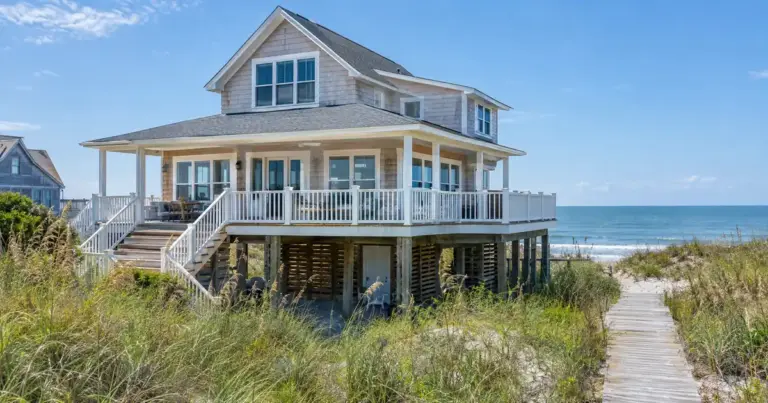
Founder Use a Second-home Loan on a Beach — No.
Your personal tax returns and business bank statements mostly stay out of it.
The real bottleneck isn’t income documentation — it’s sourcing and seasoning the windfall cash itself.
Does A DSCR Lender Use The Lease Or Market Rent For A Trust Rental — A trust changes who holds title, not how the rent gets calculated.