Blanket DSCR Loans In Alabama: How Multi-property Investors Qualify
Underwriting blends the income and debt across the whole group into one coverage ratio, so a soft property can be offset by a strong one.

Underwriting blends the income and debt across the whole group into one coverage ratio, so a soft property can be offset by a strong one.
The underwriter blends monthly rent against monthly payment obligations across the whole pool rather than testing each property alone.
Underwriting still appraises every property individually, then blends the income into one coverage test.
Sizes on this ladder run from $150,000 to $10,000,000, with leverage stepping down as the balance climbs.
Luxury Rental DSCR Loans In Bar Harbor — A seasonal luxury rental doesn’t fail underwriting because it’s empty in February.
Luxury Rental DSCR Loans In Portsmouth — A seasonal luxury rental doesn’t get financed on its best month.
Leverage steps down and credit floors step up as the loan size climbs, but the core math never changes: rent has to cover the payment.
For a luxury short-term rental, that discount and the comp set behind it are the whole ballgame.
The lender divides gross rent by the full monthly payment (principal, interest, taxes, insurance, and any dues) to get a coverage ratio.
For a short-term rental, the lender never just multiplies a nightly rate by thirty.
Lenders annualize the full year, discount projected revenue, and size reserves against the slow months — not the peak ones.
Luxury Rental DSCR Loans In Kennebunkport — The lender doesn’t care what your Airbnb screenshots say.
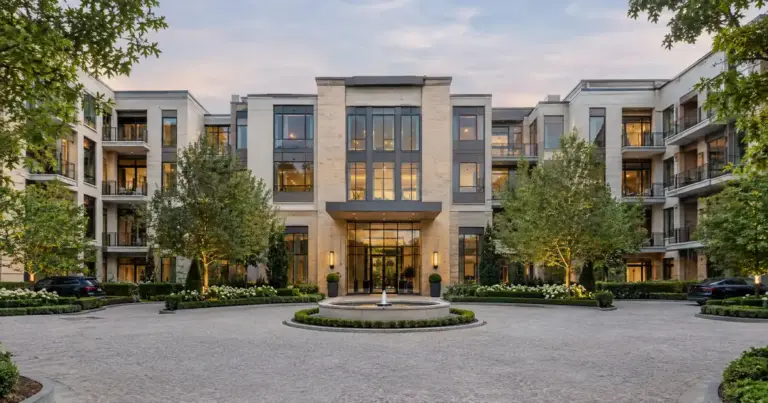
A DSCR loan is business-purpose financing for a rental property. It sits outside the conventional owner-occupied mortgage rulebook entirely.
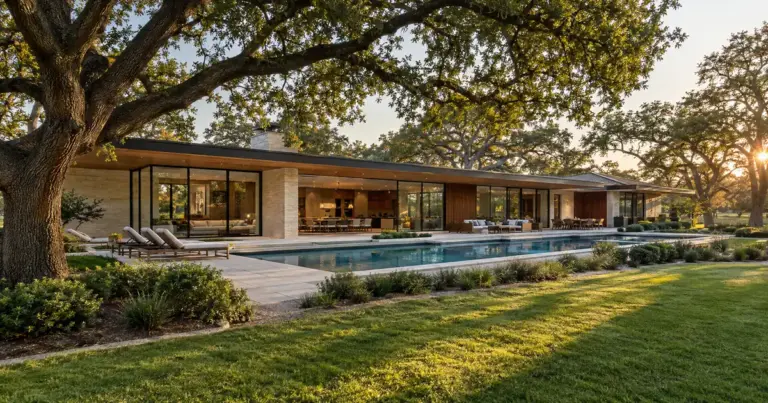
There is no federal line marking where “jumbo” becomes “super jumbo” — it is a lender-defined tier, and every wholesale program draws it differently.
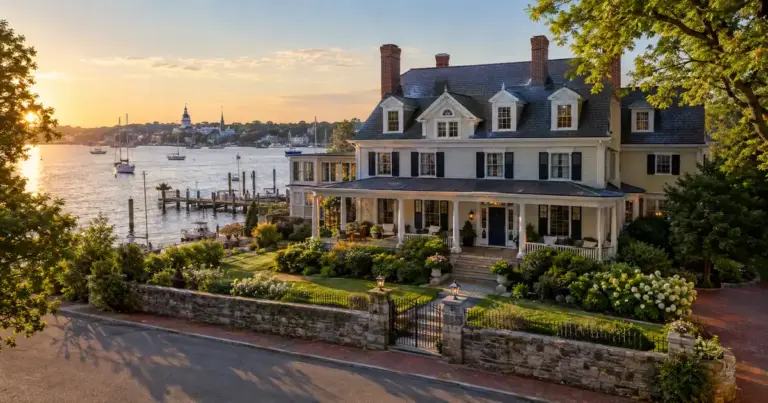
Luxury Rental DSCR Loans in Annapolis — A DSCR loan qualifies a rental property on the rent it produces, not the owner’s tax returns.