How To Finance A Luxury Short-term Rental Above The Jumbo Line
The real cliff isn’t the jumbo threshold.

The real cliff isn’t the jumbo threshold.
On a super jumbo file, that same math applies but the income path caps out at $2,000,000 in loan size, credit floors rise, and appraisal scrutiny doubles.
Above roughly $4 million, every file gets reviewed one at a time — no flat percentage applies. This isn’t a niche corner case anymore.
A short-term rental file doesn’t hit a wall at the jumbo line.
Reserves, entity structure, and leverage size then do the rest of the work.
The lender does not lower the reserve bar in slow months or raise it in peak season.
Get those three pieces right before you apply, and the loan structure — not your bank account — does the heavy lifting in January.
Get the entity paperwork and income documentation lined up before underwriting starts, and the file moves like any other business-purpose loan.
Get the sizing wrong and a good annual DSCR still leaves an owner scrambling every January.
Asset-based Borrowers Need Extra Reserves For A Seasonal Rental — Yes, typically.
Above that, larger investment properties move onto the standard DSCR ladder, which runs to $10,000,000 with tighter credit and reserve rules at the top.
Jumbo DSCR Loan Treat Short-term Rentals Differently — Yes.
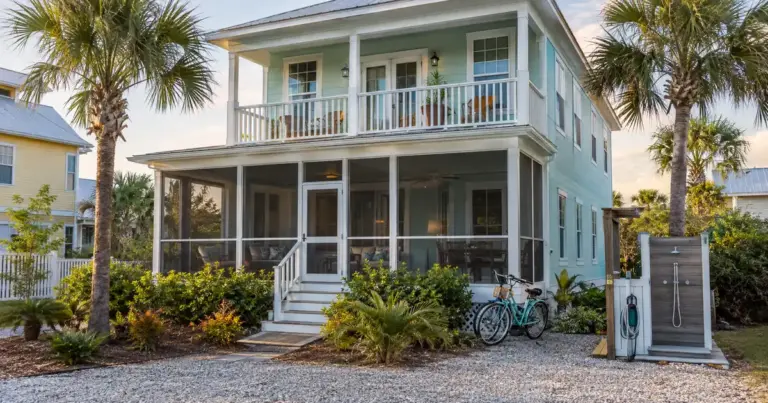
How Off-season Vacancy Sets Reserve Requirements On A Coastal DSCR Loan: what investors need to know about large-balance DSCR financing, from Lendmire.
Leverage steps down as the loan gets bigger, and the LLC shields property-level liability — not the loan itself.
A long-term lease qualifies on the lower of actual rent or appraised market rent.