DSCR Loan For Retired Real Estate Investors
DSCR Loan For Retired Real Estate Investors — Yes, retirees can get one.

DSCR Loan For Retired Real Estate Investors — Yes, retirees can get one.
No pay stubs, W-2s, or personal tax returns are the usual ask. You still document credit, funds, reserves, insurance, and the property.
DSCR Loan For High Debt-to-Income Borrowers — Yes, a high personal debt-to-income ratio usually does not block a DSCR loan.
Introduction A bankruptcy on your credit history feels like a full stop — a point where lenders close the door and investors have no choice but to wait …
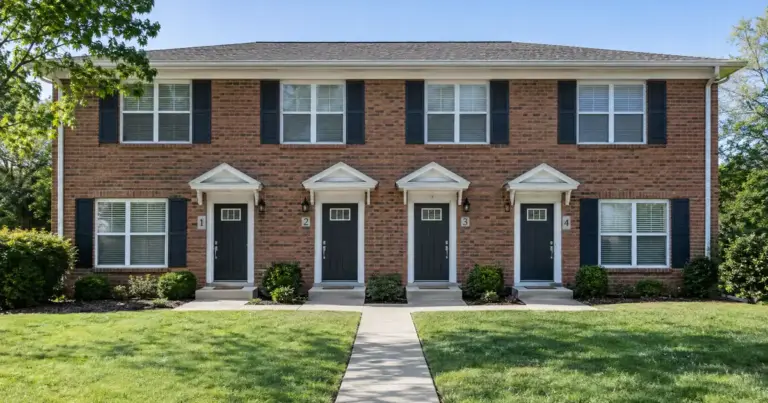
Every unit’s rent counts against one PITIA, so small multifamily often produces a stronger ratio than a comparable single-family rental.
DSCR Loan For Foreign Nationals Buying U.S. Rentals — Yes, a non-U.S. resident can finance a U.S. rental with a DSCR loan.
DSCR Loan For Out-Of-State Real Estate Investing — Yes, you can use one, and where you live is not part of the formula.
DSCR Loans For Investors With Multiple Properties — Yes, you can hold DSCR loans on many properties at once.
DSCR Loan For LLC-Owned Investment Properties — Yes, an LLC can borrow on a DSCR loan, and it is a common way to do it.
Introduction Real estate investors often ask whether a DSCR loan with no down payment is possible—and the answer depends on the property’s rental income and your lender’s guidelines. …
Conventional lenders qualify you. DSCR lenders qualify the property.
DSCR Loan For First-Time Rental Property Buyers — Yes, a first-time buyer can use a DSCR loan.
Your write-offs, tax-return net income, and employment history are not the test.