How To Qualify A Short-term Rental When The Lease Is Below Market
Here’s how each path actually works, and where investors get it wrong. Picture an investor under contract on a duplex.

Here’s how each path actually works, and where investors get it wrong. Picture an investor under contract on a duplex.
One is cash: how many months of PITIA — principal, interest, taxes, insurance, and any HOA dues — the borrower keeps liquid after closing.
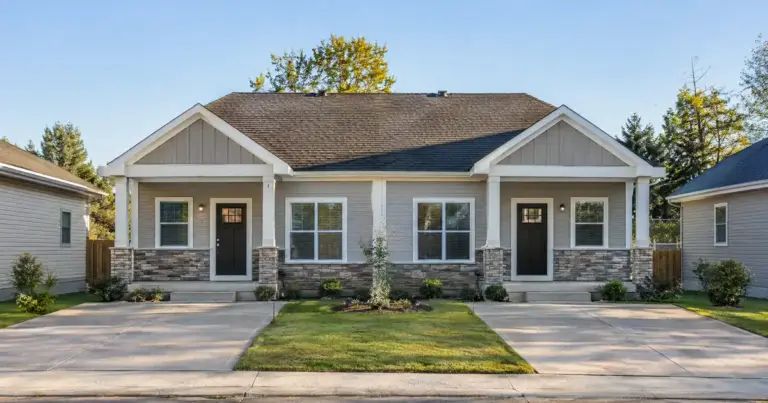
Does A Duplex Get The Same Leverage As A Single-family DSCR Loan — Mostly, yes.
– Above $2 million, two independent appraisals are typically required due to thin comparable data on unique luxury properties.
Get the entity paper clean before you apply, and a newly formed LLC closes like any other.
A strong July does not decide your loan. That single fact trips up more seasonal STR borrowers than any other underwriting quirk.
Because the loan is being used to acquire a rental, it’s classified as business-purpose credit rather than consumer credit.
Family Office Close A Luxury DSCR Loan — Yes.
The windfall itself doesn’t count as income on a DSCR file — it mostly matters as reserves and down payment, which still need a clean paper trail.
The entity paperwork rarely blocks approval — it drives whether the file closes on schedule or sits in conditions.
If a tenant pays below market, the file uses the lower lease figure, not the higher appraised number.
Condo Questionnaire Sets Eligibility On A DSCR Rental — The questionnaire is a form the building’s association fills out.
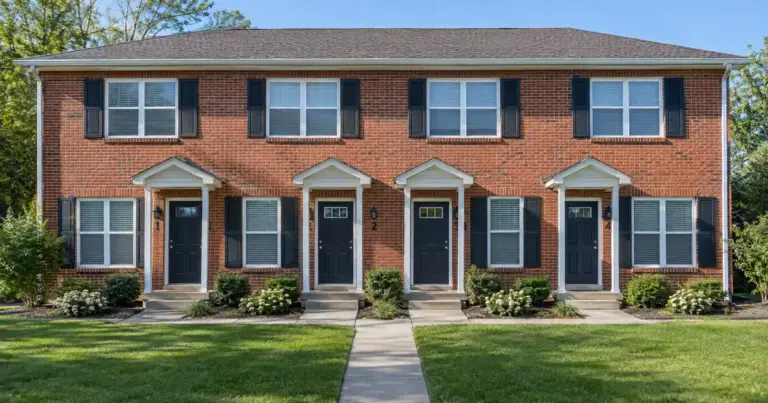
A fourplex has four units. That number matters more than it sounds like it should.
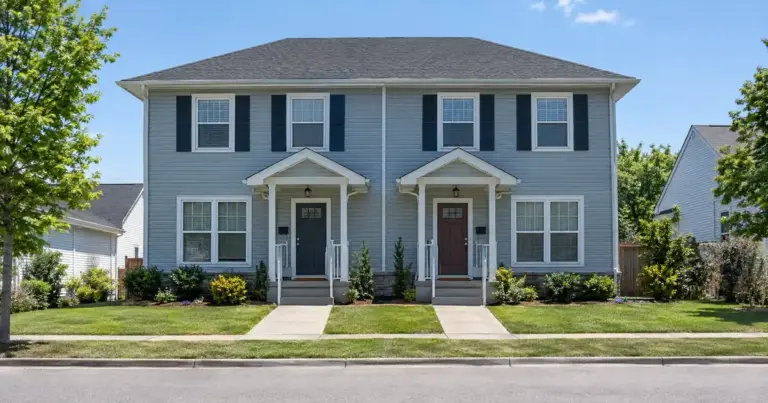
Does A Duplex Match Single-Family Leverage In A DSCR Portfolio Loan — Mostly, yes — up to a point, then no.
Can An IRA Satisfy Reserves On A Jumbo DSCR Rental Loan?