
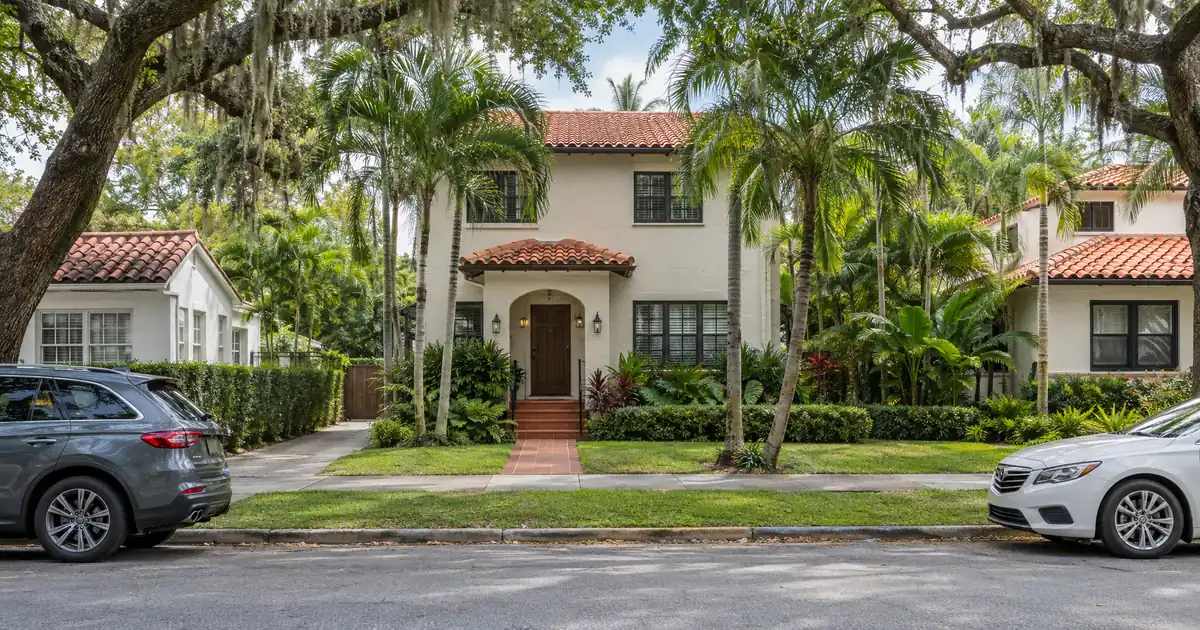
Picture two investors in Coral Gables. One owns a historic-core house in the Coral Gables Section, where Redfin shows a median near $1,499,276. The other owns a duplex a block from campus. Both want a DSCR cash out refinance. The duplex owner has a file. The house owner has a hobby. Rent on a single-family home at that price rarely covers a full-leverage obligation, and the whole city runs on that arithmetic.
TL;DR: A DSCR cash-out refinance in Coral Gables, Florida suits owners of small multifamily near the University of Miami, because the loan is underwritten primarily on the property’s rental income measured against its full monthly obligation, and a $1.7 million citywide median leaves most single-family rentals below the baseline.
DSCR Cash-Out Calculator
Run the cash-out numbers in Coral Gables, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out tops out at 75 percent LTV, with about six months of seasoning from title recording.
- Citywide prices are nearly flat year over year, per Redfin. Underwrite proceeds at today’s value.
- Duplexes near campus carry the coverage. Luxury single-family does not.
- Loans above $1,500,000 typically carry about nine months of reserves.
What the Cash-Out Box Looks Like Here
The program ceiling is 75 percent LTV on a cash-out, with minimum coverage of 1.00 and about six months of ownership measured from title recording. Credit tiers start at a 620 floor. Reserves run about six months of PITIA, stepping up to about nine months above $1,500,000. Standard programs go up to $3,000,000. All of this is guidance, and eligibility is subject to lender guidelines.
The reserve step-up matters more in Coral Gables than almost anywhere else. At a $1.7 million median, a lot of files cross the $1,500,000 line on their own. Nine months of PITIA in liquid reserves is real money to hold back. Investors planning a cash-out should count it before counting the proceeds.
Equity is not a cash figure until three inputs agree: rent used for lender review, full PITIA and the 75 percent cap. The proceeds are whatever is left after the tightest of those three. In this city, the tightest is almost always rent.
Qualification on these files is what DSCR qualification actually looks like in practice: rent used for lender review divided by principal, interest, taxes, insurance and any HOA dues. Owners weighing this against a bank refinance can read the comparison of the two approaches, and the steps involved are laid out in “The Refi Options”. Investors across the state can also start from the hub page for DSCR loans in Florida.
Don’t Count on Appreciation
Coral Gables is not handing out free equity. Redfin reports the median sale price up 2.2 percent year over year, and a separate Redfin page shows a median of $1,698,983, essentially flat. Zillow puts the average home value at $1,576,723, up 3.2 percent. Homes take 99 days to sell on Redfin’s count. Zillow shows about 72 days to pending. Redfin scores the market 12 out of 100 for competitiveness.
That is a negotiating market, not a bidding war. Price per square foot is up 15.3 percent on Redfin, but that mixes in changes in what sells.
Then there is the appraisal problem. Homes.com shows a March median of $1,485,000 against an average sale price of $2,146,153. Luxury closings drag the average up. A mid-priced rental does not borrow from them. Comps are thin and uneven, so a refinance appraisal can land flatter than the headlines suggest. The sensible approach is to model cash-out proceeds at today’s value and treat any appraisal upside as a bonus.
Investors who bought recently should expect the seasoning clock, not appreciation, to be the main thing that has changed. Six months from title recording gets the file eligible. It does not get it a higher value.
Where Coverage Holds: Duplexes Near UM
Small multifamily near the University of Miami and the Douglas Road Metrorail station is the only product that approaches the baseline at Coral Gables prices. The reason is demand. The City of Coral Gables names UM its largest employer.
A near-campus duplex listing shows two units of 2,100-plus square feet with four bedrooms each, bringing in $12,000 a month in total, both leased through the academic year, per Subdivisions.com. That is one listing with no price attached. Treat it as an anecdote, not a yield benchmark. It does show what a large unit near campus can command.
Run the numbers on modeled inputs, not sourced ones. Assume a duplex at about $900,000, near the low end of the $898,350-to-$4,295,000 range Homes.com shows, with two 2-bedroom units at about $4,000 each. RentCafe’s average 2-bedroom is $4,464 and Apartments.com’s is $3,737, so $4,000 sits inside the range. At 75 percent LTV, coverage lands around 1.3x including taxes and insurance, which clears the baseline with some room.
Now run the same structure at the median ask. Redfin shows 19 multifamily listings at a median list price of $1.89 million. Two units at about $4,400 each put coverage near 0.7 including taxes and insurance. Same city, same product, opposite answer.
The takeaway: price per unit decides everything. Underwrite each building on its own.
Sub-1.00 files exist. Select lenders may review reduced leverage, interest-only structures or stronger credit and reserves as compensating factors, but the file gets harder and eligibility depends on lender guidelines and property review. Owners who want to see where their building lands can talk to Lendmire before ordering an appraisal.
One caution on tenants. Student and shared-household leases follow the academic calendar. Underwrite turnover in summer, not just the lease on paper. And if the rent roll is one 12-month lease at a number the market has not yet tested, a lender will look at that too.
Central Gables and the West Side
Central Gables is the entry point. Redfin’s March figure is a median of $593,000, down 8.8 percent year over year, per its neighborhood page. Redfin does not give a property mix, so a good share of that is probably condos. Price-to-rent is the best in the city. The catch is HOA dues, which sit in the denominator of the coverage ratio and which building rules can push higher. Check the budget before assuming a condo cash-out works.
West Coral Gables, on the Westchester side, shows a median near $1.0 million, up 12.4 percent over the three months to October, per Redfin. That is the lowest-priced single-family area in the research, and it draws workforce and family renters. The data is dated, so treat the growth figure as a snapshot, not a trend. No reliable rent source exists for houses here. A 3-bedroom at the apartment-heavy $6,000-plus levels would not describe a modest house, so don’t borrow that number.
The Douglas corridor is the one to watch. Rent.com shows 1-bedroom averages near $2,100 in Douglas, among the lower-priced in the city. It is a small sample, and 1-bedroom data only. Still, pairing modest entry pricing with campus and Metrorail proximity is the right shape for a small-building cash-out.
Experience From the Desk
Working DSCR brokers see a recurring pattern in high-price, low-yield markets: the investor’s equity is real, but the rent supports only a slice of it. Files that clear tend to be small buildings bought below the local median, with leases in place before the appraisal is ordered. Files that stall are single-family rentals where the owner asks for the full 75 percent and the coverage lands well under 1.00. The fix is usually a lower balance or a different property in the portfolio, not a cleverer application.
Skip the Estate Enclaves (and Be Careful in the Section)
Cocoplum shows an average value of $6,878,787 on Zillow. Gables by the Sea sits near $4.3 million on Redfin. No rent covers that. Skip these for DSCR. They are owner-occupier assets.
The historic Section is the harder call. Its median is up 12.1 percent on Redfin, which makes the equity look generous. But owners there are sitting on a high-end single-family asset whose rent will not carry a 75 percent cash-out, and the Section is exactly where the appraisal premium is least reliable for a rental. Equity is not income. A lender looks at the second.
Broker-stated cap rates on multifamily listings, per Showcase, tell the same story: a Ponce de Leon Boulevard portfolio at $4,295,000 and a 2.46 percent cap, a $2,395,000 building at 5 percent and a $12,750,000 asset at 4 percent. These are asking-side figures. At 2.5 percent, no leverage structure produces a 1.00 coverage ratio. Only the 4-to-5 percent listings come close, and only with substantial equity.
New supply is a quiet risk at the top of the market. Florida YIMBY reported a site approved for an eight-story, 120-unit Class A building on Douglas Road. Luxury apartments can cap rent growth for older product at the high end. RentCafe shows rent growth of just 1.32 percent, and Apartments.com showed 0.4 percent, so the rent side is not covering for the price side.
The Demand Base Behind the Rent Roll
A tenant base tied to institutions is easier to underwrite than one tied to tourism. Beyond UM, Baptist Health South Florida is headquartered in Coral Gables, and the city page lists banking, investment, health care and professional services, plus the international headquarters of Bacardi and Del Monte Fresh Produce. Renters in households earning well above the median matter here: Data USA shows a median household income of $130,803. Only 36 percent of households rent, per RentCafe, so the rental pool is smaller than in most Florida cities.
Population is flat to slightly down, from 49,696 to 49,243 in the Data USA series. Demand is steady, not growing. For a cash-out, that suits the conservative approach: stable leases, no assumed lift.
Where the Proceeds Go
The usual use is the next down payment, and the rule here is the same as in the rest of the file: size it to rent, not to hope. Owners pulling equity from a coverage-strong duplex often do better putting it into another sub-$1 million small building than into a house in the Section. LLC vesting is available, subject to lender program eligibility. Lendmire’s overview of investment property refinance options covers this in more depth. Investors should verify current local rental rules, taxes and insurance with qualified local professionals before committing.
For a direct conversation, reach the team at 828-256-2183.
Frequently Asked Questions
Can a house in the Coral Gables Section qualify for a DSCR cash-out?
It can be reviewed, but expect a lower balance than the 75 percent ceiling implies. Rent on a single-family home at a median near $1.5 million rarely covers full PITIA at high leverage. Reduced leverage, stronger credit and larger reserves may reshape the file, subject to lender guidelines.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Coral Gables, FL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
How long must I own a duplex near UM before pulling cash out?
About six months, measured from title recording. The clock starts at recording, not at contract. Appreciation is not required, and with prices nearly flat it should not be assumed.
Will an appraisal capture the luxury sales that lift the city average?
Usually not for a mid-priced rental. Homes.com shows a median of $1,485,000 against an average of $2,146,153, which means high-end closings skew the average. Appraisers lean on closer comps, so model proceeds at flat value.
Do academic-year leases hurt a student-area rent roll?
They add turnover risk, not disqualification. A lender reviews the lease schedule and the rent against full PITIA. Documented leases in place before the appraisal strengthen the file.
How much do reserves matter on Coral Gables loan sizes?
A great deal. Reserves run about six months of PITIA, and about nine months above $1,500,000, which many Coral Gables balances will cross. Plan for liquid funds on top of the equity you are pulling.
Where the Mispricing Sits
The asymmetric opportunity is the sub-$1 million duplex or small building near the Douglas Road Metrorail station and UM. It is priced far below the $1.89 million multifamily median, it draws from a student and staff base of tens of thousands, and it is the one product in the city where the rent roll can stand up to a 75 percent cash-out.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a DSCR and non-QM mortgage broker, Lendmire (NMLS# 2371349) connects investors with wholesale lending channels across 41 markets, including Washington, D.C. The property’s rental income, not the borrower’s traditional personal-income documentation, is central to program review, which works for self-employed operators and portfolios beyond four financed properties. Lendmire is recognized as a top-ranked workplace in 2026 and a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin
2. Redfin, Coral Gables housing market
3. Zillow, Coral Gables home values
4. Homes.com, Coral Gables multifamily
6. City of Coral Gables, A Dynamic Destination
8. Redfin
9. Redfin — Central Gables Housing Market
10. per Redfin
11. Zillow
12. Showcase
13. Florida YIMBY
14. Baptist Health South Florida
16. RentCafe
17. Scotsman Guide — Top Workplaces 2026
18. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Coral Gables, Florida: What Qualifying Takes on $3,000 Rent · DSCR Cash Out Refinance in Coral Springs, Florida · Luxury Rental DSCR Loans In Coral Gables: Seasonality And Coverage
Guides: Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.