
The Quick Read: The loan amount is the smallest of three limits: the leverage cap on appraised value, the payment the rent used for lender review can support, and the program’s loan-size range. On most files the rent test binds before the leverage cap does, especially on condos and townhomes with HOA dues in the payment.
- Purchase leverage typically runs 75%-80% LTV on an investment property, subject to lender guidelines.
- Cash-out refinances top out around 75% LTV across most of the network.
- Coverage of 1.00 is where select programs start; stronger ratios open better terms.
- Credit tiers start at 620, with most programs wanting around 660 and 700+ for the strongest tiers.
- Reserves are commonly about 6 months of PITIA, stepping up to about 9 months above $1,500,000.
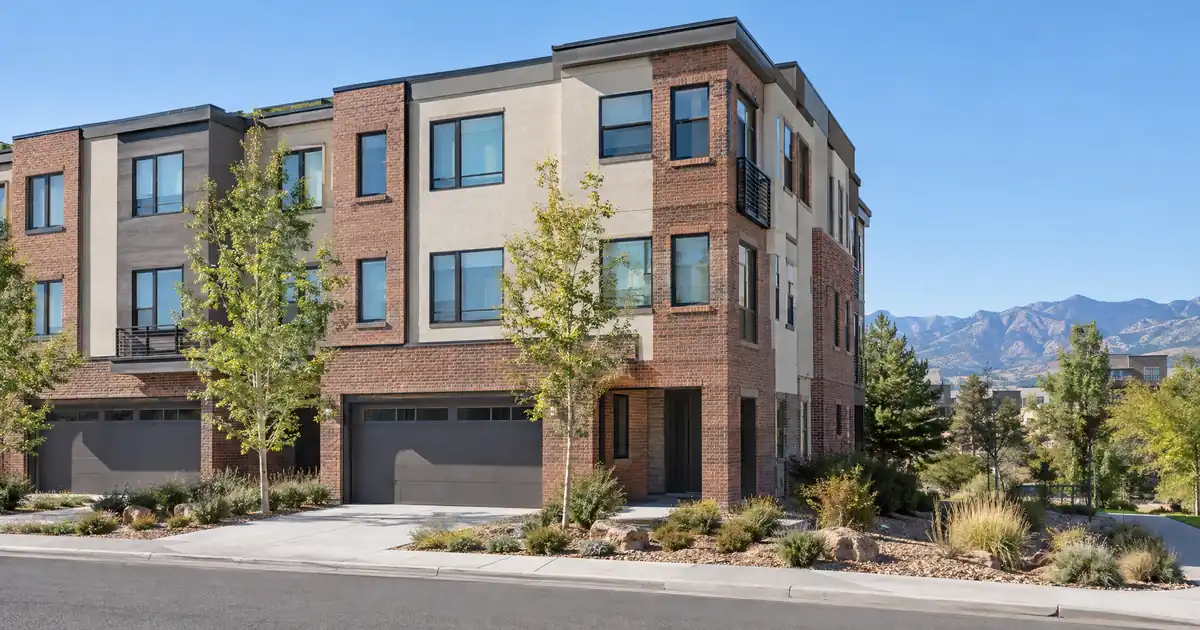
Denver Tech Center (DTC) is a good worked example because the typical small-investor product there is a condo or townhome with HOA dues. This article is national in scope. DTC is used only to show how the mechanics play out.
DSCR Calculator
Run the numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 29, 2026
Prefilled with starting assumptions — enter your own rent or nightly figures, taxes, insurance, and HOA for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 29, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Rent, nightly rate, occupancy, taxes, and insurance are editable estimates. Short-term rental figures are estimates only and vary significantly by season, property type, management approach, and local short-term-rental rules — confirm local regulations before relying on them. Qualifying income for short-term rentals varies by program — some use appraisal market rent, others use documented STR history or projections — and is confirmed in underwriting. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
What Is a DSCR Lender Actually Testing?
A DSCR lender tests whether the property’s rent covers its monthly obligation. The ratio is monthly rent divided by PITIA: principal, interest, taxes, insurance, and any HOA dues. The loan is reviewed primarily on property-level rental income covering the payment, subject to lender guidelines, credit approval, and property review.
The ratio is not your cash flow. Repairs, vacancy, management, utilities, and capex sit outside it. A file can clear 1.00 and still lose money in a soft market. Treat the number as a lender’s test, not a profit forecast.
DSCR loans are designed for non-owner-occupied investment properties. Because they are business-purpose loans, they are reviewed differently from a standard owner-occupied mortgage. For the full framework, see Lendmire’s complete DSCR loans guide.
The Three Ceilings on Loan Size
The loan is the lowest of three numbers. Most investors only look at the first one.
| Ceiling | What sets it | When it binds |
|---|---|---|
| Leverage cap | LTV % × appraised value | Strong rent, modest HOA |
| Coverage limit | Rent ÷ coverage floor = max payment | High HOA, taxes, or insurance |
| Loan-size range | Program minimum and maximum | Very small or very large balances |
The coverage limit is the one that surprises people. Work backward: the rent divided by the coverage floor gives the largest monthly obligation the file can carry. Taxes, insurance, and HOA dues take their share of that obligation first. Whatever is left funds principal and interest, and that sets the loan size, however generous the LTV.
This is why two properties at the same price can support different loans. A no-HOA house leaves more room for principal and interest than a condo with heavy dues.
How a Denver Tech Center Rental Profiles Out
DTC is a submarket, not a jurisdiction. It straddles Denver and Greenwood Village, so tax treatment and HOA structure can differ from one block to the next. Taxes and HOA dues both sit inside PITIA, and both depend on the exact address. Pull them for the specific property before you estimate a loan.
The typical small-investor product there is a condo or townhome in a managed community. That has two file consequences:
- HOA dues sit in the denominator. Higher dues reduce coverage and shrink the loan, even if the price and rent look attractive.
- The condo project must be eligible. Lenders review the HOA questionnaire, budget, reserves, and litigation. Condo certification gaps are a common reason files stall.
Tenant demand in an employment corridor tends to lean on professionals and relocations. For underwriting, though, what matters is documented lease terms and appraisal rent, not the tenant profile.
Which Rent Counts: Lease or Market?
The convention among practitioners is the lower of the in-place lease and the appraiser’s market rent, with program details set by each lender. An above-market lease adds nothing. A below-market lease pulls coverage down. TrueCap’s investment-property explainer illustrates it: a lease and a lower market rent produce a lender ratio of 1.17 against 1.26 on the lease alone.
Market rent comes from the appraisal. The rent schedule borrowed for DSCR files is the Fannie Mae Form 1007, which lets a lender get market rent for a single-family investment property from the appraiser. DSCR loans are not agency products. The form is used only as a documentation convention. It uses a subject plus three comparables and asks for comments on vacancy and rent trends. Its instructions also say concessions should be adjusted to the market, not to the subject. For two-to-four unit properties, appraisers use a different form that estimates rent per unit.
On a vacant or month-to-month unit, the market rent stands alone. Comp quality then decides the outcome. Appraisal reconsideration is a routine step when comps come in light, so a documented packet of recent nearby leases is worth having ready.
Why Denver’s Concessions Matter to Loan Size
Concessions pull supported rent below asking rent, and lower rent used for lender review means a lower loan or more equity. Denver is a live example.
The Colorado Sun reported metro apartment vacancy at 7.6%, the highest in 16 years, with Arapahoe and Denver counties both at 8.2%. The Real Deal reported average rent down 4.8% to $1,754, with concessions averaging 9.5% of gross rent. This is apartment data. Little of it speaks to condos or townhomes, so do not read it as a DTC average.
The practical point: an appraiser adjusting comps for concessions can land below asking rents. Underwrite on a rent you can document, not on a listing. Single-family rentals have shown tighter vacancy and lighter concessions than apartments, per local property-management commentary, but treat that as directional only.
Worked Example: Same Price, Two Different Loans
Run the logic with ratios, not dollars. Picture an investor buying a condo at 75% LTV on a purchase. The rent is documented and the appraisal supports it. Coverage lands around 1.15x. The leverage cap is the binding limit, and the full 75% loan works. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Now change one input. Say the HOA dues are materially higher and the appraised market rent comes in a notch under asking. Coverage at the same loan slips to roughly 0.95x. Now the coverage limit binds first.
The options a lender would review:
1. Bring more down payment. A larger down payment lowers the monthly obligation and can lift the ratio. It never erases credit floors, reserve rules, or property eligibility.
2. Use a different structure. Extended terms (40-year) and interest-only periods are available through select lenders in the network. Those change the payment profile.
3. Look at sub-1.00 programs. Coverage below 1.00 is available through select lenders in the network, with leverage and terms adjusted.
4. Change the property. A no-HOA townhome or small multifamily may carry more cushion.
None of these is a promise. Qualification stays subject to lender guidelines, credit approval, and property review.
Where the General Rule Breaks
Short-term rental income in Denver. Under Denver’s short-term rental rules, a short-term rental must be the host’s primary residence. The city’s FAQ adds that a non-primary-residence property is not eligible for a license. A non-owner-occupied condo on the Denver side should be underwritten on long-term rent. Nightly rate × 30 is not market rent, and the rent schedule cannot estimate a nightly fee. Short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income. That includes the Greenwood Village side.
For reference, where short-term income is allowed, network programs run about 75% LTV on purchases and about 70% on refinances and cash-out, with a 640+ score and roughly 12 months of hosting history. Purchase and refinance each carry a 1.00 coverage floor. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Ineligible property types. Manufactured homes (single- and double-wide), log homes, and barndominiums are not offered in the network’s DSCR programs.
Large balances. Loan sizes run up to $3,000,000 on standard programs. Above $2,500,000 the network generally holds to 30-year fixed structures, and reserves step up to about 9 months above $1,500,000.
Cash-out. Cash-out tops out around 75% LTV on a standard rental, with about 6 months of seasoning the common expectation. Seasoning is documented by the settlement statement, and files that assume it away get kicked back. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
DSCR vs. conventional financing
There are two common ways to finance an investment property, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What Documents Keep the File Clean
DSCR needs no personal income documentation, but the file is not light. The friction points are predictable:
- Entity documents if buying in an LLC, subject to lender program eligibility.
- Lease evidence or, on vacant units, a clear path to the appraiser’s rent schedule.
- HOA questionnaire, budget, and condo certification for condos.
- Insurance quote that is complete and current.
- Reserves documentation, commonly about 6 months of PITIA, varying by lender, leverage, loan size, and transaction type.
- Title and settlement information for refinance files.
Credit sets the leverage tier. A 620 floor exists in parts of the network, most programs want around 660, and 700+ unlocks the strongest tiers. Select high-leverage purchase programs reach 85% LTV with roughly a 700+ score.
Key Terms Defined
PITIA: Principal, interest, taxes, insurance, and HOA dues, the monthly obligation the rent must cover.
DSCR: Debt service coverage ratio, rent used for lender review divided by PITIA.
LTV: Loan amount as a percentage of appraised value.
Market rent: The rent an appraiser supports using comparable leases, not the asking price.
Seasoning: The ownership period a lender requires before cash-out is available.
Condo certification: The lender’s review of the condo project’s HOA documents, budget, and litigation.
What the Decision Looks Like in Practice
Start with the rent you can document, then price the carrying costs for the exact address. If coverage clears with room, the leverage cap sets the loan. If it doesn’t, expect to bring more equity or adjust the structure. For related reading, Lendmire’s piece How Much a DSCR Lender Lends on a $1.5M Rental in Los Angeles walks a larger-balance case.
Tax treatment can depend on how the funds are used and how the property is held; investors should keep clear records and speak with a qualified tax professional before relying on any deduction.
If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire, a DSCR-focused mortgage broker arranging investor loans across 41 markets including Washington, D.C., can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals. Call 828-256-2183 or request a quote.
Frequently Asked Questions
Is the maximum LTV the loan I will get?
No. LTV is only one limit. Coverage often binds first, especially with HOA dues, and the program’s loan-size range applies too. The smallest of the three sets the loan.
Does a larger down payment fix weak coverage?
It can help. It does not erase credit floors, reserve rules, or property eligibility, so the file still has to clear both the equity test and the coverage test.
Can I count Airbnb income on a Denver Tech Center condo?
Not on the Denver side if you do not live there. The city requires a short-term rental to be the host’s primary residence. Underwrite on long-term rent and confirm local and HOA rules before relying on any projected income.
What if my lease is above market rent?
The premium usually does not count. The convention is the lower of the lease and the appraiser’s market rent, though each program sets its own treatment.
Can coverage fall below 1.00?
Yes, through select lenders in the network, with leverage and terms adjusted. Expect lower leverage than a file that clears 1.00, and approval remains subject to lender guidelines.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C., through wholesale and investor-lending channels. DSCR loans are evaluated by the lender on rental income rather than personal income, subject to lender guidelines — a fit for LLC-owned portfolios, self-employed investors, and operators scaling beyond conventional loan caps. Recognized as a Scotsman Guide Top Mortgage Workplace in 2025 and 2026.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. TrueCap, investment property appraisal
2. Fannie Mae Form 1007, Single-Family Comparable Rent Schedule
3. The Colorado Sun, metro Denver apartment vacancy
4. The Real Deal, Denver apartment vacancy
5. FAQ
This article is part of Lendmire’s DSCR loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How Much a DSCR Cash-Out Refinance Lends on a Freshly Bought Rental · How Much a DSCR Lender Lends on a Rental After Storm Repairs · How Much a DSCR Lender Funds as You Scale a Rental Portfolio
Guides: DSCR Loans in Denver, CO · DSCR Loans in Colorado
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.