
The Quick Read: A VA loan can finance a four-unit building with no down payment, as long as you live in one unit and the price does not exceed the appraised value. The other three units can help you qualify, but only when the file meets extra conditions on reserves and landlord experience. “No money down” does not mean “no cash needed.” The funding fee, closing costs, and reserves are the real cash items, and the appraisal sets the ceiling on the loan.
Key Takeaways
- The loan is owner-occupied. You certify that you will live in one unit, and move-in is generally expected within 60 days of closing.
- Full entitlement carries no VA loan limit. Leverage is 100% with no mortgage insurance, provided the price is not above the appraised value.
- Rent from the other units counts toward qualifying only in a discounted form, and only with your own cash reserves and landlord documentation behind it.
- The funding fee, closing costs, and reserves are the cash items that catch buyers off guard.
- Residual income is the controlling test, not the debt-to-income figure alone.
What Does It Mean to House Hack a Fourplex With a VA Loan?
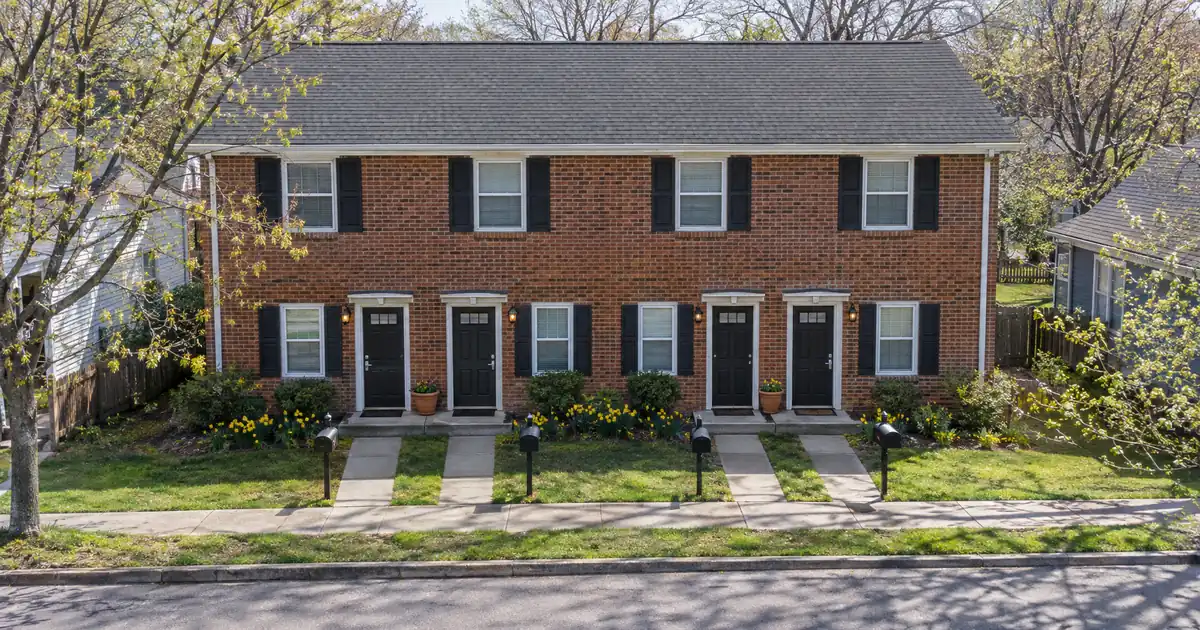
House hacking means you buy a small multi-unit building, live in one unit, and let tenants in the others help carry the housing cost. With a fourplex, three units are rentable. A VA loan fits this because it allows 100% financing with no mortgage insurance of any kind.
VA payment estimate
Starting assumptions reflect an example price with no down payment and a first-use funding fee. Replace them with your own figures.
Editable benchmark: 7.32% as of October 22, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not a VA loan quote.
Illustrative starting assumptions: a $350,000 price, no down payment with full entitlement, a first-use funding fee financed into the loan, a thirty-year term at the current Freddie Mac benchmark, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conventional benchmark, a market reference and not a VA loan quote; your rate is set by the lender at lock. The funding fee follows VA’s published table for the use and down payment entered; the residual-income figure is VA’s guideline for the region and family size, and the rough residual shown subtracts only the housing payment and the debts entered, while VA also deducts taxes, maintenance and utilities. Taxes, insurance and dues are editable estimates; closing costs are not included. Licensed in sixteen states for consumer mortgages. Lendmire is not affiliated with or acting on behalf of the Department of Veterans Affairs.
It is an owner-occupied purchase. It is not an investment loan. The occupancy certification at closing is what separates the two, and it is a legal statement of intent. If you want a building to hold purely as a rental, this is the wrong program. Occupancy decides the leverage, and that is all this article will say about the investor side.
Lendmire’s VA loan programs are arranged through wholesale lenders, and the mechanics below reflect what comes up on these files across that network. Every figure is subject to lender guidelines and full file review. Nothing here is a commitment to lend.
Fourplex, Duplex, Triplex, or a Room Rental: Which Fits?
A fourplex gives you the most rentable units under one VA loan. A duplex or triplex gives you less rent but a smaller building and usually a lower price. Renting rooms in a single-family house is a different category of income and is not the fourplex path.
| Option | Units you rent | Rent offsets | Trade-off |
|---|---|---|---|
| Duplex | 1 | Smallest share | Easiest to manage |
| Triplex | 2 | Middle share | More systems to maintain |
| Fourplex | 3 | Largest share | Most upkeep and vacancy exposure |
| Room rental | Rooms only | Varies | Shared living space |
A fourplex is not automatically the better deal. More units mean more roofs, meters, and turnover. Whether the extra rent beats the extra work depends on the price and the condition of the building.
What Do You Need to Qualify?
You need a Certificate of Eligibility (COE), a decision score the wholesale lender will accept, and income and residual income that fit the loan. VA sets no minimum credit score. The wholesale programs Lendmire places VA loans with start at a 580 decision score, and lenders may set a higher floor.
The COE comes from VA and decides your eligibility. Service requirements are VA’s rules, not the lender’s.
Residual income is the controlling test. That is the money left each month after taxes, debts, and housing costs, compared against a VA table. The 41% debt-to-income figure is a guideline, not a cap. A ratio above it can still work when residual income sits well above the table. A ratio below it will not save a file with thin residual income.
Which Properties Qualify?
The building must be a residential property of up to four units, and it must meet VA’s minimum property standards at appraisal. A fourplex fits that range. The VA’s underwriting chapter refers to a multi-unit property securing the loan in which the Veteran occupies one unit, as set out in VA’s credit underwriting guidance.
Condition matters more on a fourplex than on a single-family home. Failing roofs, unsafe wiring, or broken heating in one unit can stall the whole file. Older buildings are where this shows up most. Get a private inspection before the VA appraisal, not after.
How Does the Occupancy Rule Work?
You must certify that you will occupy one unit as your home. Under the VA Lenders Handbook, Chapter 3, a “reasonable time” to move in generally means within 60 days after closing.
A later date can be reasonable only if two things are true. You certify a specific future date, and a particular event makes occupancy possible on that date. Occupancy more than 12 months after closing generally cannot be considered reasonable. The same chapter says deployed service members are in temporary duty status and can meet the occupancy requirement.
Plan the closing date around orders, deployment, and lease end dates on the building. If the current tenant in your intended unit has a lease, that is a timing problem to solve before you write the offer.
The handbook does not set a minimum stay. That does not make the certification casual. You are stating real intent at closing. Moving out later for a job or a new duty station is a normal life event. Buying with the plan to never live there is not.
What Does “No Money Down” Actually Cover?
It covers the down payment and nothing else. The loan is 100% financing, with no mortgage insurance, as long as the price is not above the appraised value. You still need cash for several items.
| Cash item | What it is | Can it be financed? |
|---|---|---|
| Funding fee | One-time VA fee | Yes |
| Closing costs | Title, settlement, and related items | Generally no on a purchase |
| Inspection and appraisal | Due diligence before closing | No |
| Reserves | Your own funds, if rent is used | Not applicable |
| Earnest money | Deposit with the offer | Not applicable |
The funding fee. For first use with less than five percent down, the fee is 2.15%. With five to under ten percent down it is 1.5%, and with ten percent or more it is 1.25%. For subsequent use with less than five percent down it is 3.3%, with the same 1.5% and 1.25% tiers above that. Veterans receiving compensation for a service-connected disability are exempt, along with the other exempt groups. VA’s funding fee page explains that the fee applies to the loan amount, not the purchase price. It can be paid in cash or included in the loan. Financing it raises the loan balance.
Seller help. Closing costs and certain concessions can sometimes be negotiated with the seller, within VA’s limits. Whether that is realistic depends on the deal and the market.
How Does Rental Income Help You Qualify?
Rent from the other units can count as income, but only a discounted share of it, and only when conditions are met. This is where fourplex files differ most from single-family VA files.
Under VA’s underwriting chapter, Chapter 4 of the Lenders Handbook, prospective rental income is included only if:
1. You have a reasonable likelihood of success as a landlord, shown by documented experience managing rental units or by use of a property management company.
2. You hold cash reserves of at least six months of the mortgage payment (principal, interest, taxes, insurance), verified by the lender.
3. The local market supports continued rental success.
If each unit is separate and not under one mortgage, six months of reserves must be verified for each separate unit. The lender also writes a justification on VA Form 26-6393, the Loan Analysis.
The discount exists because rent is not guaranteed. It reflects vacancy and maintenance. Treat the counted amount as smaller than the rent you collect. Your own reserves, repairs, and vacancy are not covered by it.
If you do not use the rent, the lender counts the full mortgage payment as a debt, and the reserve requirement does not apply. That path may fit a buyer who has strong income but little cash. It also means you qualify on your income alone. Terms depend on the lender’s guidelines, the property type, the leverage, and a full review of the credit profile.
Reserves are the item that most often surprises buyers. They need to be your own funds. Documented reserves belong in the file before it goes to the lender, not after. A buyer who plans on rent income and then learns of the reserve test during review loses time, and sometimes the contract.
What Does the VA Appraisal Do?
The VA appraiser sets the reasonable value, which appears on the Notice of Value. The loan is tied to that value. Per Chapter 3 of the handbook, VA specifies no maximum loan amount, but the maximum depends on reasonable value and the lender’s secondary-market needs. The exact numbers vary by lender and program and follow a full review of property, leverage, and credit.
If the appraisal comes in below the price, you have limited choices. You can renegotiate the price, bring cash to cover the gap, or walk away. No down payment is required only when the price does not exceed the appraised value. On a fourplex, a low appraisal can also trace back to a weak rent estimate, so rent comps in the file help.
Ask for an appraisal reconsideration when you have recent sales or condition facts the appraiser missed. A reconsideration packet works best with specific, comparable sales, not opinions.
Where Does the General Rule Break?
Several edge cases change the answer. These are the ones that come up most.
- Partial entitlement. If a prior VA loan still uses part of your entitlement, a down payment may be required. Speak with a loan officer for your numbers. Full entitlement has no VA loan limit, though the lender, appraisal, and income still limit the amount.
- Appraisal below price. The loan follows the appraised value, not the contract price.
- Delayed occupancy. The two-part test and 12-month outer limit apply.
- Departing residence. If you are moving out of a current home and renting it, that income follows different reserve rules than the fourplex. Reserves are not needed to offset the payment on the home you occupied before the new loan, per VA’s underwriting chapter. The fourplex units still need the six-month reserve test.
- Extra lender conditions. A given lender may add its own requirements on three- and four-unit files. Do not assume a test is VA’s rule just because a lender asks for it.
- Unit count and use. Stick to a building that is legally four residential units. Mixed-use buildings raise questions best settled with a loan officer before an offer.
Building the Full Picture: Qualifying View vs. Cash-Flow View
Two views matter, and they are not the same. The qualifying view is what the lender counts. The cash-flow view is what you actually keep.
The qualifying view uses a discounted share of rent against the payment, with your income and residual income as the controlling test. The cash-flow view has to include everything the lender’s number does not: vacancy, repairs, capital items like roofs and boilers, management, utilities you pay, and landlord insurance.
A fourplex can qualify and still run tight. Run both views before you make an offer. If the building only works when every unit is full and nothing breaks, it does not work. A reasonable go/no-go test is whether you could carry the building through one empty unit and one repair without borrowing.
“Living for free” means rent covers the full housing payment. In expensive areas, rent may cover only part of it. That is still a good outcome compared with renting.
How Do You Vet a Fourplex and Make the Offer?
Inspect each unit, not just the one you will live in. Look at roofs, plumbing, electrical, heating, and how utilities are metered. Separate meters shift cost to tenants. Shared meters put it on you.
On a tenant-occupied building, ask for the leases and a rent roll before you commit. Existing leases carry over. Below-market rents may be locked in for months. Ask which unit will be vacant at closing, since you must move into one. An unoccupied unit at closing saves a timing problem.
Confirm local zoning and rental rules before you shop. Pick a lender who has done multi-unit VA files before. Then request a pre-approval that states whether rent income is being used.
What Does the Process Look Like?
Here is the sequence from start to close.
1. Pull your COE. It shows your entitlement and any funding fee exemption.
2. Choose your qualifying path. Decide whether rent will count, and gather reserve and landlord documentation if so.
3. Get pre-approved. The lender reviews income, debts, and residual income.
4. Write the offer with an occupancy plan. Tie the closing date to your move-in date.
5. Inspect, then appraise. The VA appraiser sets reasonable value, and the building must meet VA’s property standards.
6. Review the Loan Estimate and Closing Disclosure. The lender must give you the Closing Disclosure at least three business days before closing, as the CFPB explains. Compare it against your earlier Loan Estimate.
7. Close and move in. Occupancy is certified at closing.
What Goes Wrong Most Often?
- Buying as a pure investment. VA is owner-occupied. The certification is real.
- Assuming all rent counts. Only a discounted share does, and only with reserves and landlord documentation.
- Skipping reserves. Six months of payments in your own funds is a real cash need.
- Ignoring the cash-flow view. A file that qualifies can still fail in practice.
- Treating gift funds or equity as reserves. Reserves are your own funds, and a lender will confirm the source.
- Skipping the inspection. An older fourplex can hide deferred repairs across all four units.
- Not planning the exit. Decide ahead whether you will hold the building after you move out, sell it, or repeat the strategy.
Who Is This Strategy Right For?
It suits a veteran or service member who can live next to tenants and handle landlord duties, or hire someone to. It suits a buyer with some cash set aside beyond the funding fee and closing costs. It does not suit a buyer who needs every unit full to pay the bills, or one who wants no landlord role at all.
After the first stretch of living in the building, you may keep it as a rental and buy another home.
Key Terms Defined
Entitlement: The amount of VA guaranty available to you, shown on your Certificate of Eligibility.
Funding fee: A one-time VA charge that stands in for mortgage insurance and can be financed.
Residual income: The money left each month after taxes, debts, and housing costs, tested against a VA table.
Reasonable value: The appraised value on the Notice of Value, which caps the loan.
Reserves: Your own cash held after closing, measured in months of mortgage payments.
PITI: Principal, interest, taxes, and insurance, the full monthly housing payment.
Frequently Asked Questions
Can I really buy a fourplex with a VA loan and put nothing down?
Yes, with full entitlement, as long as the price is not above the appraised value and you will live in one unit. You still need cash for the funding fee (unless exempt), closing costs, inspection, and reserves when rent is used. With remaining entitlement from a prior VA loan, a down payment may be required, so speak with a loan officer.
Do I have to live in the building?
Yes. You certify that you will occupy one unit, and move-in is generally expected within 60 days of closing. A later date can work if you certify a specific date and a specific event makes it possible, with a 12-month outer limit. Deployed service members can meet the requirement.
Does all the rent from the other units count toward qualifying?
No. A discounted share counts, and only when you have at least six months of reserves in your own funds and show landlord experience or a property manager. The lender also needs the local market to support rental success. If you do not use the rent, the full payment counts as a debt and the reserve test does not apply.
What if the appraisal comes in below the price?
The loan is tied to the appraised value, so you would need to renegotiate the price, cover the gap in cash, or walk away. A reconsideration request with recent comparable sales can sometimes help. A low rent estimate can also factor into the value on a multi-unit property.
Can I move out and keep the fourplex as a rental?
Many buyers do, after living there for a period. The handbook sets no minimum stay, but your certification at closing is a statement of real intent. Plan your move-out as a life change, not the purpose of the purchase.
If you are buying a home and want to see whether a VA loan fits your file, Lendmire can help you compare the options and what each one asks of the file. For more on the choice between programs, see Lendmire’s piece VA Loan vs FHA Loan on a Fourplex With No Money Down.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage serving homeowners and home buyers in 16 states. FHA, VA, conventional and jumbo purchase and refinance loans are arranged through wholesale lending channels; Lendmire brokers the financing and the lender underwrites each application. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. VA Lenders Handbook (VA Pamphlet 26-7), Chapter 3, The VA Loan and Guaranty
3. VA.gov, Funding Fee and Closing Costs
4. VA Lenders Handbook (VA Pamphlet 26-7), Chapter 4, Credit Underwriting
5. CFPB, What is a Closing Disclosure?
This article is part of Lendmire’s VA loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Should a Veteran With a Big Down Payment Choose a Conventional Loan? · Can You Get a VA Loan With Thin Credit and No Down Payment? · How to Confirm VA Loan Eligibility Before You Start House Hunting
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.