
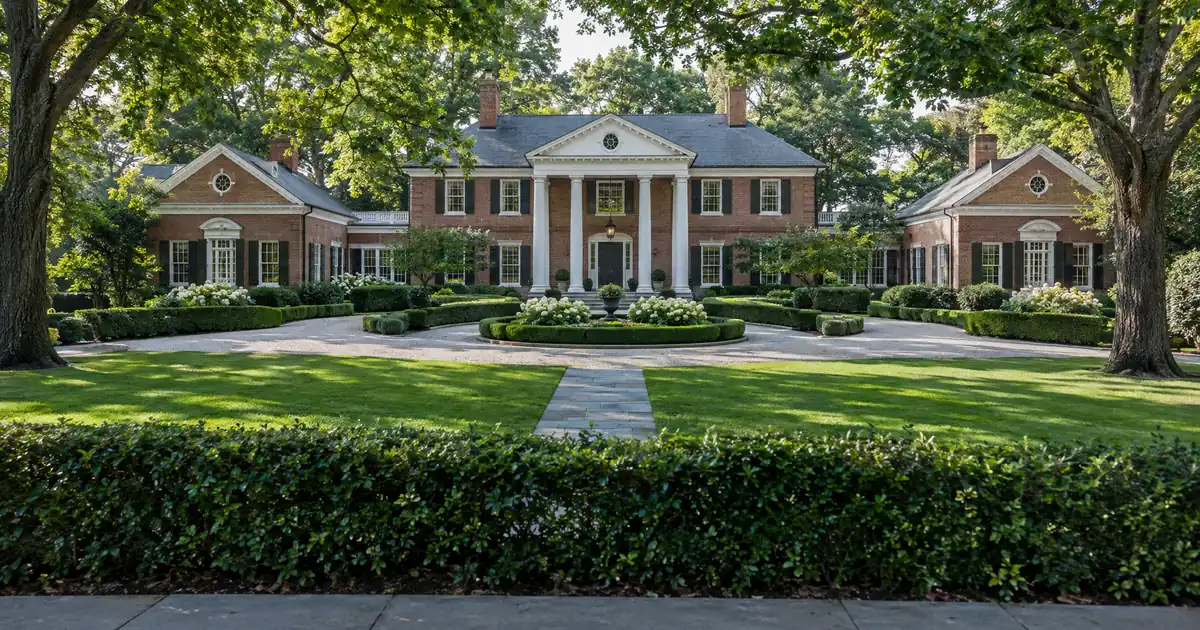
The Quick Read: The appraiser values the real estate only, so the operator builds a file that proves the land, the buildings, the permits and the rent, and keeps furniture, reviews and booking income in their own buckets. That file protects the loan amount, the leverage and the coverage ratio on a large-balance DSCR loan, which is a loan underwritten mainly on what the property earns.
- The lender orders the appraisal. You supply the evidence, and you cannot dictate the conclusion.
- Nightly revenue does not raise appraised value by itself. Comparable sales and the real estate drive it.
- Above $2,000,000, our network’s programs call for two appraisals, and the lower value usually governs.
- Short-term-rental income counts only to $2,000,000, so larger estates often qualify on long-term market rent.
- A clean, consistent document set matters more than a long one.
This article covers a lender-ordered appraisal on a business-purpose rental. It is not an estate-tax or probate appraisal, even though “estate” here means a large luxury property.
Short-Term Rental Calculator
Run the STR numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 15, 2026
Prefilled with starting assumptions — enter your nightly rate, occupancy, taxes, and insurance for a more accurate picture.
Short-term rental income is documented with a 12-month history or a market data report. Program parameters update from Lendmire’s centralized guideline source.
As of Oct 15, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Nightly rate, occupancy, taxes, and insurance are editable estimates. Qualifying income for short-term rentals varies by program — some use appraisal market rent, others use documented STR history or projections — and is confirmed in underwriting. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
What Is the Appraiser Actually Valuing?
The appraiser values the land and buildings, nothing else. A short-term rental is worth the same as an identical home that is not rented that way. McKissock, an appraiser-education publisher, says furniture, fixtures and equipment must be left out of value. It also says business income cannot be counted in the 1007 rent schedule value.
Think of three buckets. Lenders loan against the first bucket and generally do not treat furniture or operations as collateral.
| Bucket | What is in it | In the appraised value? |
|---|---|---|
| Real property | Land, buildings, fixed amenities | Yes |
| Personal property | Furniture, linens, hot tub covers, décor | No |
| Business value | Reviews, brand, booking calendar | No |
Operators trip on this. Strong reviews and a polished listing feel like value, and they are, but they sit in the second and third buckets. The appraiser is not being stingy. The appraiser is being asked a narrower question than the one you are thinking about.
Key Terms Defined
Going-concern value: The worth of a running business, including its brand, bookings and operations, on top of the real estate.
FF&E: Furniture, fixtures and equipment, meaning the movable items that furnish the rental.
1007 rent schedule: An appraisal form that estimates monthly market rent for a one-unit rental. A 2-4 unit property uses Form 1025.
Highest and best use: The legal, physical and financially sensible use that supports the most value, which is why permits matter.
Coverage ratio: Monthly rent divided by the monthly obligation on the loan. A reading of 1.00 means rent matches the obligation.
Lender overlay: A rule a lender adds on its own, beyond what law requires.
Purchase File or Refinance File?
The evidence you lean on depends on the transaction. On a refinance, you have trailing history. On a purchase, you have only the appraiser’s short-term-rent analysis.
| Factor | Purchase | Refinance |
|---|---|---|
| STR income source | Appraisal’s STR analysis | 12 months of operating history |
| Your records | Seller data, if any | Your own bookings and deposits |
| Counted at | 80% of gross | 80% of gross |
| Main risk | Thin or generic rent opinion | History that does not tie to the bank |
Both paths require 1.00 coverage or higher, an experienced investor (twelve months owning income property in the last thirty-six), and a loan at or below $2,000,000. All of it is subject to underwriting. Short-term rentals are not eligible on the no-ratio path.
How Do You Build the Preparation Runway?
Start before the appraisal is ordered. First, decide which income path the file will lean on: the appraisal’s rent analysis, your documented operating history, or long-term market rent. Then build the package in phases.
| Phase | Item | Why it matters |
|---|---|---|
| Before ordering | Permit, license and HOA approvals | Show the use is documented |
| Before ordering | Booking export tied to bank deposits | Proves income is real |
| Before ordering | FF&E inventory, kept separate | Keeps contents out of value |
| After ordering | Plans, survey, improvement permits | Supports a factual correction |
| After ordering | Candidate comps with reasons | Gives context, not steering |
| Before the visit | Access to every structure | Nothing gets skipped |
Appraisers may use two to three years of Airbnb, Vrbo or direct-booking reports, plus third-party analytics. Gather occupancy and average daily rate along with the payout reports. Many appraisers still lean on long-term comps as the baseline, so plan for that.
One consistency check pays for itself. The entity name on the deed, insurance, permits and platform listings should match. A mismatch invites questions that have nothing to do with value.
Documenting the Estate Itself
A multi-structure estate needs an inventory, because appraisers measure what they are shown. List the main house, guest house, pool house, staff quarters, accessory units and any separate parcels. For each one, note square footage, finish level, year of improvements and whether permits exist.
Then list the amenities that are fixed to the land: the pool, courts, docks, gates, wells, solar, and acreage. Receipts, designer invoices and system specifications help the appraiser see quality that photos miss. Under our network’s rules, acreage and rural status also affect eligibility, so know your acreage and its limits early. Above $3,000,000: no rural property, and no more than ten acres on a non-rural one.
Unpermitted work is a quiet problem. A beautiful addition that lacks a permit may support less value than you expect, so surface it before the appraiser does.
Keeping Furniture Out of the Value
Build the FF&E inventory as its own document. List major items by room, with purchase receipts where you have them. This does two things. It shows you are not asking the lender to count contents as collateral, and it gives the appraiser a clean line between what stays with the real estate and what leaves with the operator.
Reviews, Superhost status and a strong calendar belong to the business. Do not write them into an appraiser briefing as reasons for a higher value.
What If the Estate Has Few Comparable Sales?
On a one-of-a-kind estate, comps are thin. A custom property may have no truly comparable recent sale, so the appraiser looks farther out. McKissock says widening the comp search radius can be warranted for unique properties and thin-sales areas, but the appraiser must explain why and how those areas compete with the subject. The appraiser may then weigh three methods. Income may carry more weight where sales are thin, and the cost approach can support distinctive properties.
Your job is to offer candidate comps with reasons, not to dictate. Strong comps match on view, privacy, acreage, architecture, condition and market tier. Two or three strong sales beat ten stretches. Comps should also have STR potential, since a comparable that cannot be rented short-term is a weaker match.
Where the General Rule Breaks
The $2,000,000 STR cap. The STR income path stops at $2,000,000 even though the broader ladder goes higher. A $3,000,000-plus estate therefore usually is reviewed on long-term market rent. Rent at that size is often thin, so run both income paths early.
The sub-1.00 route. If long-term rent does not reach 1.00 coverage, select lenders in the network have programs for coverage from 0.75 to 0.99 through $2,000,000. LTV and terms adjust, subject to underwriting.
The competency problem. Most residential appraisers are not credentialed to value personal property or a going-concern business. Using STR comps without isolating the real estate could raise a USPAP competency issue. USPAP is the appraisal profession’s standards framework.
Permit and zoning status. Permits and zoning for current operations are valuation factors. Short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income.
Vacant or newly acquired property. With no lease or history, the appraiser’s rent opinion carries everything.
Form changes. The standalone 1007 and 1025 are being retired for agency-delivered loans. That may affect the appraiser panels some non-QM lenders use, so expect the paperwork format to shift.
DSCR vs. conventional financing
There are two common ways to finance an investment property, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
How the Appraisal Feeds the Loan
The appraisal sets the value the leverage applies to, and it informs the rent that drives coverage. Across our wholesale network, the ladder steps down with size. The figures below are ceilings at 1.00 coverage or higher, through select programs and subject to underwriting.
| Loan size | Purchase LTV | Cash-out LTV | Credit for this leverage |
|---|---|---|---|
| $150K–$1M | 80% | 75% | 660+ |
| $1M–$2M | 75% | 70% to $1.5M, then 60% | 700+, then 720+ |
| $2M–$3M | 75% | 60% | 720+ |
| $3M–$4M | 65% | — | 700+ |
On a purchase or rate-and-term refinance above $4,000,000, the ceiling is 60%, and these loans are reviewed case by case before submission. The program floor is 660, and 700 above $3,000,000 is the super-jumbo overlay. Reserves are typically six months on the subject property, twelve for first-time investors. Interest-only terms run 120 months to 75% LTV.
Operators often assume two appraisals are a federal rule. They are not. A business-purpose rental generally falls outside it. The two-appraisal step above $2,000,000 is a lender overlay, and it is how most programs in our network treat large balances. For the full picture, see the complete DSCR loans guide. If a value comes back short, Lendmire’s piece on low appraisal options for luxury STR operators on super jumbo DSCR covers the next moves.
A low value does real damage. It shrinks the loan at the same LTV, which means more cash to close.
If the Number Comes In Low
Start by asking what went wrong. A factual error, such as wrong square footage, a missed structure or a permitted addition left out, is your strongest argument, and plans, permits and a survey prove it. Saying the property is unique is a weak argument by itself.
Send a reconsideration request in writing through your broker or the lender, with two or three better comps and a short explanation of why each fits. Do not ask the appraiser to count reviews, staging or furniture. Those requests undercut an otherwise good rebuttal.
A Worked Example
Run the numbers on two fictional estates. These are modeled assumptions, not market data.
Estate A is a $2,400,000 purchase at 75% LTV, with credit at 720+ for this leverage. The loan lands under the $2,000,000 STR cap, so the appraisal’s short-term-rent analysis can feed rent at 80% of gross. Say it supports roughly 1.1x coverage. Two appraisals apply above $2,000,000, and the lower governs. The prep package is the full set above. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Estate B is a $6,000,000 purchase at 60% LTV. The resulting loan lands in the $3M–$4M band, where the ceiling is 65% and the top cell needs 700+ credit, so 60% sits inside it. That loan is above the $2,000,000 STR cap, so STR income is off the table and the file runs on long-term market rent. If that rent supports only about 0.9x, the file would likely fall outside the sub-1.00 route, which is limited to loans of $2,000,000 or less. The operator would need to look at other structures or a lower loan amount, subject to underwriting. The operator should have run this math before making an offer. Every figure here varies by lender and program: guidelines, property type, leverage, and credit profile all apply.
The lesson is simple. Same operator, same style of property, different income path. Size decides which evidence matters.
Next Step
If you are buying or refinancing a high-balance rental property and want to see how the numbers work, Lendmire can help you compare super jumbo DSCR loan options based on the property income, the loan balance, credit profile, leverage, and investor goals. For a side-by-side of the two big paths, read Lendmire’s comparison of portfolio loans and super jumbo DSCR for a luxury STR operator. Lendmire is a broker arranging financing through select lenders in its wholesale network, across 40 states plus Washington, D.C.
This article is general information, not legal or tax advice. Consult a qualified attorney or CPA about your own situation.
Frequently Asked Questions
Can I order my own appraisal?
No. The lender orders the appraisal so the value is independent. You can supply documents, candidate comps and access, and you can request reconsideration in writing through your broker.
Does the appraiser use my nightly rates?
Not directly. Your history matters more on a refinance, and the appraisal’s STR analysis matters on a purchase.
Does the furniture count toward value?
No. Furniture and equipment are personal property, not real estate. Keep a separate inventory so the lender sees a clean split.
What if my permit is pending?
Pending status weakens any rent that depends on short-term use. Municipal permission must be documented for the specific property, so the file may need to run on long-term market rent until the permit is issued.
Do I need two appraisals?
Above $2,000,000, our network’s programs call for two, and the lower value usually governs. Below that, one is typical. All of it is subject to underwriting.
For current guidelines and terms, see Lendmire’s super jumbo DSCR loan programs page.
Lendmire’s self-employed mortgages page presents both super jumbo programs, bank statement and DSCR, side by side.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage focused on DSCR investor financing, helping arrange programs through wholesale and investor-lending channels in 41 markets, including Washington, D.C. DSCR loans are evaluated by the lender on property cash flow rather than personal income, subject to lender guidelines, supporting LLC closings and accommodating investors with four or more financed properties. Scotsman Guide Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. McKissock: Form 1007 and short-term rental appraisals
2. McKissock: Dos and don’ts of sharing comparable sales
This article is part of Lendmire’s super jumbo DSCR loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How to Qualify for a Super Jumbo DSCR Loan in Missouri · How a Super Jumbo DSCR Loan Works for Luxury STR Operators Who Need Projected Income · How to Document Super Jumbo DSCR STR Income for a Cabin or Rural Property
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.