
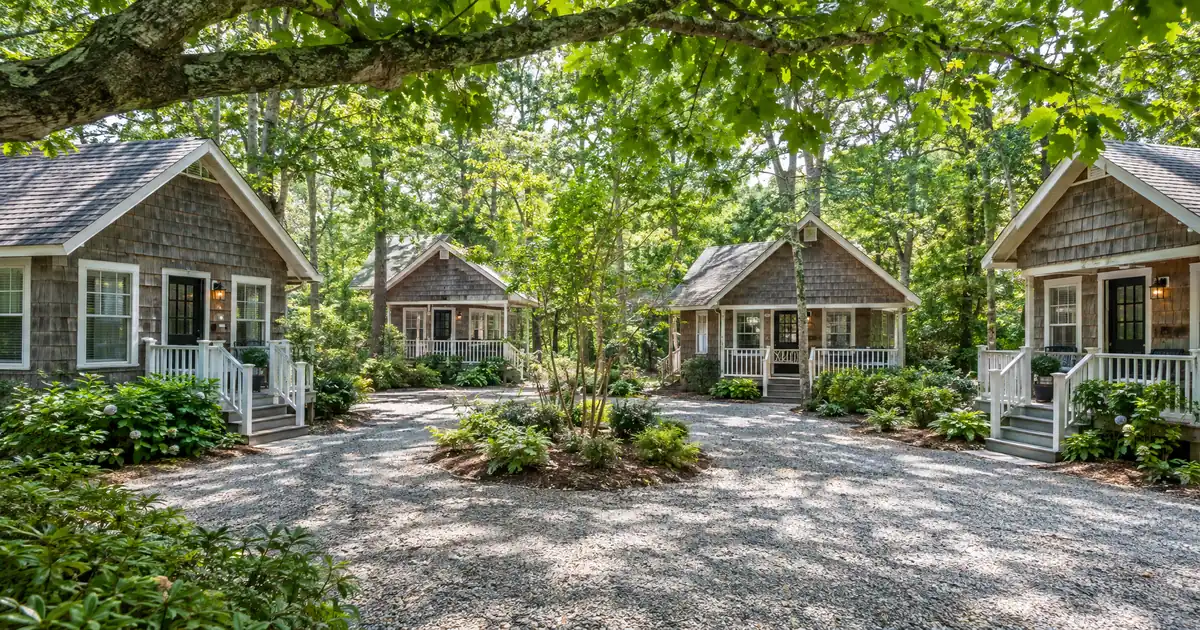
The Quick Read: It depends on the program: four cabins can sit under one portfolio note, but many programs keep short-term rentals on separate loans, so the answer turns on documented hosting income, legal rental use, and eligible construction for every cabin. Four is a small pool, which makes the one-note versus four-notes choice a real cost comparison, not an obvious call.
- Four cabins fit a small-pool portfolio structure in principle, but short-term rental eligibility inside that structure has to be confirmed program by program.
- Each cabin still gets its own appraisal, its own insurance, and its own legal short-term rental use check.
- Short-term rental purchases typically reach up to 75% LTV, while short-term rental refinances and cash-outs reach up to 70% on the strongest files, subject to lender guidelines.
- Log-built cabins are not offered in the network’s DSCR programs. Frame-built cabins are reviewed individually.
- Four separate loans are the clean fallback when the pool does not work.
Does Four Cabins Count as One Property or Four?
Four detached cabins are four properties, even when they share one lender. A lender treats a single building with four units differently from four detached structures, and both differ from cabins on separate parcels.
Short-Term Rental Calculator
Run the STR numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 22, 2026
Prefilled with starting assumptions — enter your nightly rate, occupancy, taxes, and insurance for a more accurate picture.
Short-term rental income is documented with a 12-month history or a market data report. Program parameters update from Lendmire’s centralized guideline source.
As of Oct 22, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Nightly rate, occupancy, taxes, and insurance are editable estimates. Qualifying income for short-term rentals varies by program — some use appraisal market rent, others use documented STR history or projections — and is confirmed in underwriting. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
| Setup | How it is usually treated |
|---|---|
| One building, four units | One property, one appraisal, one lien |
| Four cabins, one parcel | Reviewed case by case; parcel rules matter |
| Four cabins, four parcels | Four properties; pool or separate loans |
The parcel question comes first, because it decides which of those rows you are in. Cabins often share one lot, and a lender may want each one separately platted, insured, and identified in the legal description before it will pledge them individually. If the cabins sit on one tax parcel, expect the lender to ask how the structure will be handled, because a lien is normally recorded against a parcel.
The Two Ways to Finance Four Cabins
A pooled loan secures several properties under one note. Across the wholesale network, both structures exist, and short-term rentals land on the separate side more often than the pooled side.
Pooled structure. One note, a lien recorded against each cabin, and one blended coverage test. The network has a portfolio structure that handles small pools like four properties. A separate term-loan structure is aimed at five or more properties or units. Four cabins therefore fit the small-pool structure, not the larger one, though short-term rental eligibility inside it is a program-level question. No national rule says short-term and long-term rentals must share a pool, and the wholesale network commonly keeps short-term rentals on separate loans, subject to lender guidelines.
A pooled structure also cross-collateralizes the properties. As Nav’s explainer on blanket liens describes the concept, each pledged asset backs the whole obligation, not just its own share.
Separate loans. Each cabin is tested on its own rent. A sale pays off only that cabin’s loan, and a weak cabin cannot drag down a strong one. The cost is more files, more closings, and more appraisals to coordinate.
Closing four loans on the same day does not create a pooled loan. Those are still four separate notes and four separate liens.
What a Lender Checks Before Pooling Four Cabins
Every cabin in the pool has to earn its place. Programs that allow short-term rentals in a pool typically look for the same four things on each property:
1. The cabin will be held for the life of the loan.
2. Its income is documented and short-term rental use is permitted.
3. Title, insurance, legal description, and ownership are clean.
4. It adds coverage or at least does not pull the pool down.
Item four is where many four-cabin deals get tested. A pool is only as good as its weakest member when that member drags the blended ratio under the program floor.
Short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income. Confirm them per cabin, not just per lot.
Which Cabins Are Eligible?
Construction type can end the conversation before income is ever reviewed. Cabin is a style of home, not a program category, and the network treats the underlying build very differently.
| Cabin type | Status in the network |
|---|---|
| Frame-built (stick-built) cabin | Reviewed individually |
| Log home or log-built cabin | Not offered |
| Manufactured or modular-on-chassis | Not offered |
| Barndominium-style building | Not offered |
| New or partly built-out cabin | Reviewed individually; history matters |
If one of your four cabins is log-built, it falls outside these programs entirely. That is a structural problem for the whole plan, not a pricing problem. In a mixed set, only the frame-built cabins can be reviewed under these programs, and the pool or the separate loans would cover those alone.
How Is Short-Term Income Documented Across Four Cabins?
Each cabin needs its own record. Typical support includes trailing platform statements or management reports, bank deposits that match them, and an appraiser’s short-term rental analysis or a market-data projection. Most short-term rental programs in the network expect about 12 months of hosting history. Projection tools can support a file without a record, but projected income is usually discounted.
Cabins add a seasonality wrinkle. A mountain or lakeside cabin may earn most of its income in a few strong months, which makes a full trailing year more useful than a partial one. A rural location can also thin out the comparable data a lender relies on. If one cabin is new, expect it to be underwritten on projections while the other three lean on history.
How Does a Lender Value Four Cabins?
Each cabin is appraised on its own. A pooled note changes how the debt is secured, not whether every property’s value gets checked.
Appraisal forms add friction. The 1007 rent schedule and the 1025 small-income-property report were built around monthly long-term rent. Fannie Mae’s appraiser update says the 1007 was not designed for appraising single-family properties used as short-term rentals. McKissock’s appraisal education piece explains what the form actually measures, and HousingWire makes the same point for DSCR lending. The takeaway is simple: a long-term rent schedule will not capture nightly income, so the lender leans on trailing statements and a short-term rental analysis instead.
They support income. They do not replace an appraisal of what the cabin is worth.
Wells, septic, and road access also matter for cabins. A lender may ask whether each structure has adequate utilities and legal access, since four dwellings on private systems are a different risk from one.
How Pooled Coverage Works (With an Illustration)
Pooled coverage is total rent from every property divided by total monthly debt service, which means principal, interest, taxes, insurance, and any HOA dues. One strong cabin can offset a weak one.
Here is an illustration with modeled assumptions, not market data. Assume every cabin carries equal debt service. Three cabins each cover their payment at about 1.25x, and one covers it at about 0.80x. The pooled ratio lands near 1.14x, which clears a 1.00 floor.
Now stress it. Say a slow season pulls two cabins down to about 0.85x while the other two stay at 1.25x. The pool drops to roughly 1.05x. It still clears, but with little room.
Run the same cabins as four separate loans and the picture changes. The 0.80x cabin would be tested alone, and 1.00 is where many select programs start. A separate select-lender path takes coverage below 1.00 with leverage and terms adjusted, but that is a different program with a different cost.
One caution applies either way. Clearing 1.00 is not the same as positive cash flow. The ratio compares rent to the full monthly obligation only, so repairs, vacancy, management, utilities, and capital needs sit outside it. Cabins often carry higher turnover costs than ordinary rentals, which makes that gap wider.
Leverage, Credit, and Reserves for a Four-Cabin File
The lowest result controls. A lender reviews structure first, then values, pool leverage, coverage, and finally credit and reserves.
On typical short-term rental files, purchases reach up to 75% LTV on the strongest files. Refinances and cash-outs on short-term rental collateral reach up to 70%. Expect a minimum score around 640 and a 1.00 coverage floor on purchases, with refinances carrying their own 1.00 floor. Standard programs run up to $3,000,000 per loan, and smaller balances route through select lenders in the network. Those are typical ranges, not promises. Each figure is subject to lender guidelines and a complete review of property type, leverage, and credit.
A larger down payment lowers the monthly obligation and can lift the ratio. It does not erase leverage caps, credit floors, reserve rules, or property eligibility. The strongest files clear both tests: enough equity and enough rental coverage.
Reserves vary by lender, leverage, loan size, and transaction type. Around six months of PITIA is common, and on a pooled note they are often sized to the whole pool. That means four cabins can require more liquidity at once than one cabin does.
One practitioner pattern shows up often in multi-property files. Borrowers focus on the headline ratio and forget that the weakest cabin’s documentation can stall the whole pool, while on separate loans the same weak cabin only affects its own file. Gathering all four sets of statements before choosing a structure usually shows which route is realistic.
DSCR vs. conventional financing
There are two common ways to finance an investment property, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
The Edge Cases That Change the Answer
Release clause. A release clause lets you sell one property without paying off the entire loan. It is a contract term, not a legal right. Without one, selling a single cabin becomes a negotiation with the lender, which matters if you might sell one cabin later.
Cross-default. A default on one cabin can count as a default on all of them. That risk does not exist with separate loans.
Adding a cabin later. Adding a fifth cabin to an existing pool is usually a new underwriting event. Substitution language is uncommon.
Mixed pools. A cabin with low-cost existing debt can stay out of the pool, and a short-term rental can sit on its own loan while long-term rentals pool together.
Personal use. DSCR loans are designed for non-owner-occupied investment properties. Because they are business-purpose investor loans, they are reviewed differently from a standard owner-occupied mortgage. Plan on the cabins being investment properties, not a place you live.
Pool or Separate Loans? The Investor Decision
For a small pool, pooling often gains little. A saving appears mainly when you want one closing, one credit review, and blended coverage that lets strong cabins carry weak ones.
| Factor | One pooled note | Four separate loans |
|---|---|---|
| Coverage test | Blended across cabins | Each cabin alone |
| Selling one cabin | Needs a release clause | Pays off one loan |
| Default risk | Can reach all cabins | Stays with one cabin |
| Files and appraisals | One file, four appraisals | Four files |
Pooling tends to favor an investor who plans to hold all four cabins long term, has solid history on each, and wants the simplest administration. Separate loans tend to favor an investor who may sell one, has one uneven cabin, or has a cabin that falls outside a pool’s eligibility.
If you plan to buy the next cabin with equity from these four, Lendmire’s piece Can a Short-Term Rental Owner Cash Out a Pool to Buy the Next One? covers that decision. Separate loans keep each cabin’s equity accessible on its own, while a pooled note ties the cabins together.
What to Do If the Answer Is No
A no on pooling does not end the plan. The fallback is four separate loans, each judged on its own rent. If one cabin lacks history, finance the three seasoned cabins first and add the fourth once it has a record. If one cabin is ineligible by construction, finance the others and plan the ineligible one around these programs.
If the issue is the parcel, ask whether the cabins can be separately platted. That is a local land question, so it needs a local answer before a lender can price anything.
Pre-Application Checklist
- Trailing statements and matching bank deposits for each cabin
- Short-term rental permits or HOA confirmation for each structure
- Insurance quotes for each cabin
- Legal descriptions and parcel identification
- Construction type for each cabin
- Documentation of well, septic, and access
- Entity and ownership details
Tax treatment varies; consult a qualified professional before relying on any deduction.
For a broader view of how these loans work, see Lendmire’s complete DSCR loans guide. If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals. Qualification is subject to lender guidelines, and nothing here is a commitment to lend.
Key Terms Defined
Blanket or portfolio loan: a single loan secured by two or more properties, with a lien recorded against each one.
Cross-collateralization: a setup where every pledged property backs the whole debt, not just its own share.
Release clause: a negotiated loan term that lets you sell one property without paying off the whole loan.
PITIA: principal, interest, taxes, insurance, and any association dues, the monthly obligation used in the coverage ratio.
Coverage ratio (DSCR): rental income divided by that monthly obligation.
Form 1007: an appraiser’s rent schedule built around monthly long-term rent.
Frequently Asked Questions
Can the four cabins be listed as one rental on a booking platform?
That is an operations choice, separate from financing. A lender cares about documented income per cabin, so keep records that show each cabin’s bookings and deposits even if you market them together.
What if one of my cabins is log-built?
That cabin is not offered in the network’s DSCR programs, because log homes fall outside them. The frame-built cabins can still be reviewed individually, either in a pool or on separate loans.
Does a new cabin count toward the pool?
A new or partly built-out cabin is reviewed individually. Without about 12 months of hosting history, income is usually based on a projection, which is often discounted, so a lender may treat it more cautiously than the seasoned cabins.
Does having four cabins change insurance?
Yes, because each structure is insured and reviewed separately, and the premiums feed the monthly obligation in the coverage ratio. Get a quote for each cabin before choosing between a pool and separate loans.
Can cabins on separate parcels go into one pool?
Often yes, since each parcel can carry its own lien. The harder case is several cabins on one parcel, where the lender needs to confirm how each structure is identified and insured.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income, not the borrower’s W-2 history — a practical fit for LLC-titled portfolios and self-employed investors. All scenarios remain subject to lender review and program guidelines. Two consecutive Scotsman Guide Top Mortgage Workplace recognitions (2025, 2026).
Get Started
Ready to find the right loan for you?
In about two minutes you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Fannie Mae – Appraiser Update
3. McKissock Learning – Form 1007 and Short-Term Rental Appraisals
4. HousingWire – Short-Term Rentals Are Breaking the Appraisal Playbook
This article is part of Lendmire’s short-term rental loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Can You Buy a Duplex Rental With a DSCR Loan and No Tax Returns? · How the Portfolio DSCR Loan and Rental Term Loan Differ · DSCR Loan Requirements for Buying a Duplex as a Rental
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.