Jumbo Vs Super Jumbo DSCR For A Luxury Short-term Rental
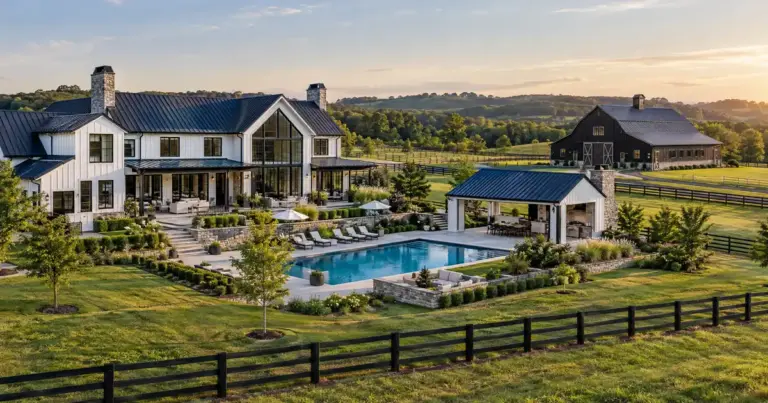
Neither label shows up in any government rulebook.

Articles about financing short-term and vacation rentals. Start with the Short-Term Rental Loans program page or browse the Short-Term Rental Loans Guide Library.
Neither label shows up in any government rulebook.
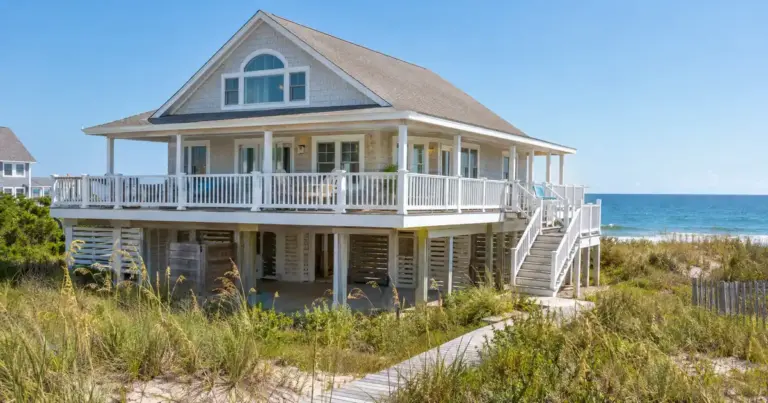
Neither choice changes how the property qualifies — coverage still runs off rental income, subject to lender guidelines.
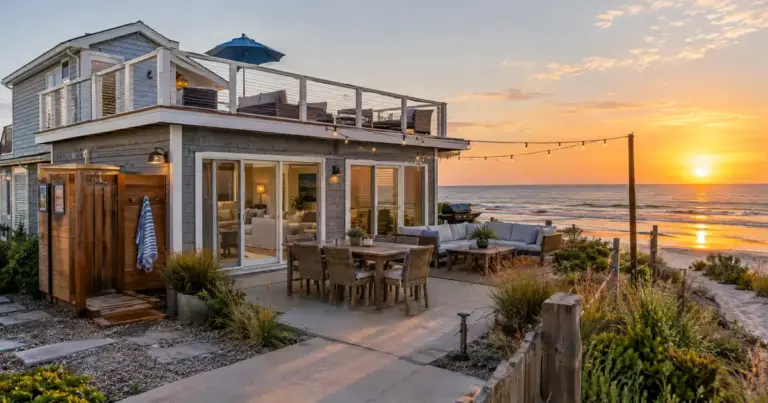
STR DSCR Vs Bank Statement Loan For The Self-employed — These solve two different problems.
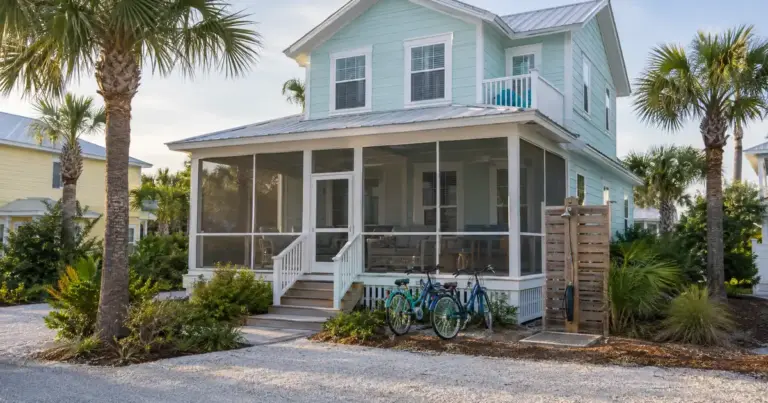
The right answer depends on portfolio size, existing financing, and how much administrative overhead an investor wants to carry.
Neither option is “better” on paper.
If you’re buying a rental, DSCR is usually the cleaner path.
Above $4 million, every file goes through case-by-case review before it’s even submitted.
Standard mortgage financing won’t touch these units, so the entire condotel market runs through non-QM and DSCR-style investor lending instead.
Loan size can run from $150,000 up through multi-million-dollar purchases, with leverage stepping down as the balance grows.
Nightly-rate income looks great on paper, but lenders don’t use the raw number.
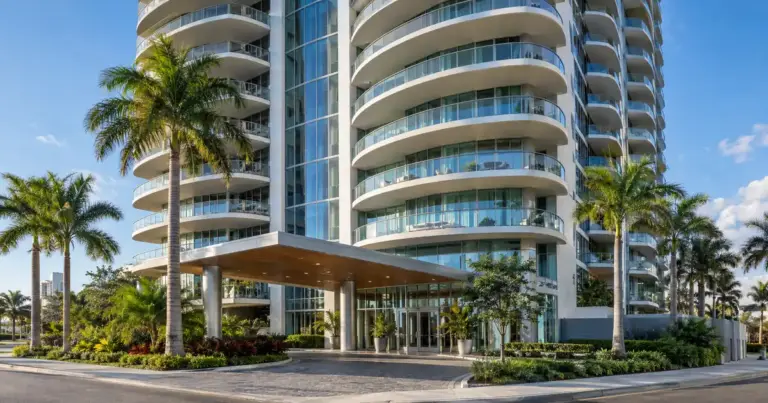
Fannie Mae and Freddie Mac won’t buy loans on buildings that operate like hotels, so those files never reach agency underwriting at all.
Existing guest reservations do not transfer to a buyer — the trailing income record does. A calendar full of future reservations feels like proof of value.
It’s the legal foundation behind most DSCR financing on short-term rentals.
Short-term rental income gets documented separately from the vesting question, usually at a discount to gross platform revenue.
No single number “guarantees” approval — the file, the property, and local rules all matter.