
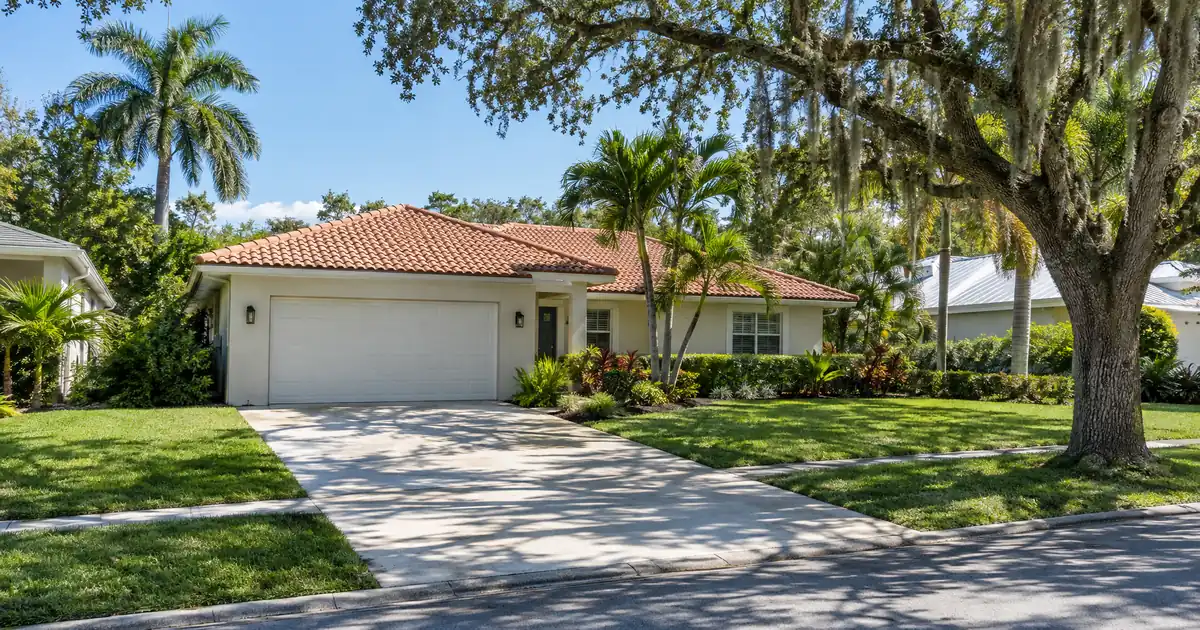
Two Pinecrest owners can both hold serious equity and sit in opposite positions on a cash-out file. One owns a large-lot estate with a Zillow-style average value near $2,258,425 (Zillow). The other owns a condo in the Downtown Dadeland pocket, where Redfin shows a median sale price around $340K (Redfin). For a cash-out refinance investment property strategy, the math favors the condo owner on coverage and the estate owner on raw equity. Only one of those two can clear a 1.00 coverage ratio on rent alone.
Lendmire, a DSCR-focused mortgage broker (NMLS# 2371349), places DSCR investor financing for Pinecrest, Florida through non-QM wholesale channels that cover 41 markets, including Washington, D.C. This piece is about the owner who already holds the property and wants to pull equity out for the next deal.
DSCR Cash-Out Calculator
Run the cash-out numbers in Pinecrest, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read: A cash-out DSCR refinance in Pinecrest, Florida is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the deal works from seasoning check to appraisal to rent schedule to lender review, and the property type decides how clean that path is.
- Village single-family rents sit well below what a multimillion-dollar average value would need, which leaves coverage well under 1.00.
- Downtown Dadeland condos pencil far better, since rents there run much closer to their much lower purchase values.
- Cash-out LTV tops out at 75%, with about 6 months of ownership seasoning.
- Pinecrest’s renter share is small, so rental comps are thin.
Pinecrest Market Snapshot
A quick read on the Pinecrest investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | Median listing $4.3M (Wikipedia: Pinecrest, Florida) |
| Typical rents | $1,898 avg (Apartments.com Pinecrest Rent) |
| Recent appreciation | +2.8% yoy (Zillow Home Values Pinecrest) |
| Population | 18,462 population (Census Reporter Pinecrest, FL) |
| Employment | 30,000+ employees (Baptist Health South Florida) |
Where the Coverage Math Actually Clears
Pinecrest is an equity story, not a cash-flow story. The village is small in both residents and land area (U.S. Census Bureau), its population has been flat for two decades, and value growth has come from land scarcity and high-net-worth buyers. Zillow’s rental data puts the average house rent high in absolute terms, with a very wide range from modest units to extreme outliers (Zillow Rental Manager). That spread tells you how different the tenant segments are.
Run the numbers on an estate. These are modeled assumptions, not sourced deal data: a home valued near the Zillow average and rented at roughly the $6,500 average. That is a gross yield around 3.5%. Once you load full PITIA (taxes and insurance included), coverage lands under 0.5x at 75% LTV. Cut leverage to half of value and it still sits below 1.00. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Sub-1.00 files are not dead, but they get harder. A lender may review a sub-1.00 program, interest-only structuring, lower leverage, stronger credit, and deeper reserves. Any of those is subject to lender guidelines, credit approval, and property review, and none is a given. Estate owners with large balances sometimes compare a portfolio or jumbo lender against a DSCR cash-out. It’s a fair comparison to run.
Now the condo. Using the same modeled approach with a $340K value and the $3,100 Dadeland median rent (Redfin rental data), full-PITIA coverage comes in around 1.3x at 75% LTV. That is before association dues, which can erase most of that cushion. Pull the building’s actual dues before trusting any of it. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
The Dadeland Pocket (Small Dollars, Clean Math)
The Dadeland-adjacent condo pocket is the most realistic DSCR fit for a cash-out. It sits near the Dadeland retail and transit corridor and draws on the same Baptist Health and US-1 employment base. South Miami Hospital borders Pinecrest along US-1, and Baptist Health South Florida runs 12 hospitals with more than 29,000 employees. The University of Miami sits roughly 15 to 20 minutes north.
The catch is the dollar scale. Cash-out proceeds are capped by a 75% LTV on a modest value, so the check is small. This pocket is a good place to hold a cash-flowing asset, not a good place to manufacture large down payments for the next deal. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
The building’s leasing rule matters too. Per Miami Condo Lifestyle, each unit owner can rent twice per year, with a six-month minimum lease. That fits a standard long-term-rental file and rules out high-turnover leasing. Confirm the specific building’s cap before assuming turnover flexibility.
Expect the condo questionnaire, the master insurance certificate, and HOA financials to be part of the file. Missing condo documents stall reviews more often than a weak ratio does.
North Pinecrest and Snapper Creek: Appreciation Leg, Not Cash-Flow Leg
North Pinecrest holds large private estates, and Snapper Creek has mixed acreage lots, some closer to canal access. Tenant demand here comes from relocating executives and medical staff, and it is thin by volume. Skip these for coverage-driven cash-out. The math doesn’t work at current values.
The appreciation side is real, though. NeighborhoodScout puts latest-twelve-month appreciation at 7.53%, above 90% of Florida places. Zillow shows a slower 2.8% for the village average. Redfin’s recent-sale median reads higher still, around $3.4M, because it measures closed sales rather than a value index (Redfin). These are different measurements, so treat them as a range.
The consequence for a cash-out: equity may be abundant, but rent won’t support proportional leverage. Size each pocket on its own and don’t apply a villagewide assumption. The stronger play might be refinancing the estate at conservative leverage, if coverage is reviewable at all, versus cashing out a smaller asset that cleanly clears 1.00. Investors chasing appreciation could argue the other way.
Appraisal Friction: The 33156 Comp Problem
This is the plumbing detail that moves real dollars. Zillow’s ZIP-level average for 33156 is $1,543,591, versus $2,258,425 for the village footprint (Zillow ZIP data). The ZIP spans Pinecrest and lower-priced adjacent areas. If an appraiser pulls ZIP-wide comps instead of in-village sales, valuation on a cash-out can swing by hundreds of thousands of dollars.
Give the appraiser the in-village sales history up front. Also know what happens on the rent side. With few true rental comps, the rent schedule leans on whatever small sample exists. The 2020 ACS numbers show a 7.8% rental vacancy rate against 2.1% for owners (Wikipedia, citing ACS), and renters are only 19.4% of households (Towncharts). Fewer comps, longer re-tenanting. Budget for that.
Zillow calls the rental market “cool,” and Apartments.com shows rent up only 1.2% year over year (Apartments.com). Average rent there runs $1,898, with two-bedrooms near $2,391 and three-bedrooms near $3,134. Don’t underwrite rent growth to fund coverage.
What Working Brokers See in Markets Like This
Working DSCR brokers see a recurring pattern in high-value, owner-dominated suburbs: the equity is huge, the rent schedule is thin, and the file stalls on valuation and rent support rather than credit. The owner expects the equity to qualify the loan. The lender looks at rent against full PITIA and at comp quality. Files that move smoothly usually arrive with a clean lease, a tight rent comparable set, and a conservative leverage target.
Duplexes and Guesthouses: Scarce Product
Small multifamily exists inside the village, but barely. One listing snapshot shows a duplex with two 3-bedroom, 2-bath units (United Realty listing). With so few sales, each one carries outsized weight in valuation. A duplex owner here has an unusually strong asset for coverage and an unusually thin comp set.
Don’t count a guesthouse as income. The village code defines an accessory guesthouse as not to be rented (Village of Pinecrest Code), so it adds nothing to rent used for lender review. Better multi-unit stacking plays tend to sit just outside the border, in Kendall, South Miami, and Palmetto Bay, on the same US-1 employment corridor at lower price points. Those markets have different comp sets and different tenant depth, so they are different files.
How the Cash-Out File Is Built
On most files, the parameters look like this, subject to lender guidelines and credit review:
- Leverage: cash-out LTV is capped at 75%. Purchase leverage is higher, and the two shouldn’t be confused.
- Seasoning: about 6 months of ownership, measured from title recording.
- Coverage: a 1.00x baseline is typical, meaning rent used for lender review against PITIA. Some lenders review lower ratios with stronger compensating factors, lower leverage, or different pricing.
- Credit: a 620 floor on most programs, with tiers at 660, 680, and 700.
- Reserves: about 6 months PITIA, stepping to about 9 months on larger balances above $1,500,000.
- Loan size: up to $3,000,000 on standard programs. Smaller balances route through select lenders.
Equity available depends on rent used for program review, PITIA, reserves, and the 75% ceiling. It is never a guaranteed figure. LLC-titled properties can be reviewed, subject to lender program eligibility. Read the DSCR qualification mechanics for the ratio math, Lendmire’s DSCR-versus-conventional breakdown for the comparison with income-based loans, and pulling equity with a DSCR cash-out for the full cash-out framework. State-level detail lives on the Florida DSCR financing page.
Before underwriting any specific Pinecrest deal, verify current taxes, insurance, and local rental rules with qualified local professionals. Those cost items move the coverage number more than most investors expect.
Frequently Asked Questions
How do you qualify for a DSCR loan in Pinecrest, Florida?
Qualification centers on the property’s rent against its full monthly obligation, plus credit, reserves, and leverage. A 1.00x baseline is common, and a 620 credit floor applies on most programs. Pinecrest’s thin rental comp pool makes the rent schedule and appraisal the parts of the file that need the most care. Final eligibility rests with the lender.
What are the requirements for an investment property loan in Pinecrest, Florida?
Expect about 6 months of seasoning for a cash-out, a 75% LTV ceiling, reserves around 6 months PITIA, and a rent schedule that supports the coverage ratio. Condos add a project review. Eligible property types exclude manufactured homes, log homes, and barndominiums. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Pinecrest, FL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What loan-amount ranges may DSCR lenders review for Pinecrest rental properties?
Standard programs run up to $3,000,000, which covers most Pinecrest condos, duplexes, and many estate balances. Lendmire arranges DSCR investor loans, with smaller balances routed through select lenders in the network.
Does a Pinecrest guesthouse count toward DSCR rental income?
No. The village code describes an accessory guesthouse as not to be rented, so lenders have no legal rent to count. Only legally rentable units contribute to qualifying income.
Can ZIP-wide comps hurt a Pinecrest cash-out appraisal?
Yes. The 33156 ZIP average sits far below the village average, and a comp set that leans on ZIP-wide sales can drag valuation down. Supply the appraiser with in-village sales to support value, since equity available at 75% LTV depends directly on the appraised figure. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
The Real Choice
Pinecrest investors end up choosing between two structures. They can keep cash-out leverage modest on a high-value estate, accepting sub-1.00 coverage, heavier reserve demands, and stricter eligibility review, in exchange for harvesting the village’s strongest equity. Or they can cash out a smaller condo or duplex asset that clears 1.00 cleanly, accepting a small check in exchange for a file that moves through review with less friction. Neither is wrong. They are different bets on where Pinecrest’s value actually sits.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. Eligibility is generally reviewed around a property’s rental income rather than personal income, subject to lender and program guidelines, which suits self-employed investors and LLC-owned portfolios. Lendmire was recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a 2025 Scotsman Guide Top Mortgage Workplace. Investors can get a DSCR quote or call 828-256-2183.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Home Values: Pinecrest
2. Redfin: Downtown Dadeland Condominium
4. Apartments.com: Pinecrest Rent Trends
5. Census Reporter Pinecrest, FL
6. Baptist Health South Florida
7. U.S. Census Bureau QuickFacts: Pinecrest village, Florida
12. NeighborhoodScout: Pinecrest
13. Redfin
14. Zillow ZIP data
15. Towncharts
17. a 2026 Scotsman Guide Top Mortgage Workplace
18. a 2025 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Pinecrest, Florida: Can the Rent Support a Cash-Out in Pinecrest? · DSCR Cash Out Refinance in Hialeah, Florida: Duplex Equity Along the Metrorail Line · DSCR Cash Out Refinance in North Miami, Florida: What It Takes to Qualify on $2,400 Rent
Guides: Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.