
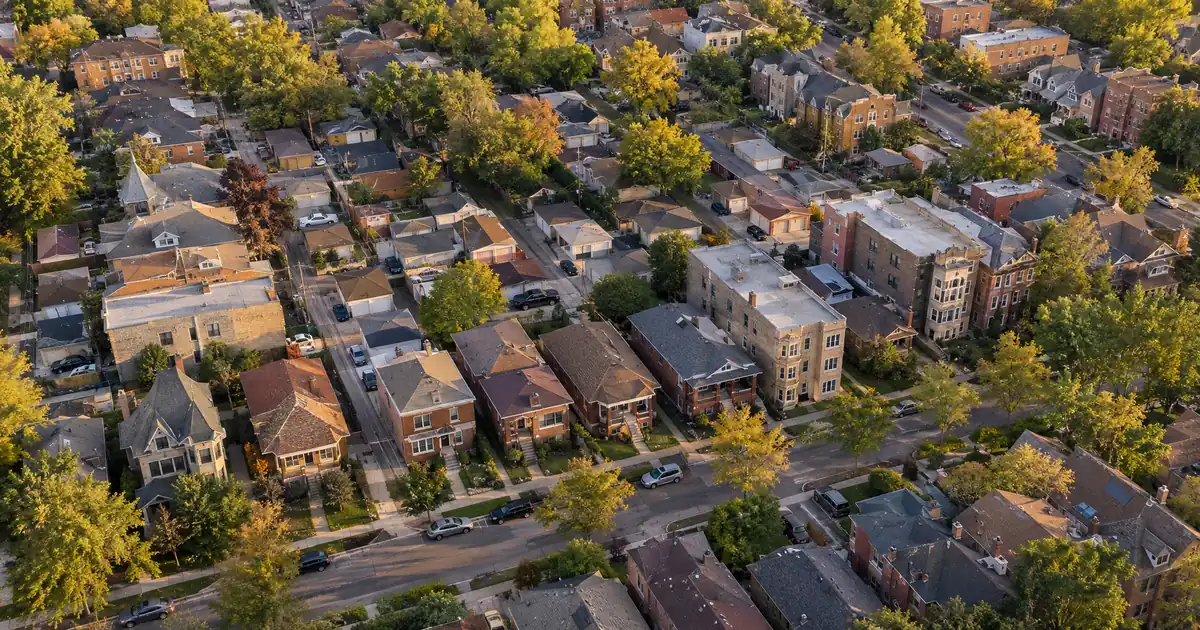
Can a Chicago two-flat you already own throw off enough equity to fund the next purchase, or does the math fall apart when the appraisal lands? Sometimes it works, and the answer turns on two numbers: what the rent covers against the full monthly carrying cost, and what an appraiser says the building is worth on an income-driven valuation. A DSCR cash out refinance on an investment property generally caps at 75 percent loan-to-value, so the building has to pass both tests, not one. Chicago, Illinois is one of the 41 markets — 40 states plus Washington, D.C. — where Lendmire places DSCR loans for investment-property borrowers. Lendmire is a DSCR-focused mortgage broker (NMLS# 2371349), and what its deal desk sees in this city is mostly a story about small-building economics.
DSCR Cash-Out Calculator
Run the cash-out numbers in Chicago, IL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A DSCR cash-out refinance on a Chicago, Illinois investment property is underwritten primarily on the property’s rental income measured against its full monthly obligation, with a lender sizing proceeds off an appraised value generally capped at 75 percent loan-to-value after the seasoning period, so rent and appraisal both have to hold.
- Pilsen, Bridgeport, and Avondale two-flats offer stronger rent-to-value than Logan Square or the North Side.
- Appreciation is uneven: Near South Side medians slipped 2.4 percent while the citywide median rose 6.9 percent.
- Downtown holds 56.6 percent of proposed new units, so oversupply risk sits there, not in neighborhood flats.
- Cash-out generally needs about six months of ownership, measured from title recording.
- Lenders see gross rent against full PITIA. Real after-expense cash flow on older buildings runs thinner.
Chicago Market Snapshot
A quick read on the Chicago investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Recent appreciation | $427,500 (+6.9%) (Option Premier, “Where Chicago) |
| Cap rates | 6–7% cap (thechicagolandlawyer.com — What Is a Good Cap Rate in Chicago) |
| Vacancy | 5% vs 8.5% national (Bisnow (Chicago multifamily)) |
Where Does the Rent-to-Value Case Hold Up?
Pilsen, Bridgeport, and Avondale are where Chicago two-flat rent-to-value is strongest for an equity pull. Entry prices run lower than on the North Side while two- and three-bedroom rents stay comparatively firm. Appreciation is the weaker leg, so these cash-outs depend on rent, not price growth.
Pilsen is a Mexican-American arts and restaurant district with historic two-flats, a busy 18th Street corridor, and the National Museum of Mexican Art nearby. One agent blog puts Pilsen’s median roughly 30 percent below Logan Square’s. That is anecdotal, and the same agent’s claim of gross yields above 7 percent on multi-flats is too. Treat both as directional.
Bridgeport sits minutes from the Loop, with the White Sox ballpark and a growing restaurant scene feeding the rental market, and Chinatown is next door. Avondale, tucked beside Logan Square, carries more affordable two-flats and draws young professionals and families. A published analysis says amenity spillover is narrowing the rent gap with Logan Square in some segments.
Here is the catch. Neighborhood-level price and rent data in Chicago comes mostly from agent blogs, not an official dataset, and the sources conflict. So the number that matters for a cash-out is not any headline median. It is the comparable sales an appraiser pulls for your exact building type, on your block. For equity extraction, comps depth beats neighborhood reputation every time.
One more flag for the South and West Sides generally. Some sources describe pockets there as slower to recover and more volatile on pricing. Rent coverage can look excellent on a lower-priced flat while the value never moves enough to release equity. That is a reason to lean on the rent side of the file and treat any appreciation as a bonus.
The Appreciation Trade (and Its Price)
Logan Square is the appreciation play, not the yield play. Higher basis means thinner coverage, and the cash-out only works if rents sit at the top of the local range. Buyers here get greystones, walk-ups, and Blue Line access, but they pay for them.
Two agent blogs disagree on the Logan Square median by a wide margin, so a range is the honest way to say it: well above Pilsen, with the exact figure depending on the source and the sample. Rents for two-bedrooms near the Blue Line reportedly run in the mid-$2,000s and up, per the same agent source above. Tenants skew toward young professionals and creatives who value transit.
Run the numbers on a modeled $700,000 two-flat with two units at $2,500 each. That price and those rents are illustrative assumptions, not market data. At 75 percent loan-to-value, with taxes and insurance included in the carrying cost, the coverage number lands right around 1.0x, with almost no cushion.
Now shave rents by 10 percent, which is easy to do when one unit turns over or an appraiser’s rent schedule comes in light. The number slips below 1.00x. A sub-1.00 structure may be available through select lenders, as may lower leverage or an interest-only restructure, and lenders would review those subject to credit approval, reserves, and property review. But the question worth asking first is whether to use them. If the property is being stretched to qualify at every neighborhood you look at, that points to a submarket problem, not a loan-type problem.
The same logic applies to the broader North Side. Lakeview, Lincoln Park, and Bucktown carry stable demand, and agent sources describe two-flats and single-family homes there priced well into the high six figures and above. The ratio only works at the top of the rent range, and the appreciation story has to justify the thin current yield. Some investors will take that trade, and it can be defensible. It just isn’t the same trade as a Pilsen flat.
Reading a Three-Flat Underwrite Honestly
A lender’s coverage number and an owner’s real cash flow are different animals in Chicago. Gross rent against full carrying cost can look healthy on a building whose after-expense income is far thinner, which matters when a cash-out raises the balance.
A Chicago attorney’s sample underwrite is a useful illustration. It models a $450,000 three-flat with two units at $1,600 and one garden unit at $1,400, or $4,600 a month in total. It puts the expense ratio at about 51 percent of effective gross income, which it calls normal for older stock where the landlord pays water and common-area heat. It also shows how a listing’s advertised cap rate of 8.6 percent shrinks once vacancy, management, reserves, and snow removal come back into the calculation.
Model that building at 75 percent loan-to-value with taxes and insurance included, and the DSCR ratio lands around 1.4x. That figure is my modeled assumption layered on the attorney’s example. It looks comfortable. But roughly half of that $4,600 never reaches NOI, and the owner’s real free cash flow after a larger balance is a much tighter picture than 1.4x suggests. Both facts are true at once.
The appraisal side matters just as much. The same source puts stabilized cap rates around 6 to 7 percent in a solid neighborhood, with prime areas lower and tougher areas higher. Small-building valuations are income-driven, so a refinance appraisal on a two- to four-flat will likely use a cap rate near or above 6 percent. Run that NOI through a 6 to 7 percent cap and the value comes in at or below the purchase price, not above it. A rent shortfall shows up directly as a lower value and a smaller cash-out. Don’t assume institutional-grade cap rates on a neighborhood three-flat.
This one is a genuine toss-up for some borrowers. The ratio clears easily, but sizing the cash-out to the conservative NOI is the safer way to run it. The upside is a bigger check. The downside is carrying a heavier balance on a building whose true cash flow is half what the rent roll suggests.
The Mechanics: Seasoning, 75 Percent, and Reserves
The core cash-out parameters are straightforward. Seasoning is generally about six months of ownership, measured from title recording. The loan-to-value ceiling on cash-out is 75 percent, which is lower than the purchase-side ceiling, so don’t borrow the purchase number when you estimate proceeds. The DSCR baseline most programs build around is 1.00x, where rent used for lender review covers the full PITIA. Some lenders may review lower scenarios, but those usually mean stronger compensating factors, lower leverage, or different pricing.
Credit tiers generally step at 620, 660, 680, and 700, with 620 as the floor, and stronger scores tend to improve the file. Reserves are typically about six months of PITIA, or about nine months on balances above $1,500,000. Loan sizes run up to $3,000,000 on standard programs, and smaller balances route through select lenders in the network. That last point matters in Chicago. A partner-content piece in Chicago Agent Magazine notes that several national programs exclude condos, properties above four units, or loans under certain size floors, and that Chicago two-flats can fall below those floors. Treat that as sponsored context, not a rulebook. It does flag why a lower-priced south or West Side flat can need a different lender lane than a mid-priced one.
For entity-held buildings, LLC ownership is workable, subject to lender program eligibility. Review details remain subject to lender overlays, and equity available is not a guaranteed cash figure. It depends on rent used for lender review, PITIA, reserves, and the 75 percent ceiling. Lendmire’s DSCR guide covers the underlying qualification logic if the mechanics are new.
On the flip point: if you hold only one or two financed properties personally, have clean traditional employment income, and the building is easy to document, a conventional cash-out may carry a lower cost and be worth pricing first. The program-to-program comparison lays out where that line sits. DSCR becomes the practical lane when the portfolio is entity-held, when the file’s personal income is hard to document, or when you’re past four financed properties and the conventional lane runs out.
On files from markets built around older small multifamily like this one, the usual friction point isn’t the ratio. It’s the rent documentation and the appraisal. Leases that are month-to-month, a unit rented informally, or an owner-occupied unit that has to be priced at market rent can all create drag. Cleaner files from a documentation standpoint tend to arrive with current leases for every unit, a rent schedule that matches the appraiser’s, and the reserve balance seasoned in the account before the file goes to the lender. Lendmire’s deal desk sees that pattern repeatedly.
Skip the Downtown Condo Core.
River North, Streeterville, and the West Loop are the weakest fit for a DSCR cash-out in this city. Condos are often excluded or restricted by DSCR programs, HOA dues cut into coverage, and the new-supply pipeline is concentrated exactly there.
Cushman & Wakefield reports Chicago multifamily occupancy of 94.9 percent, above the 10-year average of 93.8 percent, with 24 of 26 submarkets holding stabilized occupancy of 93.0 percent or higher. The risk is the pipeline, not the occupancy. Of 31,054 proposed units, 56.6 percent sit downtown, led by West Loop and Fulton Market at 10,177 and the Gold Coast, Old Town, and Near North area at 3,758.
The oversupply risk lives in downtown and Class A product, not in neighborhood two- to four-flats. That supports the outlying-neighborhood thesis. It also makes a downtown condo a riskier building to refinance for cash, because new competing inventory pressures rents just when you need an appraisal to hold.
Demand Anchors That Hold Up in a Soft Population Picture
Chicago’s rental demand rests on employers, universities, and medical campuses, not on population growth. That distinction matters when you’re underwriting rent increases for a refinance.
The city’s population is about 2.73 million, with 2,731,585 in the latest Census estimate, keeping it the third-largest in the country. But growth has slowed sharply: about 5,300 added over the latest year versus nearly 28,000 the year before. Marcus & Millichap’s Chicago multifamily report warns that weak net in-migration and modest job gains may weigh on absorption. That is a reason not to underwrite aggressive rent growth into a cash-out.
The anchors are deep, though. Crain’s Chicago Business ranks government at the top of its largest-employers list, and Advocate Health Care is the largest health care employer on it. Other named employers include Chicago Public Schools, Northwestern Medicine, the University of Chicago, Abbott, Allstate, Boeing, and Exelon. The Near West Side medical district, home to Rush University Medical Center and University of Chicago Medicine among others, is a natural tenant pool of nurses, residents, and students.
Universities add steady renter demand. Loyola University Chicago reports 12,640 undergraduates, with its Lake Shore campus in Rogers Park, and the University of Illinois Chicago and the University of Chicago anchor other corridors. Northmarq found Rogers Park and the Loop led the market on rent growth and vacancy improvement, with combined rents up 3.7 percent year over year and vacancy improving 90 basis points, in areas where supply growth had been elevated. Lincoln Park rents rose 3.0 percent with vacancy down 30 basis points. Rogers Park absorbed new supply and still tightened, which gives a sourced reason to treat it as a demand-backed submarket, not only a Loyola story.
Tenant stickiness helps stability too. A Chicago property manager reports vacancy near 5 percent, lower in affordable workforce housing and higher in luxury Class A buildings, and Marcus & Millichap notes renewal conversion above 60 percent. Workforce-priced units tend to turn less often, which cuts turnover cost and steadies the coverage number.
What the Rent Data Does and Doesn’t Prove
Chicago rent figures vary widely by methodology, so pick one source, attribute it, and don’t mix them. RentCafe reports an average of $2,529, up 3.36 percent year over year, with two-bedrooms at $3,321 and three-bedrooms at $3,759. That skews toward larger professionally managed buildings, not a typical two-flat.
The market context is favorable. Apartments.com reports 2.9 percent rent growth for Chicago and says the Midwest leads the nation. Bisnow cites vacancy near 5 percent versus 8.5 percent nationally, with a year-end projection of 3.8 percent. Multifamily Executive reports just under 10,000 units delivered in a year, with units under construction falling from about 25,000 to 18,000. CRE Daily notes Chicago posted the biggest jump in RentCafe’s competitiveness index, at nine renters per available apartment.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Chicago, IL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Those are apartment-market figures, not two-flat figures. They support the direction, not the exact rent on your building. Use them to justify holding rents flat in a stress case, not to project increases.
Where the Equity Goes Next
The cash-out thesis depends on what the investor does with the proceeds. Pulling equity to buy another two- to four-flat in a submarket where coverage still clears, such as Pilsen, Bridgeport, Avondale, or a Rogers Park building, keeps the strategy self-reinforcing. Pulling equity to chase appreciation in a premium submarket, or to deploy where the math doesn’t pencil at current pricing, is a different decision and worth stress-testing first.
Appreciation is the tension. Option Premier, an agent blog and so directional only, reports a citywide median of $427,500, up 6.9 percent year over year, with listings down 28.9 percent. But the broader Near South Side median was about $409,857, down 2.4 percent, and West Ridge was about $334,883, up only 1.5 percent. A property bought in a flat or falling submarket may not gain the equity a refinance needs, so lean on the rent side of the ratio. Reading a neighborhood medians table as a trend would be a mistake, since small-sample medians swing widely.
Investors weighing this move can read through pulling equity out and the refinance side for the broader mechanics. DSCR loan options for Illinois investors lays out the statewide picture. When you want a file reviewed against a specific building, you can request a quote or call 828-256-2183. Verify current City of Chicago and Cook County rental rules, taxes, and insurance with qualified local professionals before sizing anything.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Chicago, Illinois?
The property has to show that its rent used for lender review covers its full monthly obligation (principal, interest, taxes, insurance, and any HOA dues), with 1.00x as the common baseline. Lenders also look at credit tier, reserves, and an appraisal that supports at most 75 percent loan-to-value. Qualification remains subject to lender guidelines and property review.
What are the requirements for a cash-out refinance on an investment property in Chicago?
Generally about six months of ownership from title recording, a credit score at or above 620 with better tiers at 660, 680, and 700, and reserves of roughly six months of PITIA. Loan amounts run up to $3,000,000 on standard programs, and smaller balances route through select lenders. Ineligible property types include manufactured homes, log homes, and barndominiums.
Do downtown Chicago condos work for a DSCR cash-out?
Often not well. Condos are frequently excluded or restricted by DSCR programs, and HOA dues reduce the coverage ratio. The downtown pipeline is also heavy, with more than half of proposed new units concentrated there, which adds rent and appraisal risk. Neighborhood two- to four-flats are the more common fit.
Will a two-flat in a flat-price neighborhood still support a meaningful cash-out?
It can, but the proceeds depend on the appraisal and the 75 percent ceiling, not on rent alone. If values in the submarket are flat or falling, the equity may not have grown since purchase. Pull current comps for your building type before assuming a size.
Can Lendmire help arrange DSCR financing for an investment property in Chicago?
Yes. Lendmire arranges DSCR investor loans, and Chicago is among them. Programs generally review eligibility on the property’s rental cash flow instead of traditional personal-income documentation, subject to lender guidelines.
The One Thing to Keep
Chicago’s two-flat cash-out works when you size the check to the building’s conservative income, not its rent roll, because the appraisal and the after-expense cash flow both answer to NOI. If you only take one thing from this piece, it’s this: in Chicago, the neighborhood flat that clears 1.00x on gross rent can still fail on appraised value, so run the cash-out against a 6 to 7 percent cap-rate value, not the asking price.
About Lendmire
A DSCR-focused mortgage broker, Lendmire (NMLS# 2371349) places investor financing across 41 markets — 40 states plus Washington, D.C. — with DSCR eligibility generally reviewed by the lender on property cash flow instead of traditional personal-income documentation, subject to lender guidelines. Scotsman Guide named Lendmire a 2025 Scotsman Guide Top Mortgage Workplace and a 2026 Scotsman Guide Top Mortgage Workplace.
Scotsman Guide’s Top Mortgage Workplace list for 2026 documents Lendmire’s recognition.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Option Premier, where Chicago buyers can find value
2. Cushman & Wakefield, Chicago multifamily MarketBeat
3. Chicago Land Lawyer, cap rates in Chicago
4. Bisnow, Chicago multifamily
6. partner-content piece in Chicago Agent Magazine
7. NBC Chicago, Census population coverage
9. Marcus & Millichap, Chicago multifamily report
10. Northmarq, Chicago multifamily report
11. chicagospropertymanagement.com — Multifamily Property Management in Chicago 2026 Guide
12. RentCafe, Chicago average rent
13. Apartments.com
15. CRE Daily
16. a 2025 Scotsman Guide Top Mortgage Workplace
17. Scotsman Guide 2026 Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Chicago, IL · Investment Property Cash-Out Refinance in Illinois
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.