
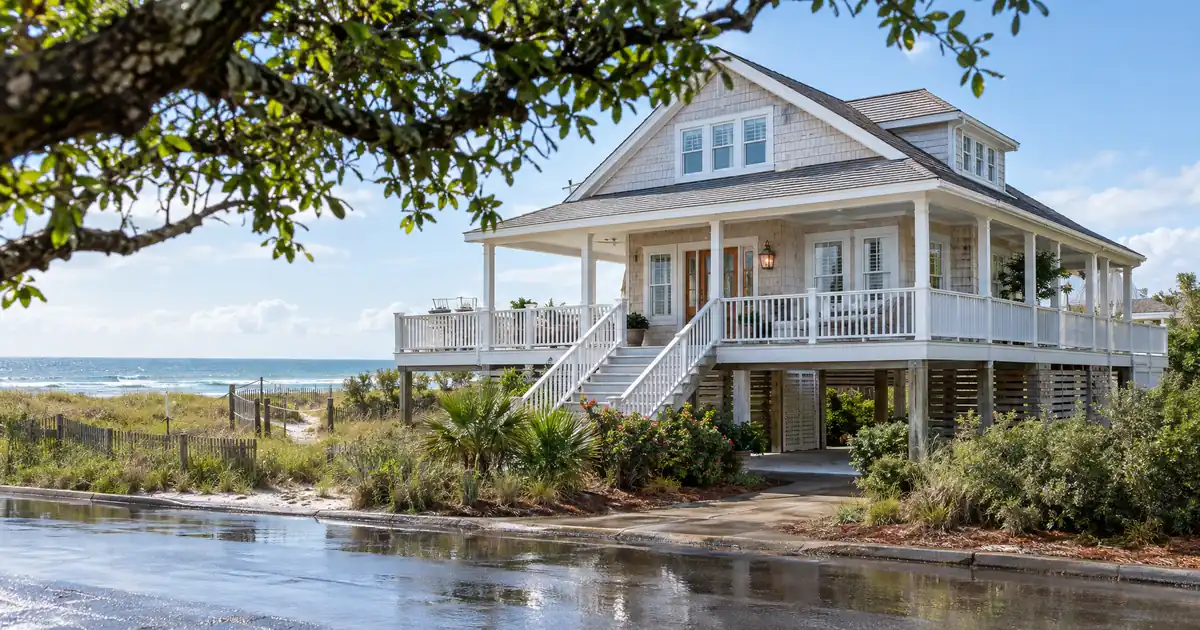
The Quick Read: Usually no. A flood zone does not by itself block a short-term rental DSCR loan. It adds a required flood policy, and that premium joins the monthly payment the rent must cover. The loan fails when the coverage ratio drops below the program floor, or when the property cannot be insured to the lender’s standard.
- A mapped high-risk zone usually means flood coverage is required, whoever the lender is.
- The premium goes into the payment side of the ratio, never the income side.
- The same rent against a bigger payment gives a lower ratio. The property did not change.
- Thin deals fail on the ratio first, not on the zone itself.
- Get the real flood quote before you bid, then run the ratio with and without it.
Key Terms Defined
DSCR (debt service coverage ratio) is the property’s rental income divided by its monthly payment. A result of 1.00 means rent equals the payment.
PITIA is principal, interest, taxes, insurance, and association dues. It is the payment the rent has to cover.
Special Flood Hazard Area (SFHA) is any area mapped as an A or V zone on a federal flood map. These are the high-risk zones.
Flood determination is a formal check that tells the lender whether the building sits in a SFHA.
Premium means three different things in this market. Here it means the insurance premium, the yearly cost of a flood policy. It is not a pricing premium on a loan, and it is not a market premium on coastal property.
Short-Term Rental Calculator
Run the STR numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 15, 2026
Prefilled with starting assumptions — enter your nightly rate, occupancy, taxes, and insurance for a more accurate picture.
Short-term rental income is documented with a 12-month history or a market data report. Program parameters update from Lendmire’s centralized guideline source.
As of Oct 15, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Nightly rate, occupancy, taxes, and insurance are editable estimates. Qualifying income for short-term rentals varies by program — some use appraisal market rent, others use documented STR history or projections — and is confirmed in underwriting. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Is the Zone or the Premium the Real Problem?
The zone and the premium are two separate checks. The zone decides whether flood coverage is required. The premium decides how much that coverage hurts the ratio. A property can sit in a high-risk zone with a modest premium. A property in a lower-risk zone can carry an expensive one.
| Situation | Is flood coverage typically required? | Effect on the ratio |
|---|---|---|
| A or V zone (high-risk) | Yes, in nearly every case | Premium added to the payment |
| Zone X, B, C, or D | Not by federal rule, but a lender may ask | Depends on the building’s own quote |
| Community outside the national flood program | Federal rule does not apply, but a lender may require private coverage | Private quote added to the payment |
| Remapped into a high-risk zone after closing | Requirement can switch on mid-loan | Payment rises; ratio thins |
Insurers now price flood by the individual building. Distance to water, first-floor height, foundation type, and rebuilding cost drive the quote, according to a Congressional Research Service overview of flood insurance pricing. So the zone letter tells you whether coverage is required. It does not tell you what the coverage costs.
That is why two cabins on the same lake can produce very different files. The zone is a yes-or-no gate. The premium is a number you can only get by asking for a quote.
Does a DSCR Lender Require Flood Insurance?
Yes, in practice. Congress requires flood insurance on buildings in a high-risk zone when the loan comes from a federally regulated lender. The interagency Federal Register Q&A on flood hazard loans says the rule applies when any part of a building sits in the high-risk area. It is triggered when a designated loan is made, increased, extended, or renewed.
Most DSCR loans do not come from those regulated lenders. They come from investor channels, so the federal rule may not apply directly. The investors who buy or fund the loans set their own flood rules, and those rules almost always mirror the federal one. Across our wholesale network, a high-risk zone means a flood policy, full stop.
Outside the high-risk zones, a lender can still ask for coverage. The Federal Register guidance also notes that the federal mandate does not apply where national flood coverage is unavailable. Even there, a lender may require private flood coverage. In practice, expect a flood requirement in mapped high-risk zones and be ready for a request elsewhere.
A word on the myth that DSCR loans are not federally backed, so flood coverage is optional. The statute targets regulated lenders, but the loan terms usually carry the same demand. Treat the requirement as real.
How Does the Premium Reach the Ratio?
The yearly flood premium is divided by 12 and added to PITIA. Flood sits in the denominator, the payment side. It does not reduce income. Wind and hazard premiums on coastal properties sit in the same denominator, so the three stack.
The income side matters just as much. For short-term rentals, the rent figure usually comes from an appraiser’s rent schedule or a third-party income report. Appraisers use Form 1007 for single-family homes and Form 1025 for 2-4 units. Projected revenue is often discounted before it enters the ratio, because bookings swing by season.
Run the numbers this way, using modeled ratios rather than market data:
- A short-term rental clears roughly 1.25x before any flood cost.
- Add the flood policy to the payment, and the ratio slides to about 1.10x.
- Add a wind premium on top, and it lands near 1.02x.
- One renewal increase later, it sits below 1.00x.
Nothing about the rent or the property changed in that sequence. Only the denominator grew. If the program floor is 1.00, the deal still clears at the second and third steps, but with almost no cushion left.
One more point on what the ratio does not measure. Clearing 1.00 is not the same as positive cash flow. Repairs, vacancy, management, utilities, and capital expenses sit outside the calculation. Flood coverage also costs you in ways the ratio ignores, as the edge cases below show.
What Do STR Programs Look Like in the Network?
Short-term rental files carry tighter terms than long-term rental files. Across the programs we place files with, the typical ranges look like this, subject to lender guidelines:
- Purchase leverage: up to 75% LTV on a short-term rental purchase, on the strongest files.
- Refinance and cash-out: up to 70% LTV on short-term rental collateral.
- Credit: a 640 minimum score is typical.
- Coverage: purchase files start at 1.00, and refinance files also start at 1.00.
- Experience: about 12 months of hosting history is usually expected.
- Loan size: up to $3,000,000 on standard programs.
Reserves vary by lender, leverage, loan size, and transaction type. Around 6 months of PITIA is common. Because the flood premium sits inside PITIA, it raises the reserve target along with the payment.
Two notes on the floor. A coverage floor of 1.00 is where select programs start, and it is not a universal rule. A separate path through select lenders takes coverage below 1.00, with leverage and terms adjusted. Eligibility turns on credit, reserves, and property review, not the ratio alone. The complete DSCR loans guide walks through these tiers in more detail.
Local rules also touch the income side. Short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income. Lendmire’s piece Can an HOA Rental Cap Block a Short-Term Rental DSCR Loan? covers that separate hurdle.
When Does It Block, and When Does It Reshape?
The flood issue blocks a loan in a narrow set of cases. Most of the time it reshapes the file. This table sorts the usual outcomes.
| Scenario | Likely outcome | What to do |
|---|---|---|
| Ratio clears the floor with flood included | Proceeds | Stress-test the renewal |
| Ratio clears only without flood | Reprices or reduces leverage | Re-quote, or lower the loan size |
| Ratio sits below 1.00 with flood | Needs a sub-1.00 path through select lenders, with leverage and terms adjusted | Bring more equity and stronger reserves |
| Property cannot be insured to the lender’s standard | Can decline | Look for private flood coverage or walk away |
| Property type is not offered | Declines | Pick a different property |
The last row deserves a plain statement. Manufactured homes, log homes, and barndominiums are not offered in these DSCR programs, in a flood zone or anywhere else.
A larger down payment lowers the payment and can lift the ratio. It never erases leverage caps, credit floors, reserve rules, or property eligibility. The strongest files clear both tests: enough equity and enough rental coverage.
The Fix-It Ladder
When flood pushes a ratio too low, the fixes are not equal. This ranked list runs from most to least effective on the ratio itself.
1. Re-quote the policy. Different carriers price the same building differently. A fresh quote costs nothing and sometimes changes the answer.
2. Get an elevation certificate. It documents the building’s actual height against the flood level and may lower the premium, as an insurance agency’s flood explainer notes.
3. Price a private flood policy. It can beat the federal program’s price, and it can offer more coverage on pricier properties.
4. Lower the loan size. A smaller balance shrinks principal and interest, which makes room for the premium.
5. Renegotiate the purchase price. A lower price does the same job as a lower balance, and the seller absorbs part of the flood cost.
6. Add reserves. This does not lift the ratio. It strengthens the file around the ratio.
7. Walk away. A deal that only works at the most optimistic quote is not a deal.
Steps one through five change the ratio. Step six changes the file’s strength. The ladder helps you tell which kind of fix you are making.
DSCR vs. conventional financing
There are two common ways to finance an investment property, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Edge Cases That Change the Math
Premiums keep climbing toward full-risk pricing. Under the current rating system, the statute allows increases of up to 18% a year on primary residences. Other property categories must rise 25% a year until they reach full-risk pricing, per the Congressional Research Service. A short-term rental is a non-primary property. So a ratio that clears today may be thinner at the next renewal.
Federal coverage has a ceiling. For one-to-four family buildings, building coverage under the national flood program caps at $250,000, with $100,000 for contents. Pricier coastal properties may need private or excess coverage to meet a lender’s requirement. The lender can generally require more than the minimum.
Lost rent is not covered by the federal program. A property manager’s explainer notes that private policies may include loss-of-rents coverage, which the federal program does not offer. A flood that closes your listing for months hurts cash flow even when the ratio passed. This is where the ratio and your real returns part ways.
Your landlord policy does not cover flood. Standard property and rental policies exclude flood. Short-term rental activity may also be excluded from ordinary dwelling forms. Flood and short-term-rental coverage are separate layers on top of the base policy.
Remapping can happen after closing. A property can be moved into a high-risk zone mid-loan, which can switch on the requirement. Model a flood policy even if the property is not in a mapped zone today.
Condos and prior claims need their own look. A condo’s master policy may or may not cover what a unit needs. A property with a flood-claim history can face tougher underwriting or a higher quote. Ask for the claims history before you commit.
Escrow changes the cash plan. Many lenders collect the flood premium monthly with the payment. When they do, the premium sits in PITIA, so it counts in the ratio. What changes is how much cash you carry at closing.
What Order Should You Check Things In Before You Make an Offer?
Run these steps in order before you bid. They take the guesswork out of whether the flood premium breaks the deal.
1. Order the flood determination. Know whether the building sits in a high-risk zone, and whether any part of it does.
2. Get real quotes. You need the flood, wind, and hazard figures, not estimates. Ask for declarations pages, not ballparks.
3. Run the ratio twice. Once with flood in the payment and once with it out, so you see the swing.
4. Check it against the program. Match the result against the 1.00 starting point, your credit, and the leverage tier.
5. Stress-test the renewal. Push the premium up and see where the ratio breaks.
6. Line up documents. Insurance declarations, hosting history, and the income report all need to be ready for lender review.
Frequently Asked Questions
Is flood insurance mandatory on a short-term rental DSCR loan?
In a mapped high-risk zone, expect it to be required. The federal rule targets regulated lenders, but the investors behind DSCR loans set the same requirement in their own terms. Outside those zones, a lender can still ask for it, so budget for the possibility.
Does the flood premium count against my rental income?
No. The premium sits in the payment side of the ratio, not the income side. It does not reduce your projected revenue. It does make the payment larger, which lowers the ratio the same way a bigger loan would.
Can a loan still work if flood pushes the ratio below the program floor?
Sometimes. Coverage below 1.00 is available through select lenders in the network, with leverage and terms adjusted. That path usually asks for more equity and stronger reserves. Approval depends on credit, the property, and lender review, so it is never automatic.
Will a lender accept a private flood policy?
That is the lender’s call under its own program. Regulated lenders must accept policies that meet the federal definition of private flood insurance, as the Federal Register guidance covers. Investor-channel lenders set their own acceptance standards, so ask before you buy the policy.
If my property is in Zone X, can I ignore flood?
Not entirely. Zone X does not trigger the federal mandate, but premiums are now building-specific. Flood losses also occur outside mapped high-risk areas. Get a real quote and decide with the numbers in hand.
Where to Go From Here
If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals. Lendmire is a mortgage broker that arranges these loans through select lenders in its wholesale network, across 41 markets, including Washington, D.C. Nothing here is a commitment to lend, and every file is reviewed individually.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income, not the borrower’s W-2 history — a practical fit for LLC-titled portfolios and self-employed investors. All scenarios remain subject to lender review and program guidelines. Two consecutive Scotsman Guide Top Mortgage Workplace recognitions (2025, 2026).
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Congress.gov CRS – Risk Rating 2.0 (IN11777)
2. Federal Register – Interagency Questions and Answers on Flood Hazard Loans
3. Policy Sherpas – Flood insurance
4. True North Managed – Flood insurance for Florida rentals
This article is part of Lendmire’s short-term rental loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Does a Coastal DSCR Rental Need Flood Insurance? · Can a Rental With a Rent-to-Own Tenant Qualify for a DSCR Loan? · How to Insure a Ski Cabin Short-Term Rental for a DSCR Loan
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.