How To Plan For An Interest-only Reset On An Asset-based Second-home Loan
Plan For An Interest-Only Reset On An Asset-Based — An interest-only period on a second-home loan always ends on a fixed date built

 Lendmire Research
Plan For An Interest-Only Reset On An Asset-Based — An interest-only period on a second-home loan always ends on a fixed date built
The reserve number does not grow with loan size the way leverage shrinks with loan size.
The trust or entity structure a family office chooses before applying often matters more than the deposit math itself.
That overlap is the whole game. Business owners who bank through an entity often assume the cash sitting in that account is simply theirs to use.
Two separate reviews decide the file: a building screen, then a borrower screen. Miss either one and the deal stalls.
It typically applies to refinances, since a purchase has no track record yet.
One Down Year In Payout Deposits Disqualify — No.
Investors who move money around in the weeks before closing are the ones most likely to get a surprise condition at the closing table.
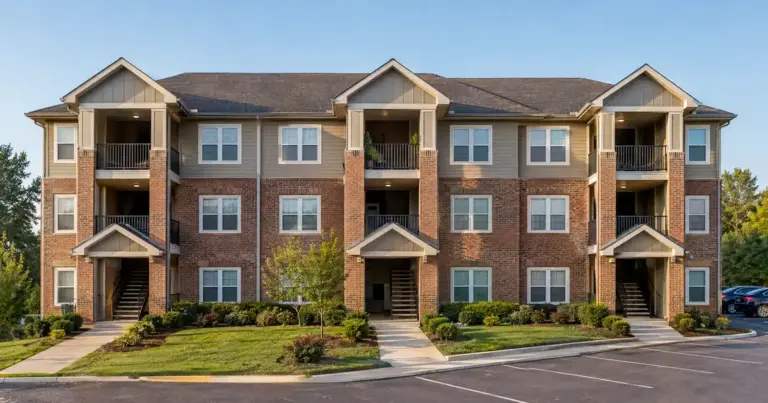
Multi-unit buildings help that math because rent is counted door by door while the mortgage payment stays tied to a single address.
Here’s the part most people miss: the building itself is often the harder problem to solve, not the borrower.
A K-1 borrower’s messy or lumpy pass-through income never has to be run through a debt-to-income ratio in this lane.
Yes. A vacant property with no signed lease can qualify for a DSCR loan, because the qualifying rent figure does not have to come from a tenant.
Can A Vacant Property Qualify For A DSCR Purchase Loan — Yes.
The fix is a documented, evidence-backed explanation paired with reserves — not a narrative letter alone.
The dashboard balance itself never counts — only the deposited, traceable cash does.