1st Lien HELOC For Investment Property
– Through this network, investment-property lines are capped at 70% CLTV and $500,000, with a 700 minimum credit score.

 Lendmire Research
– Through this network, investment-property lines are capped at 70% CLTV and $500,000, with a 700 minimum credit score.
Residential Rehab Hard Money Lenders: what investors need to know about hard money financing, from Lendmire.
Get that fork wrong at the start, and the wrong appraisal form, the wrong income concept, and the wrong lender end up on the file.
The vehicle that does this is a DSCR loan, built around the rent-to-payment math on the specific property, not a scan of the owner’s checking account.
– Bank statement HELOCs don’t come from one dominant lender — they come from three distinct provider categories, each built for a different borrower.
– Underwriting runs on credit tier, combined loan-to-value, and debt-to-income — not a personal tax-return package.
A private money investor lends money and expects a fixed return no matter how the property performs.
Which method applies depends on the loan program, your ownership stake in the business paying you, and how long you’ve been receiving 1099 income.
It just looks nothing like the HELOC on your own house.
The real friction isn’t whether the money is allowed; it’s proving where it came from and when it landed in the account.
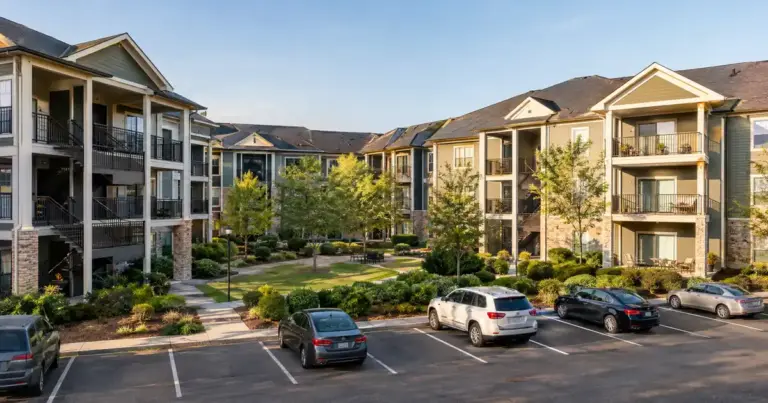
Apartment Investment Property Refinance Loans — Refinancing an apartment property splits into two different worlds depending on unit count.
It is a separate product from a DSCR loan, which is why so many investors get confused mid-project.
Renovating A Property Into An Airbnb With Hard Money — This is a two-loan play, not one.
Financing A New Construction Airbnb — Financing a new construction Airbnb almost never means one loan.