How A Bank Statement Loan Reads Retained Earnings For A Resort Home?
Their tax returns understate what they earn.

 Lendmire Research
Their tax returns understate what they earn.
Shorter fixed periods (5-year) carry smaller initial caps but reset sooner.
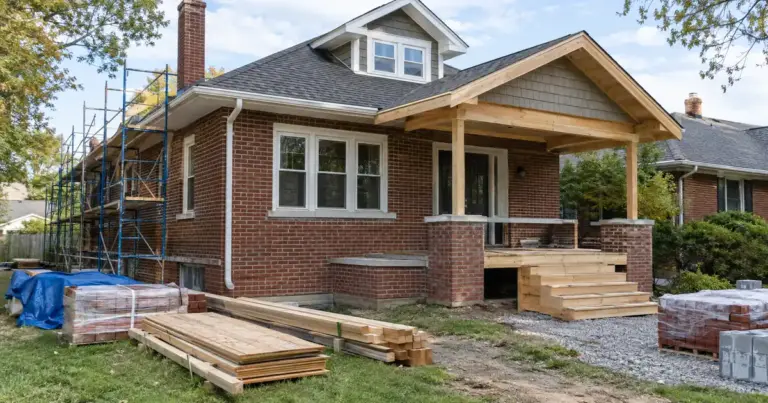
Founder Refinance A Rehab Into A DSCR Loan — Sometimes, but not automatically.
Explain Declining Income On A Super Jumbo — A drop in deposits doesn’t sink a super jumbo bank statement file by itself.
Can A Vacant Rental Qualify For A Jumbo DSCR Purchase Loan — Yes.
It has nothing to do with a DSCR rental loan, where qualifying income comes from the property’s own rent, not the borrower’s bank deposits.
How To Reconcile Two Appraisals On A Bank Statement Second Home Loan — When two appraisals disagree, the underwriter doesn’t average them.
It is not a minor edit — it is a full re-run of the income math with a new total and a new divisor.
Renting A Second Home Occasionally Void — No, occasional rental use doesn’t automatically void a bank statement loan on a second home.
Your bank statement deposits, expense ratio, and qualifying income calculate the same whether you sign as an individual or as trustee.
Above roughly $3.5 million, every file also gets a manual, case-by-case look before it goes to underwriting.
Before seasoning clears, extra cash into the deal helps the coverage math, but it never overrides a credit floor or a leverage cap.
Do Entity Transfers Count As Deposits On A Super Jumbo Loan: what borrowers need to know about high-net-worth bank-statement financing, from Lendmire.
No. A blanket STR DSCR loan does not go through a new credit decision when the interest-only period ends.
It’s a contract right, not insurance.