Does Clearing A Car Note Change A 1099 Bank Statement Loan Approval?
Clearing A Car Note Change A 1099 — Paying off a car loan can help a bank statement approval, but only on the debt side of the file.

 Lendmire Research
Clearing A Car Note Change A 1099 — Paying off a car loan can help a bank statement approval, but only on the debt side of the file.
Net payout is a bookkeeping number, not an underwriting number. A DSCR loan sizes the payment around the property’s rent, not the borrower’s paycheck.
The twist is the acreage itself: appraisers have to decide how much land actually counts toward value, and jumbo pricing steps down as the loan gets bigger.
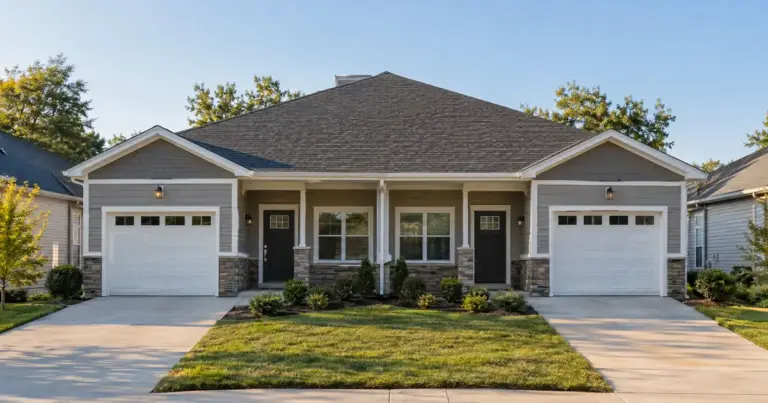
Luxury Duplex Get Single-Family Leverage On A DSCR — No, not automatically.
A below-market lease drags that number down, no matter how strong the property actually is.
Show Seasonal Rental Income As Steady DSCR Coverage — Lenders never qualify a seasonal rental off its best month.
Twenty-acre Resort Property Close on Bank Statements — No.
A super jumbo bank statement loan solves the first problem by qualifying on deposits instead of tax returns.
Presenting the wrong figure, or presenting it with no reconciliation, is the single fastest way to slow down an STR file. Here’s the disconnect.
One blended ratio decides the whole loan.
But that same annualizing can hide a property that genuinely can’t cover its payment for stretches of the year — which is the part investors miss.
The fix is usually one of a few moves: adjust leverage, wait for a lease renewal, or restructure the loan around the number the lease actually supports.
Twenty-Acre Property Qualify For A Super Jumbo — Usually not as a single twenty-acre collateral parcel.
The below-market lease does not disqualify the deal — it sets a lower qualifying rent number, which can reduce leverage or loan size at jumbo balances.
Does An Off-season Month Break A Jumbo DSCR Rental Loan Coverage Test: what investors need to know about large-balance DSCR financing, from Lendmire.