Apartment Investment Property Refinance Loan Finance
Apartment Investment Property Refinance Loan Finance — Unit count decides everything before a lender even looks at the numbers.

 Lendmire Research
Apartment Investment Property Refinance Loan Finance — Unit count decides everything before a lender even looks at the numbers.
The mechanics look very different depending on where you’re bidding, though.
Non-QM lenders often replace that with bank deposits and an expense factor instead of a tax return.
Investors holding property in an entity typically need a different structure altogether.
Property titled inside an LLC compounds the problem, since a personal HELOC generally requires title in an individual’s name or a revocable living trust.
Lenders classify it as business-purpose credit, cap leverage lower, and want a stronger credit file before they’ll even open the underwriting review.
The real workaround is buying with cash first, then refinancing into hard money once the deed records.
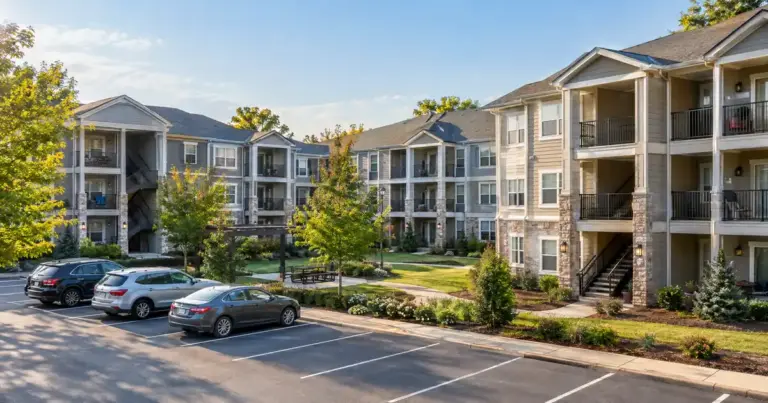
Getting the classification right up front determines the appraisal form, the documentation, and the leverage ceiling for everything downstream.
Title matters as much as income: these lines close to individuals or revocable living trusts, never LLCs.
Understanding both sides of the math — the traditional method and the DSCR alternative — is how you pick the right path for your next deal.
Key takeaways: – HELOC denial rates run far above closed-end mortgage denial rates nationally, and self-employed applicants sit at the center of that gap.
Credit minimums, reserve requirements, and available leverage all shift by lender, property type, and the investor’s track record.
A HELOC underwriter reviews your credit and your home’s value — not whether the dealership survives its first five years.
These are non-QM loans, which means the underwriting path is different from a conventional mortgage, not less regulated.
A home equity loan hands you a lump sum with a set repayment schedule from day one.