DSCR Loan For Renters Explained
Most standard DSCR programs still assume the borrower already owns a primary residence somewhere.

 Lendmire Research
Most standard DSCR programs still assume the borrower already owns a primary residence somewhere.
Most investor loans qualify the deal on the property’s rent, not on your home address.
Can I Buy An Investment Property If I Rent — Yes. Renting your own home has no bearing on your ability to buy an investment property.
Can A Renter Buy An Investment Property — Yes — renting your own home doesn’t stop you from buying an investment property.
DSCR Loan Without Homeownership — No federal rule says a borrower has to own a home before qualifying for a DSCR loan.
The answer is your coverage ratio. Your personal paycheck is not the numerator.
Which one fits depends on how your documented income looks on paper versus how the property actually performs.
The buy-and-rehab phase runs on hard money or bridge financing either way, homeowner or not.
– Cash-out refinances on investment property generally cap around 75% loan-to-value across the non-QM network — a hard ceiling, not a target.
It rarely changes whether your loan qualifies, since DSCR loans are underwritten against the property’s rent, not who happens to be collecting it.
The strategy hinges on the market’s rent-to-price math holding up under real operating costs — not on where the buyer happens to sit.
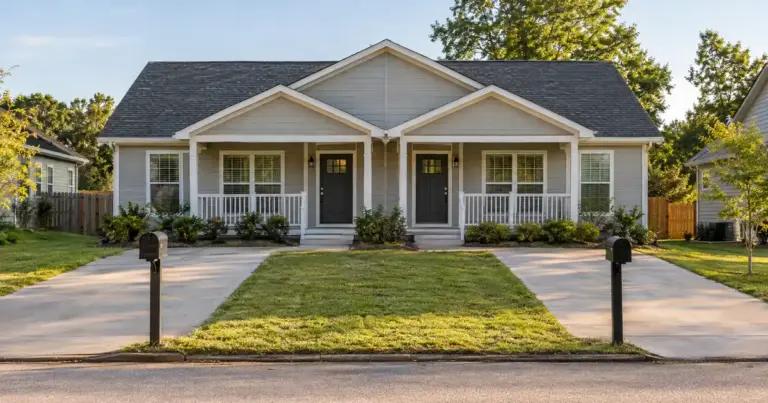
Buying a Duplex as Your First Investment Without Living in It — You can buy a duplex, rent both sides, and never live there.
DSCR loans qualify on the property’s rental income, not on where you personally live, so the two housing situations never touch each other on paper.
Every legitimate deduction your CPA recommended lowers your tax bill and lowers your qualifying income at the same time.
A bank statement loan exists for one reason: self-employed income doesn’t always show up on a tax return the way it shows up in a checking account.