Short Term Rental Loan Options For Self Employed Investors
– DSCR loans qualify self-employed short-term rental investors on the property’s rental income, not personal tax returns.

 Lendmire Research
– DSCR loans qualify self-employed short-term rental investors on the property’s rental income, not personal tax returns.
The catch is documentation: furnished monthly income needs to be supported the way a lender expects, not just advertised on a listing site.
None of these systems talk to each other, so clearing one doesn’t clear the others.
Converting A Long Term Rental To An Airbnb — Turning an existing rental into a nightly-stay property is a lot more than a listing decision.
It’s also more workable than most first-time mountain investors assume, once they know which piece of the file actually decides the deal.
Most investors use a DSCR loan — a mortgage that qualifies the property on its rental income instead of the borrower’s pay stubs or tax returns.
Which path a file takes changes what income a lender is allowed to count toward the loan — and that can swing a property’s coverage ratio by a wide margin.
That’s the mechanism that lets a host keep adding doors without hitting a debt-to-income wall.
Vacation Rental Property Loans — A vacation rental property loan is typically a DSCR (debt-service coverage ratio) loan that qualifies
The decision comes down to portfolio size, risk tolerance, and whether the ongoing compliance cost is worth the protection.
This guide walks through the mechanics, the structures, and the specific edge cases where the general rule doesn’t hold.
A conventional mortgage refinance is built around a fixed lease or owner-occupancy — neither of which describes a nightly-rate rental.
That mismatch is why non-QM, income-based financing — commonly called a DSCR loan — exists as a separate lane for short-term rental buyers.
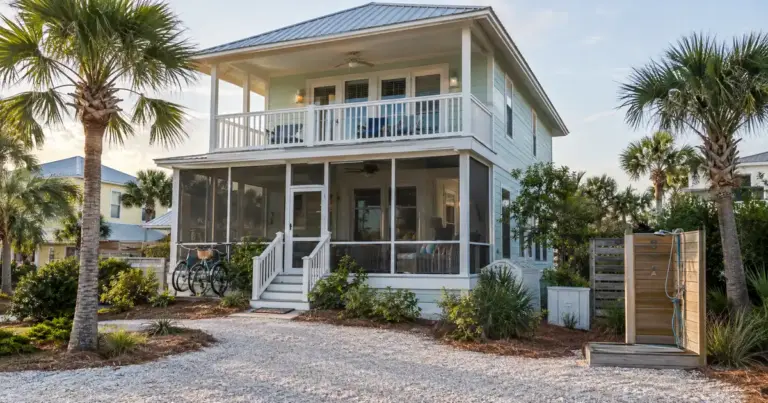
Airbnb Loan Options Explained Airbnb Loan Options Explained — An “Airbnb loan” isn’t a separate loan category.