
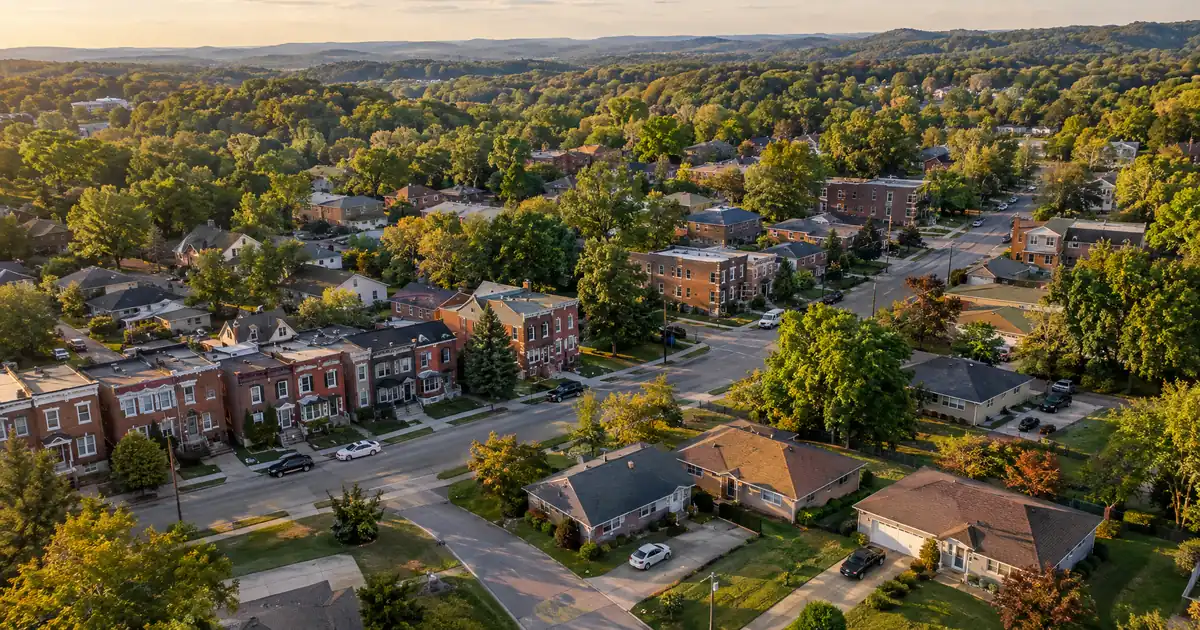
Grover is where Wildwood’s rental math is easiest to read. Zumper puts the average rent there near $2,100 a month, below Glencoe at $2,350, in a city where sale prices are high relative to the rents those homes command, so rent-to-price ratios look thinner than what investors typically see in the urban core. An owner in Grover, or anywhere in Wildwood’s large-lot housing stock, is usually sitting on meaningful equity and thin rental coverage at the same time. That tension defines every cash-out conversation in this market.
The Quick Read: A DSCR cash-out refinance in Wildwood, Missouri is underwritten primarily on the property’s rental income measured against its full monthly obligation, which makes Wildwood’s high prices and modest rent-to-value ratio the central variable in how much equity can be pulled.
DSCR Cash-Out Calculator
Run the cash-out numbers in Wildwood, MO
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Listing data shows 3-bedroom houses renting near $2,980 per Homes.com.
- Cash-out LTV tops out at 75%, and proceeds depend on rent used for lender review.
- Roughly 6 months of ownership seasoning is the typical benchmark.
- A 188-unit Town Center community adds new rental competition.
- Duplex and small multifamily stock is scarce, so unit-stacking is rare.
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker arranging investor loans across 40 states plus Washington, D.C. This article covers one narrow question: how an investor who already owns a Wildwood rental extracts equity, and whether the coverage ratio cooperates. Purchase mechanics are a separate topic.
Why the Coverage Math Is the Hard Part Here
Wildwood is a high-value, low-density, owner-occupied suburb, and that profile compresses rent-to-value. Median sale price depends on the source: Redfin reported about $528K with a 7.9% year-over-year decline, Movoto reported $700,000 for April, and Data USA puts median property value at $495,800. Call it $500K to $700K depending on whether you read sold, listed, or assessed figures.
Against that, a 3-bedroom house at roughly $2,980 a month implies a monthly rent-to-value near 0.56% on the $528K reference point. That is a modeled figure, not a sourced one. DSCR is monthly rent divided by the full monthly obligation: principal, interest, taxes, insurance, and any HOA dues. Run a single-family rental at that ratio with taxes and insurance included, and coverage lands below 1.00x at high leverage. Not close, at 75% LTV on a value near $528K. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Here is the catch. The standard benchmark is 1.00x because rent covers the obligation at that level. Some lenders review sub-1.00 files, but those typically require lower leverage, stronger credit, deeper reserves, or different pricing. Eligibility depends on lender guidelines, credit profile, reserves, and property review.
So the practical question for a Wildwood owner is not “how much can I pull?” but “at what LTV does the file clear?” In most single-family scenarios here, the answer is a leverage level well below the 75% ceiling.
Rent Bands: Underwrite the Middle, Not the Top
Rent sources disagree, and the gap matters because the rent figure is the numerator of the whole calculation.
| Source | Reading | Note |
|---|---|---|
| Homes.com | 3BR $2,980; 4BR $3,800 | Small listing sample |
| Zumper | Average house $2,522 | Flags limited data |
| Zillow ZORI (via aggregator) | About $2,786 | Index-style |
| Zumper | Average overall $2,300 | Down 4% YoY |
An underwriting range of roughly $2,500 to $3,000 for a typical house is defensible. The $3,800 four-bedroom quote is a ceiling, not a base case. An appraiser’s rent schedule and the lender’s own review set the rent used for lender review, and Zillow-style indexes or listing averages do not. Investors who size the cash-out off the top of the range will be disappointed at the appraisal stage.
Metro context helps calibrate direction. Multi-Housing News cites Yardi Matrix data showing St. Louis asking rents up 2.1% year over year to $1,312 through August, a modest pace. Wildwood’s rents are well above the metro average, which is exactly why the rent-to-price ratio, not the rent level, is the constraint.
Equity Extraction When Appreciation Isn’t Doing the Work
Price signals in Wildwood are noisy, and that shapes how much cash-out an appraisal will support.
Redfin’s city page showed $528K, down 7.9%. Its Ballwin-area Wildwood neighborhood page showed a $400K median, down 24.5%, though that is a small monthly sample and likely reflects sales mix. Movoto reported a $700,000 median in April, with homes taking 22 days to sell against 12 a year earlier, and 142 sales against 120. Homes.com put the June median near $729,000.
Read together: demand is real, since sales volume rose, but pricing power has softened and negotiation is increasing. The appraiser’s comp set may land well below a listing-based value. A refinance thesis that depends on further appreciation to lift the value is fragile here.
The safer framework for an owner considering cash-out:
- Size off a conservative value. Assume the appraisal lands near the lower end of the reported range, not the listing median.
- Treat 75% as a ceiling, not a target. The typical Wildwood file likely needs lower leverage to clear coverage.
- Plan for about 6 months of ownership seasoning, measured from title recording, and about 6 months of reserves on most files (more above $1,500,000).
- Credit tiers run from 620 upward, with stronger scores generally supporting better leverage, subject to lender guidelines.
Loan amounts run up to $3,000,000 on standard programs, which covers most of Wildwood’s price range comfortably. Equity available is never a guaranteed figure. It depends on rent used for lender review, the full obligation, reserves, and the LTV ceiling. The cash-out refinance mechanics cover how proceeds are calculated, and the rate-and-term versus cash-out refinance details are worth reading for owners weighing a lower-leverage reset instead.
What a Typical File Looks Like in Markets Like This
DSCR files in high-value, low-density suburbs like Wildwood typically look the same way: strong borrower profiles, meaningful equity, and a coverage number that is the binding constraint rather than credit or reserves. The equity is there, but the rent does not scale with the price. Files that work tend to be structured around a lower cash-out LTV, or around a property whose rent is unusually strong for its basis. Brokers placing these files often run two or three leverage scenarios side by side before choosing which to submit, because the gap between 65% and 75% LTV can be the difference between a file that clears and one that doesn’t.
The Multi-Unit Question
Wildwood is, in NeighborhoodScout’s words, “a city of large, single-family homes”. True duplex, triplex, and fourplex stock is thin. City-Data, drawing on Census figures, shows 2024 mean values of $222,556 for 2-unit structures, $208,634 for 3-to-4 unit structures, and $250,860 for 5+ unit structures. Those are means of a very small stock, directional at best.
Consider the illustration, modeled rather than sourced. Listing-based duplex rents run about $1,198 to $1,619 per unit per Apartments.com. Two units gross roughly $2,400 to $3,200, comparable to one 3-to-4 bedroom house at $2,980 to $3,800. If the duplex basis is meaningfully below the single-family price, coverage improves materially. That is the entire argument for unit-stacking: similar rent, lower value, better ratio.
The thinking-out-loud version: this is a genuine trade-off. A duplex owner gets better coverage and possibly a larger cash-out at the same LTV, but carries two tenant relationships and double the vacancy exposure. An owner of a single large house has cleaner operations and worse math. Neither is wrong. The right answer depends on what the proceeds are for.
Town Center: New Supply Changes the Next 18 Months
Town Center, at Main Street and Taylor Road, is Wildwood’s mixed-use core, and it’s about to get heavier. Wildwood Luxury Living is a 188-unit, $57.5M community with completion expected by summer 2027, though one architecture-firm release describes it as roughly 190 units.
This is Class A supply landing in a submarket where small-investor rentals compete for the same tenants. Concessions during lease-up are a realistic possibility, and Zumper’s apartment-side data shows sharp rent declines on thin listings, which should be read as noise but also as a caution. Owners near Town Center should underwrite vacancy and rent assumptions with that supply in mind, and a cash-out taken before lease-up completes locks in a value based on pre-supply rents.
The indicators worth tracking over the next 6 to 24 months:
1. Asking rents and concessions at the new community as it leases up. 2. Days on market for Wildwood single-family sales, which Movoto shows rising from 12 to 22. 3. Whether Redfin’s and Movoto’s median readings converge, which would signal a stabilizing comp set. 4. Any meaningful change in the sales-volume trend.
Demand Base: Who Rents Here
The tenant profile is professional and commuter-driven. Census Reporter puts the population at 35,133, and Data USA lists the largest resident industries as Professional, Scientific and Technical Services (2,244 workers), Finance and Insurance (2,069), and Health Care and Social Assistance (1,989). City-Data shows a daytime population change of -23.1%, which confirms that Wildwood is a bedroom community. Residents commute into the broader St. Louis region for work.
The city itself covers 68 square miles, including 11 square miles of parks, per the City of Wildwood, and it is the third-largest Missouri city by area. The recreation identity, trails, the region’s only snow ski facility, and Meramec River access, supports a workforce-plus-lifestyle renter. Whether that translates into reliable mid-term rental demand is unverified, so the conservative assumption is standard long-term leases.
One gap to state plainly: no verified employer headcounts, hospital data, or vacancy rates were available for Wildwood. The city’s Top Employers page exists but is sourced to older business-license data. Any underwriting should lean on rent and price evidence, not on an employer story the data can’t support.
Submarkets as Rent Bands, Not Price Pairs
Zumper’s neighborhood labels are loose, and its data is thin, so treat them as bands only. Grover, described as Wildwood’s most sought-after neighborhood, averages about $2,100. Glencoe sits near $2,350. Pacific at $1,450 is technically a separate city. Apartment communities like Ashton Woods and Enclaves at Cherry Hills are corporate-owned product and aren’t comparable to small-investor stock. The Clayton Road corridor surfaced only as a lead.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Wildwood, MO, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
No reliable neighborhood-level price table exists, so pairing these rents with submarket prices would be invented precision. The defensible use: Grover and Glencoe rents frame the lower and middle of the house-rent range, and the real work is a live comp pull on the specific property.
Structuring the Cash-Out
Lendmire arranges DSCR investor loans through wholesale lending channels, and lenders review eligibility and approve. Lendmire’s role is placing the file in the right program. Lendmire’s Missouri DSCR loan programs cover the state-level structure, and the DSCR qualification mechanics explain the ratio itself. For owners comparing paths, the contrast between conventional and DSCR investor loans is the relevant one: conventional underwriting leans on personal income and financed-property counts, while DSCR reviews rental income at the property.
Non-QM DSCR financing as a category can offer more structuring flexibility than conventional channels, including options for LLC-owned portfolios, subject to lender program eligibility. Review details remain subject to lender overlays, and the program ranges above reflect select wholesale-network guidance, not commitments. Properties like manufactured homes, log homes, and barndominiums fall outside these programs.
Investors who want to see how a specific Wildwood property runs can reach the brokerage at 828-256-2183 or use the quote request form. Verify current local rental rules, taxes, and insurance with qualified local professionals before committing.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance on a Wildwood rental?
Qualification centers on the property’s rent relative to its full monthly obligation, with a 1.00x benchmark common on most programs. Pricing and available terms vary by lender, borrower profile, property type, and full underwriting review. Everything remains subject to lender guidelines, credit approval, and property review.
What are the requirements for an investment property loan in Wildwood, Missouri?
Expect a cash-out LTV ceiling of 75%, a minimum coverage ratio around 1.00x, and a minimum credit score near 620. Loan amounts run up to $3,000,000 on standard programs. Ineligible property types include manufactured homes, log homes, and barndominiums.
Why is cash-out harder on Wildwood single-family homes than on a typical Midwest rental?
Prices are high relative to rent. A 3-bedroom house renting near $2,980 against a value in the $500K-plus range produces a monthly rent-to-value near 0.56%, which pushes coverage toward or below 1.00x at higher leverage. Lower LTV or multi-unit stacking are the usual fixes.
Will the new Town Center apartments affect my refinance?
Indirectly, yes. The 188-unit community, due by summer 2027, adds Class A supply that may pressure rents and raise vacancy assumptions for nearby small rentals. An appraiser’s rent schedule may reflect that, so sizing the loan conservatively makes sense.
Can Lendmire help structure a DSCR cash-out refinance scenario for a Wildwood rental property?
Yes. Lendmire arranges DSCR investor loans and places cash-out files up to a 75% LTV ceiling, subject to lender guidelines and credit approval.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire — NMLS# 2371349 — is a DSCR and non-QM mortgage brokerage with investor loan programs in 41 markets, including Washington, D.C. Lenders commonly review DSCR eligibility around property-level rent rather than personal income documentation, subject to lender guidelines, and the brokerage helps arrange financing for LLC-owned portfolios beyond conventional financed-property limits. Lendmire was recognized by Scotsman Guide as a 2026 Top Workplace and as a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zumper — Rent Research Wildwood MO
2. Homes.com
3. Redfin, Wildwood housing market
6. NeighborhoodScout — Wildwood Real Estate
9. 35,133
10. City of Wildwood, Economic Development
11. recognized by Scotsman Guide as a 2026 Top Workplace
12. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Missouri
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.