How A Family Trust Finances A Fourplex With A Super Jumbo DSCR Loan?
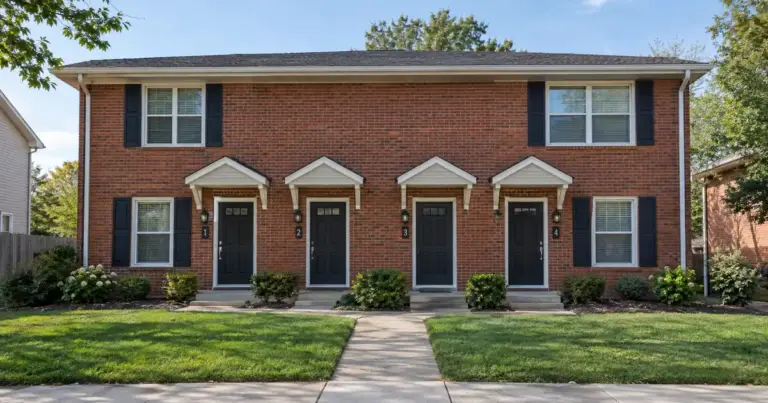
The lender underwrites the trust instrument and the trustee’s authority, not the settlor’s income.

The lender underwrites the trust instrument and the trustee’s authority, not the settlor’s income.
How LLC Portfolios Are Read On A Luxury STR DSCR Loan’s First Year — A lender looks at the property and the guarantor, not the LLC’s résumé.
Irrevocable trusts add real friction, and the vacation-rental income itself gets documented on its own track, separate from the trust question entirely.
Nothing has to be liquidated to satisfy that requirement. That distinction matters more than it sounds.
LTV, credit, and reserves are evaluated as separate gates from the rental-income test.
How Seasonality And Reserves Are Weighed On A Short-term Rental DSCR Loan — Lenders don’t qualify a seasonal rental off its best month.
The property’s rental income — not a family member’s tax return — carries the loan, subject to lender guidelines.
A condotel’s warrantability affects a super jumbo DSCR loan by capping how much you can borrow, not whether you can borrow at all.
How Seasonal Rent Data Drives A Luxury STR DSCR Loan — Lenders don’t qualify a seasonal short-term rental off its best month.
That classification pulls the loan out of the consumer-mortgage box entirely, which is exactly why property-income-based DSCR loans exist.
What Experienced Operators Check Before A Beach House DSCR Loan — They check the flood zone before they check the price.
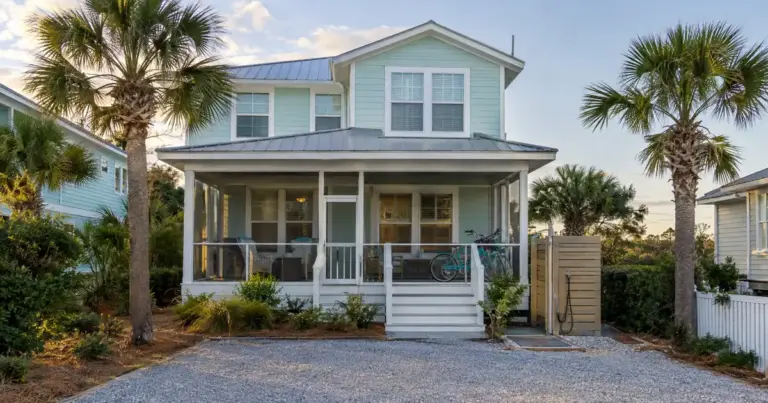
A DSCR loan then qualifies the file using the property’s rental income instead of the owner’s pay stubs, subject to lender guidelines.
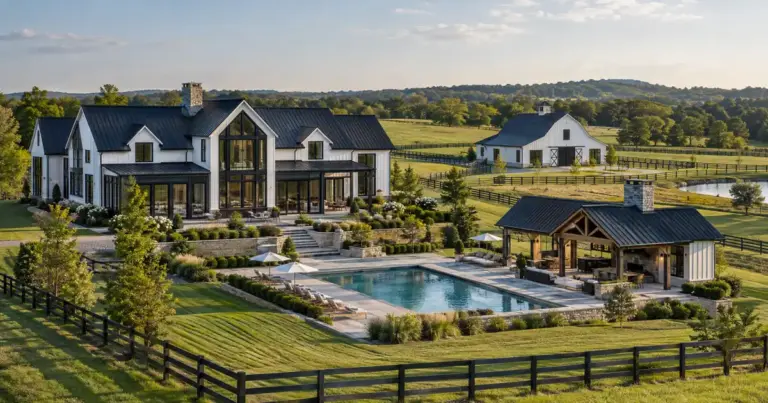
That distinction trips up a lot of buyers. They assume “approved” means done.
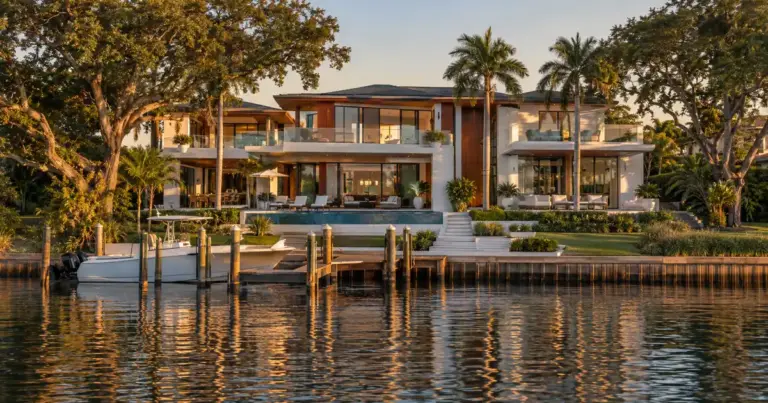
What actually changes is the income calculation. Long-term rentals get a monthly rent figure straight off an appraisal form built for leases.