How A DSCR Lender Reads Rent On A Recently Converted Rental Property?
If a lease exists, underwriting typically uses the lower of the lease and the appraised market rent.

If a lease exists, underwriting typically uses the lower of the lease and the appraised market rent.
Several Short-term Rentals Sit on One Blanket DSCR Loan — Yes.
Qualification runs on the property’s rent, the guarantor’s personal credit, and clean formation paperwork — not the age of the LLC.
Does A Rehabbed Rental Need Seasoning Before A DSCR Refinance — Yes, in almost every case.
They apply a discount — commonly 20% off the gross figure, so only about 80 cents of every projected revenue dollar counts toward qualifying income.
Founder Use DSCR Cash-out to Buy the Next Rental — Yes.
That $400,000 designer furniture package in your luxury short-term rental never touches the appraised value used to size the loan.
Estimate Qualifying Rent From A Resort Rental’s Booking Revenue — Lenders never use your gross booking-platform revenue as qualifying rent.
No, a ski cabin’s best month cannot set the qualifying income on a DSCR loan.
Does A First-time Investor Qualify For The Same DSCR Rental Loan Terms — Mostly, yes.
Whichever number is lower becomes the income used to calculate the coverage ratio.
A DSCR lender reads first-year income on a luxury rental by using the lower of two numbers: the appraiser’s market-rent opinion or an actual signed lease.
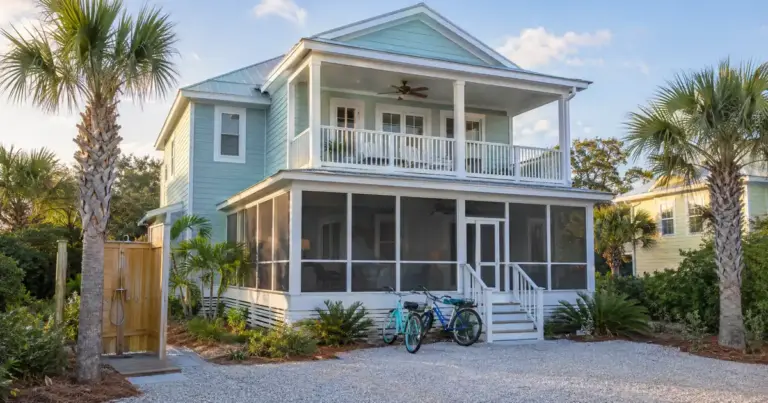
First-Time Rental Owner Get A Short-Term Rental — Mostly yes, but not always through the short-term rental income path itself.
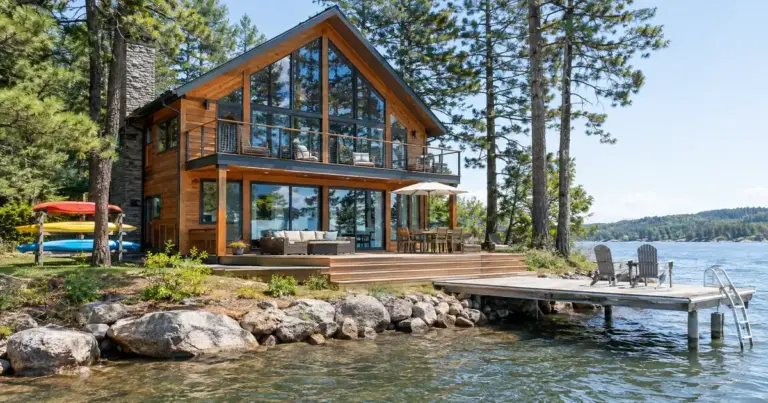
How A DSCR Lender Averages A Lake House’s Seasonal Rental Income — A lender doesn’t use your best month.