Best Hard Money Lenders For Beginners
The real skill isn’t finding a lender — it’s understanding how the underwriting works well enough to vet any lender against it.

The real skill isn’t finding a lender — it’s understanding how the underwriting works well enough to vet any lender against it.
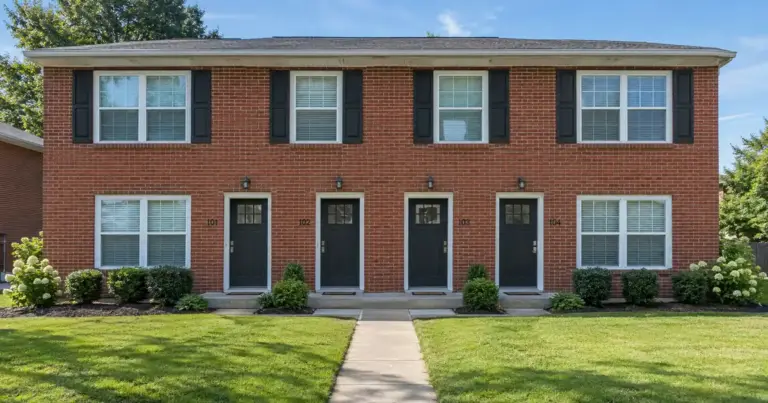
– 2-4 unit properties use a different appraisal form than single-family rentals — one that combines valuation and rental income into a single report.
It’s a real, select-lender path, not a marketing term, and it exists alongside standard DSCR programs that still require rent to cover the payment.
The underwriting math just adds HOA or condo association dues to the usual payment stack before comparing it against rent.
– A 2-4 unit DSCR loan uses one blended payment (PITIA) against combined rent from every unit in the building — not a separate loan per unit.
The tradeoff shows up in two places: the DSCR math on the new payment, and any prepayment penalty still ticking on the old loan.
Terms typically run 6 to 18 months, credit floors start around 620, and the strongest leverage goes to investors with a track record of finished projects.
Investors who understand which tier applies to their deal walk into underwriting with realistic expectations instead of guesses.
– Hard money underwriting starts with the property and the plan, not the paycheck.
The property’s rent doesn’t drive approval on this particular product — the borrower’s own credit and income do.
Get those three differences straight and the rest of the product makes sense fast.
Small capital doesn’t disqualify you, but it does put you in a lower leverage tier until you build a track record. The real barrier isn’t the paperwork.
Guide To Finding Private Money For Real Estate Deals: what investors need to know about hard money financing, from Lendmire.
It’s used to buy, rehab, or bridge a property that isn’t stabilized enough for a bank or long-term rental loan yet.
First-time investors usually land in the lower leverage tiers rather than getting shut out entirely.