What Is A Condotel Loan? How Lenders Underwrite Resort Units
Standard mortgage financing won’t touch these units, so the entire condotel market runs through non-QM and DSCR-style investor lending instead.

Short-Term Rentals articles from Lendmire: how-to guides, requirements and eligibility checklists, cost and timeline questions, and side-by-side comparisons for borrowers and investors. Start with the Short-Term Rental Loans program page or browse the Short-Term Rental Loans Guide Library.
Standard mortgage financing won’t touch these units, so the entire condotel market runs through non-QM and DSCR-style investor lending instead.
Nightly-rate income looks great on paper, but lenders don’t use the raw number.
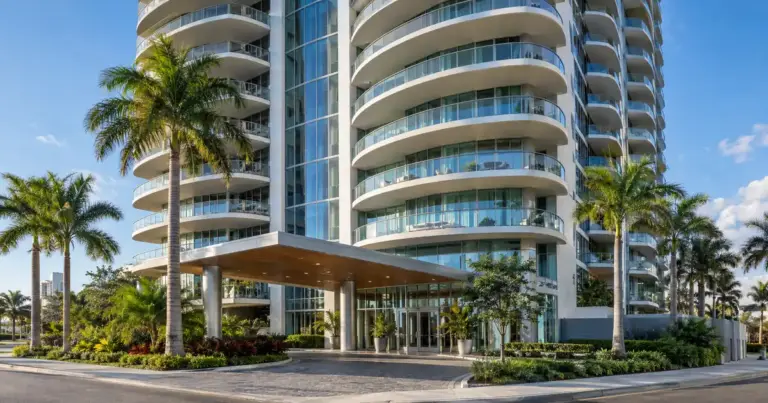
Fannie Mae and Freddie Mac won’t buy loans on buildings that operate like hotels, so those files never reach agency underwriting at all.
Existing guest reservations do not transfer to a buyer — the trailing income record does. A calendar full of future reservations feels like proof of value.
It’s the legal foundation behind most DSCR financing on short-term rentals.
Short-term rental income gets documented separately from the vesting question, usually at a discount to gross platform revenue.
No single number “guarantees” approval — the file, the property, and local rules all matter.
The property qualifies on its rent, not your paycheck.
That matters because physician mortgage programs are built for primary homes only — they won’t touch a vacation rental.
Insurance sits inside that denominator. Raise the premium and the ratio drops, even if the rent stays exactly where it was.
Coverage runs off booking history or an appraiser’s short-term-rent analysis, not a nightly rate multiplied by 30.
A lender looks at what the property earns, or is projected to earn, on Airbnb or Vrbo, and compares that number to the monthly payment.
Leverage steps down as the loan gets bigger, credit and appraisal requirements get tighter, and cash-out disappears above $3,000,000.
The lender looks at the rental property’s income, not the founder’s K-1s or capital-gains history.
Instead of pulling two years of tax returns, the lender looks at the rental’s own cash flow — bookings, appraisal-based projections, or a blend of both.