How To Co-own A Luxury Short-term Rental On A DSCR Loan
The loan qualifies on the property’s projected or documented nightly income, not the co-owners’ personal tax returns.

Short-Term Rentals articles from Lendmire: how-to guides, requirements and eligibility checklists, cost and timeline questions, and side-by-side comparisons for borrowers and investors. Start with the Short-Term Rental Loans program page or browse the Short-Term Rental Loans Guide Library.
The loan qualifies on the property’s projected or documented nightly income, not the co-owners’ personal tax returns.
In Lendmire’s network, condotels get financed up to 75% loan-to-value on a purchase and 65% on a refinance, capped at $1,500,000, subject to underwriting.
What shows up is the LLC, trust, or corporation the office uses to hold title, plus a personal guarantor standing behind it.
Does A Full Year Of Bookings Lift Leverage On A Vacation Rental Loan — No, not by itself.
– A multi-member LLC is taxed as a partnership by default under IRS rules, unless the members file Form 8832 to elect corporate treatment.
Actual payout statements almost always beat a market projection when the property has a real track record. That’s the short version.
Two tracks, two numbers, and furnishings only show up in one of them. That split trips up more borrowers than almost any other part of an STR DSCR file.
It’s financeable. It’s just not financed the same way. That’s the honest answer. Now here’s what actually happens on a file.
Keep those two things apart on paper, and the file behaves.
Reserves cover the seasonal gaps an annual average can’t show. What follows is the mechanics, the tradeoffs, and where this plan can fall apart.
Does A Year Of Bookings Raise Leverage On A Vacation Rental Refinance — No, not directly.
How A Short-Term Rental DSCR Loan Separates Furnishings From Property Value — The appraisal splits into two lanes.
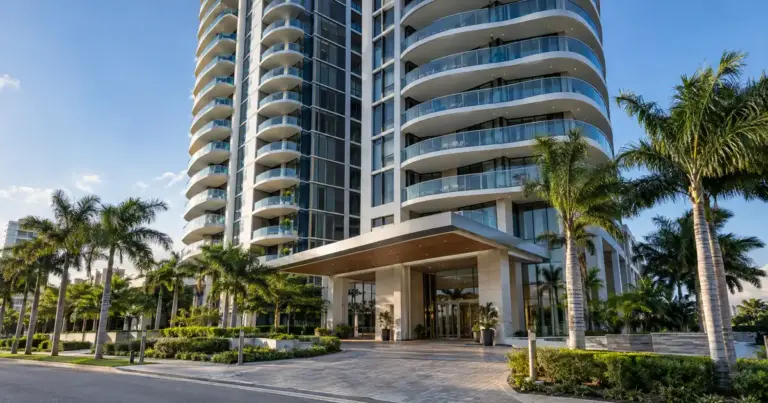
Fannie Mae and Freddie Mac exclude condo-hotels outright, so condotel buyers land in non-QM territory whether they like it or not.
Lenders want payout statements and bank deposits, not a spreadsheet the owner built.
Personal use by any guarantor can also complicate the loan’s business-purpose classification, which is a wrinkle unique to vacation properties.