Short-term Rental DSCR Loan Requirements After A Liquidity Event
Get the sourcing paperwork right early and the loan-amount conversation moves fast; get it wrong and the file stalls on a letter-of-explanation loop.

Get the sourcing paperwork right early and the loan-amount conversation moves fast; get it wrong and the file stalls on a letter-of-explanation loop.
Instead of leaning on a projected income from a market-data tool, the file can now run on actual booking receipts, discounted for expenses.
Resort real estate is a different animal than a workforce rental three blocks from a hospital. The tenant is a vacationer, not a lease-signer.
Add reserves, a credit floor, and proof the association actually allows nightly rentals, and you have the full picture.
It works less well on properties with plenty of income cushion, where the investor would rather build equity than lower the payment.
Get that stack right and the loan is priced off a track record, not a guess.
Coverage matters, but so does documented booking history — twelve months of it, on most files.
Investors shopping a $1M luxury short-term rental usually walk in assuming the math works the same way it did on their last $400,000 duplex. It doesn’t.
Short-term Rental DSCR Loan Requirements When Permit Limits Apply — Permit legality gets checked before rental income ever enters the math.
Cash-out Refinance On A $1M Short-term Rental DSCR Loan: what investors need to know about large-balance DSCR financing, from Lendmire.
DSCR loans are designed for non-owner-occupied investment properties.
Loan amounts on this property type typically top out around $1,500,000, with leverage capped tighter than a standard rental.
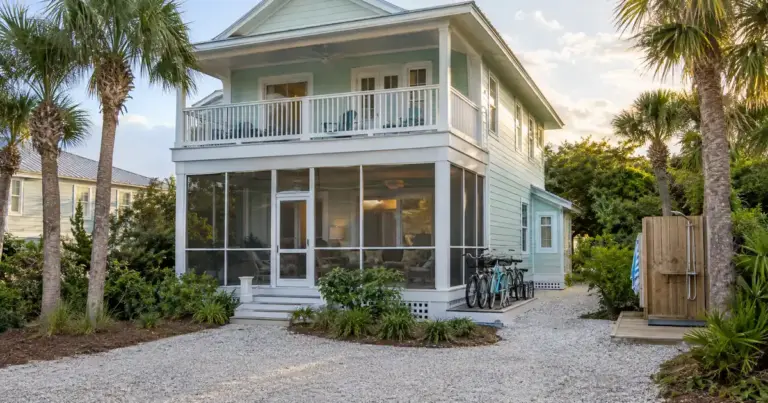
Two independent appraisals replace one. Reserve math gets stricter for first-time investors.
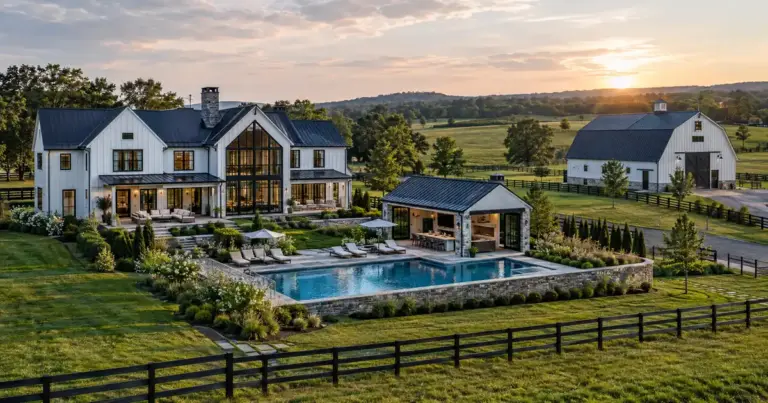
Credit, reserves, entity paperwork, and — above a certain size — a second appraisal round out the file.
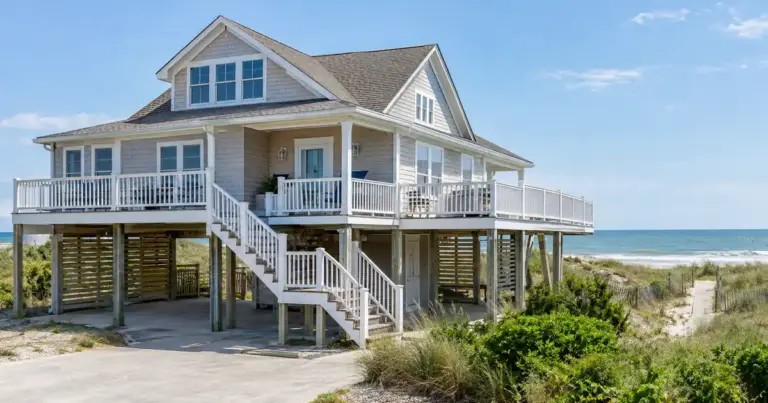
Reserves typically run six months of PITIA on the subject property, doubling to twelve if the investor has no prior landlord history.