How Condotel Units Are Financed On A Super Jumbo Bank Statement Loan?
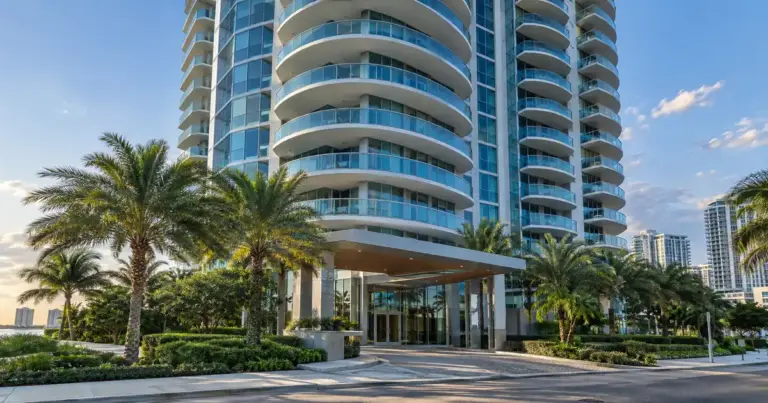
Condotels never make it onto an agency approved list.

Condotels never make it onto an agency approved list.
Pull Cash Out Of A Short-term Rental After A Cash Buy — Yes.
A defined three-to-seven-year hold usually points toward an adjustable structure with a shorter prepayment window.
Investors chasing waterfront or resort units often assume that once their bank statements qualify them for a large loan, the building type is a formality.
The appraisal is doing double duty on a DSCR file: it sets the collateral value for leverage and it sets the market rent that drives the coverage ratio.
The trustee typically signs as the individual guarantor even though the trust holds title.
Sometimes that second document is a full physical appraisal from a different appraiser.
Nothing above that on ordinary files.
A numeric rental cap doesn’t automatically kill the deal — a minimum-lease-term rule usually does, regardless of the coverage ratio.
Luxury Short-term Rental DSCR Loan Close In Thirty Days — Yes, but only on a clean file at the smaller end of the luxury range.
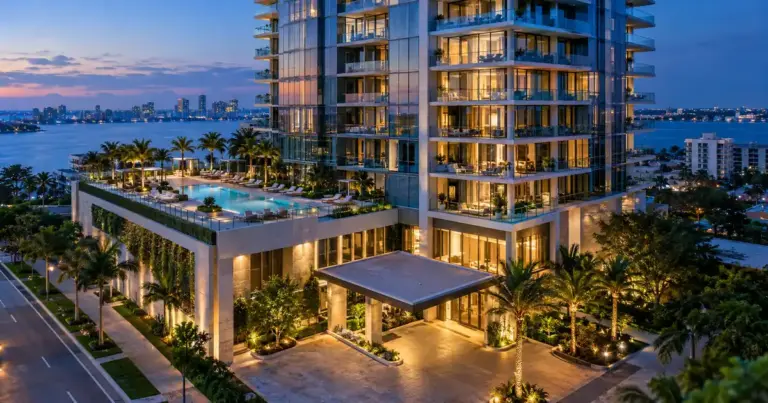
Non-warrantable condos and condotels can both qualify, but at reduced leverage and lower loan caps than a standard warrantable condo.
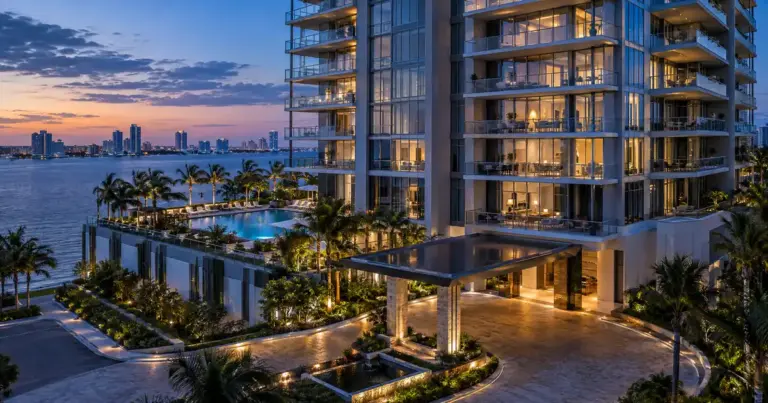
Condo Or Condotel Qualify For A Super Jumbo — Yes, both can qualify. A warrantable condo is treated almost like a single-family home.
Sizing, down payment, and documentation all shift once the property carries a condotel label, so the planning has to start there, not at the offer stage.
Asset depletion turns savings, brokerage holdings, and retirement accounts into a monthly income figure by dividing them over a set number of months.
Because one note ties to several properties, a single missed title item or slow insurance quote on any one property can stall the entire pool.