Should A Practice Owner Use A DSCR Loan On A Beach Rental?
Should A Practice Owner Use A DSCR Loan On A Beach Rental — Yes, if the beach house will be a pure rental with zero personal use, ever.

Should A Practice Owner Use A DSCR Loan On A Beach Rental — Yes, if the beach house will be a pure rental with zero personal use, ever.
Once the rent number is set, the loan is judged on one ratio: does the rent cover the payment.
When that shrunken tax return kills a conventional application, DSCR financing qualifies the loan on the property’s rent instead of the owner’s 1040.
That comparison is called DSCR, or debt-service coverage ratio. If the rent covers the payment, the file has a real shot regardless of your personal income.
Knowing this before you apply — not after the appraisal comes back — is what separates a smooth file from a surprise.
Underwriters apply a discount to the vested balance because the money is harder to reach and carries tax exposure if pulled out early.
Luxury Duplex Match Single-family Leverage on a Jumbo — No, not exactly.
Done this way, there’s no existing mortgage to trip a due-on-sale clause, and the closing package just grows by a few documents.
The size and complexity of the file — not the entity — is what drives leverage, reserves, and documentation on a luxury rental.
Does An LLC Investor Need A Personal Guaranty On A DSCR Portfolio Loan — Yes, in almost every case.
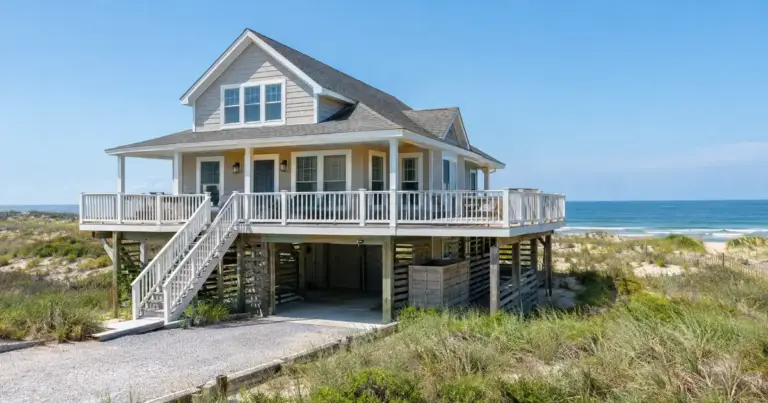
But the underwriting doesn’t count gross booking revenue — it counts a discounted, documented version of it.
Invested Assets Count As Reserves On A Jumbo DSCR Rental Loan — Cash and cash-equivalent accounts generally count at full value.
The appraiser produces a new value and a new market-rent opinion, and underwriting uses the lower of that rent or the in-place lease.
The lender underwrites the property’s rent and the guarantor’s credit, not the LLC’s age or balance sheet.
Does Rising Rent Unlock More Leverage On A DSCR Portfolio Refinance — Not automatically.