Does An Off-season Month Break A Jumbo DSCR Rental Loan Coverage Test?
Does An Off-season Month Break A Jumbo DSCR Rental Loan Coverage Test: what investors need to know about large-balance DSCR financing, from Lendmire.

Does An Off-season Month Break A Jumbo DSCR Rental Loan Coverage Test: what investors need to know about large-balance DSCR financing, from Lendmire.
The appraisal, not a rent-roll spreadsheet, sets the income number that drives every leverage decision after it.
A jumbo DSCR lender qualifies the loan on whichever number is lower: the rent from the signed lease, or the appraiser’s opinion of market rent.
An above-market lease never bumps up the qualifying income; the appraisal caps it.
The tradeoff is cross-collateralization — every property in the pool is tied to the same note.
Can A Rental On Twenty Acres Qualify For A Jumbo DSCR Loan — Sometimes, but not on the full parcel.
Above roughly $2 million, expect two appraisals, tighter leverage, and higher credit floors.
HOA Litigation Block a Luxury Short-Term Rental — No single federal rule automatically kills a DSCR loan because the HOA is in litigation.
The LLC sits on the note as borrower, but a human being signs a separate document promising to pay if the LLC doesn’t.
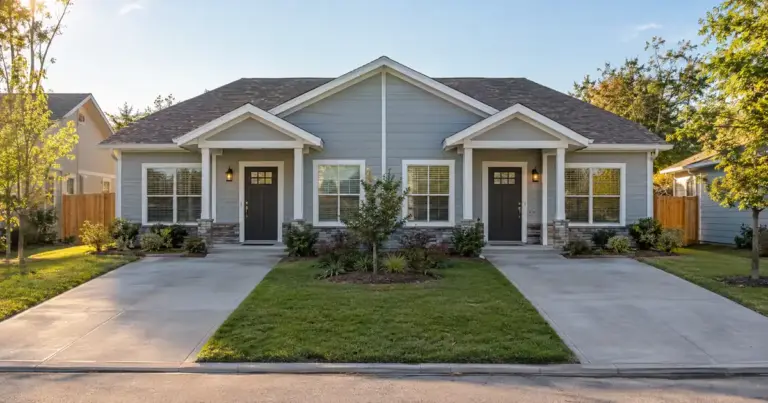
Yes. Inside one blanket DSCR loan, a duplex and a single-family rental are underwritten as a single pool, not as two separately-leveraged loans.
That’s the cross-collateral test: if one property goes bad, the lender’s remedy reaches every property in the pool.
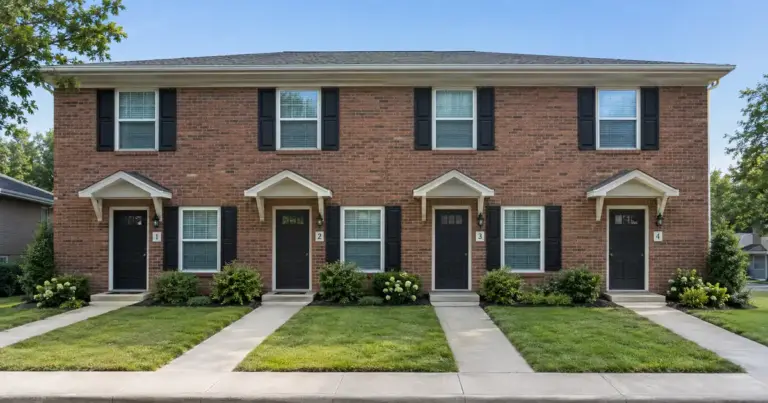
Price doesn’t move a fourplex into commercial underwriting — unit count does.
On a DSCR loan, a non-warrantable finding caps leverage instead of killing the deal outright.
The loan amount, the credit tier, and the coverage math all use the same ladder.
A high lease doesn’t push the ratio up past what the appraisal supports, and a below-market lease can drag the ratio down even on a strong property.