
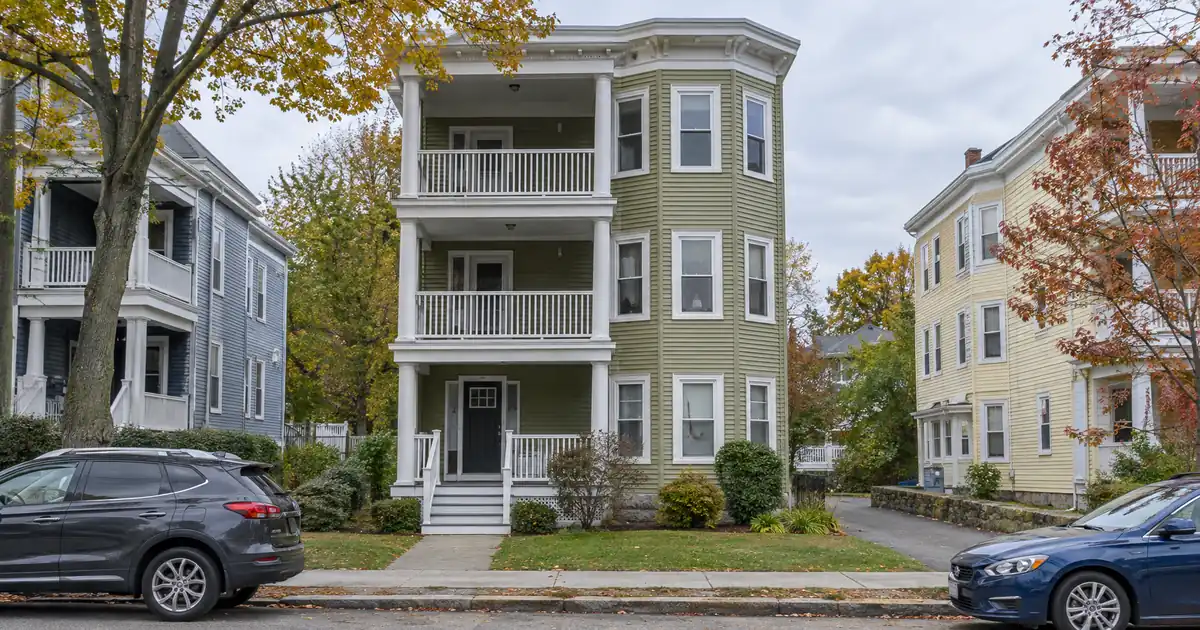
Can a Framingham investor pull cash out of a rental without the rent coverage falling short? It depends almost entirely on unit count. Homes.com shows multi-family listings priced from $699,995 to $2,999,999, against a single-family and condo median of $674,900. The two product types enter near the same price. One stacks two or three rents on it. The other stacks one. Through Lendmire’s DSCR program footprint — 41 markets, including Washington, D.C. — lenders may review qualifying rental income subject to program guidelines for Framingham, Massachusetts investors, and Lendmire (NMLS# 2371349) is the DSCR-focused mortgage broker that arranges those files.
The Quick Read: A Framingham cash-out refinance on a 2–4 unit building is underwritten primarily on the property’s rental income measured against its full monthly obligation, which makes it the better fit for owners of small multifamily than for owners of single-family homes.
DSCR Cash-Out Calculator
Run the cash-out numbers in Framingham, MA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 1, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 1, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Two-bedroom rents average $2,618 per RentCafe, which is what a duplex stacks.
- Cash-out tops out at 75 percent LTV, with about six months of seasoning from title recording.
- Single-family rent-to-price is thin, so coverage usually binds before LTV does.
- Rent trend data conflicts across sources. Underwrite on in-place rent, not hoped-for rent.
Framingham Market Snapshot
A quick read on the Framingham investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| University enrollment | 3,529 total (Framingham State University) |
| Employment | 45,000+ jobs (City of Framingham) |
South Framingham and Downtown: Where the Stacked Rents Are
South Framingham and Downtown are the strongest cash-out submarkets in the city. Older two- to four-unit stock sits here, along with the commuter rail and the City’s two Opportunity Zones aimed at Downtown redevelopment. The City’s Market Analysis notes that one South Framingham Census tract has 91 percent of its units built before 1980. For a refinance, that cuts two ways. Older stock means lower basis for owners who bought years ago. It also means maintenance drag and appraisers who look hard at condition.
Run the numbers on a duplex. Assume two 2BR units at about $2,600 each, roughly $5,200 gross a month. That is a modeled figure built from the RentCafe average. Against a $760,000 value (the median multi-family listing in South Framingham per Redfin, drawn from only three listings), gross rent comes to roughly 0.7 percent of price. At 75 percent LTV, with full PITIA counted including taxes and insurance, coverage lands around 1.1x. Tight, but above the 1.00 benchmark most standard programs are built around. Thin sample, so treat the $760,000 as an anchor, not a comp.
Downtown rents are the murky part. Rent.com puts the Downtown 1BR average at $3,104, the highest in the city, while other sources frame Downtown as the affordable end of town. Both can’t be right. Pull street-level comps before quoting a ranking to anyone, including yourself.
One property-type wrinkle: Downtown has mixed-use buildings, such as a four-apartment building listed with street-level office space. Lenders may treat these as commercial or mixed-use, with limits on the commercial share. Confirm residential-unit and commercial-share rules before assuming a standard 2–4 unit DSCR file. Not every Downtown building fits.
Framingham Centre and the Route 9 Belt
Framingham Centre pairs the Route 9 corridor with Framingham State University, which enrolled 3,529 students in the most recent fall, 2,640 undergraduate and 889 graduate. A market source reports 51 percent live off campus. That is a steady tenant pool for 2BR and 3BR units, plus faculty and staff.
Rent.com lists Framingham Centre’s 1BR average at $2,250, the lowest of the neighborhoods it tracks. The Golden Triangle retail-office corridor runs $2,531 and Saxonville $2,575. These are small samples. Read them as a pecking order of rough magnitude, not as rent comps.
Saxonville is a mill village with real character. Character does not pay a mortgage. The numbers there are too thin to build a thesis on.
Single-Family: Where Coverage Becomes the Constraint
Single-family is the weak spot for a DSCR cash-out here. Rentometer shows three- and four-plus-bedroom houses at $3,800–$4,100 a month. Against a $674,900 median, that is about 0.56–0.61 percent of price, gross.
Model a single-family at roughly $675,000 and rent near $3,950. Including taxes and insurance at 75 percent LTV, coverage sits around 0.9x. Below 1.00. Not a dead file, but a harder one. Sub-1.00 scenarios may be reviewed by select lenders through a sub-1.00 program, an interest-only structure or reduced leverage, and each path comes with trade-offs: more cash left in the deal, tighter credit requirements, different pricing. Qualification stays subject to lender guidelines, credit approval and property review.
Honestly, the stronger play might be to refinance the duplex and skip the single-family. Investors who want the single-family’s long-run appreciation could argue the other way. The data does not show much appreciation to lean on.
Nobscot and North Framingham are a separate case. Buyers there often pay $700,000 to $800,000 or more, which makes the neighborhoods owner-occupant territory. Rent-to-value is lopsided. Skip them for DSCR cash-out.
What the Appraiser Will Actually See
Appreciation is flat, so the appraisal carries the whole cash-out. Zillow puts the typical home value at $671,985, up 0.3 percent year over year, with homes going pending in about nine days. Movoto shows the median list price at $675,000, down 3 percent. Different measures, same message: nobody is getting a free equity boost from the market. Underwrite at today’s value.
Rent direction is a mess:
Apartment List shows a median at the low end of the sources and trending down. RentCafe shows a noticeably higher figure that is also slipping. Zumper shows the highest figure of the group, with the steepest decline. RentHop shows two-bedroom rents up and three-bedroom rents down.
The sources differ by hundreds of dollars because they sample different buildings. RentCafe tracks 50-plus-unit complexes, which skews high for a duplex owner. The Census-based median gross rent is $2,112 per city-data.com. A defensible range runs about $2,100 to $2,500. The City also warns that advertised units run well above median rent. In-place leases, not asking rents, set the number.
Working DSCR brokers see a recurring pattern in older Northeast small-multifamily markets: owners who bought long ago hold plenty of equity on paper, then discover that one under-market lease on a three-unit drags blended coverage below the line. The fix is usually done before the file goes in, with lease updates where the lease terms allow and a clean rent schedule. Appraisers in flat markets pay close attention to the rent schedule.
Who Rents Here (and Keeps Renting)
Framingham is a net importer of jobs. The City’s Economic Development page reports more than 45,000 jobs, more than 2,200 businesses and $3.1 billion in payroll. Staples is the City’s largest employer, with TJX, Sanofi Genzyme and Bose also named in the Market Analysis. Population is flat: 72,399 per Cubit’s ACS summary, with median household income of $107,419.
Flat population plus a heavy daytime workforce is an odd combination. It means demand for rentals comes from people commuting in and choosing to stay. Forty-five percent of households rent, per RentCafe (12,412 renter households), and the largest rent band, 40 percent, falls between $2,001 and $2,500. Underwrite near that band, not at luxury rents.
MetroWest Medical Center adds teaching-hospital demand across Framingham and Natick, and MassBay Community College serves roughly 6,000 students across its campuses. These anchors don’t set rents. They keep the vacancy tail short.
The City also states that Framingham lacks “missing middle” housing. Of owner-occupied units, 93 percent are single-unit homes, and one-bedroom units are scarce. A duplex with 2BR units matches how the market is built. That scarcity is the case for small multifamily here, and it’s why the cash-out math favors it.
Seasoning, LTV and What the Proceeds Do Next
The mechanics are short. Cash-out on an investment property caps at 75 percent LTV, with about six months of ownership seasoning measured from title recording. Standard programs reach up to $3,000,000. Minimum credit sits at a 620 floor, with tiers at 660, 680 and 700 that typically improve the file. Reserves run about six months of PITIA, more on balances above $1,500,000. Equity available is not a guaranteed figure: it depends on rent used for lender review, PITIA, reserves and the 75 percent ceiling. LLC-titled borrowers are accommodated subject to lender program eligibility. For the mechanics in detail, see the guide “What Is a DSCR Loan”, and for refinance details see the refi options. The side-by-side comparison covers how this differs from a conventional refinance. Program details can shift, so confirm current guidelines with a broker. Massachusetts-specific file questions go through Lendmire’s Massachusetts DSCR loan programs.
What do proceeds do? The cleanest use is another small multifamily, bought with the new cash. Stacked rents beat single-family math in this city, so the proceeds work harder in a second duplex than in a renovation of a house. Investors can talk to Lendmire or call 828-256-2183 to see how a specific building models. Verify current local rental rules, taxes and insurance with qualified local professionals before committing.
Bottom Line
Flat prices and conflicting rent data mean the cash-out here is earned by the rent roll, not the market. The investors who document in-place rents and refinance small multifamily now will come out ahead.
Frequently Asked Questions
Does a Framingham duplex cash-out beat a single-family cash-out on DSCR?
Usually, yes. Two stacked 2BR rents produce coverage near 1.1x in the modeled case, while a single-family at similar value lands around 0.9x. Single-family files may still be reviewed through sub-1.00 options, interest-only structures or lower leverage, subject to lender guidelines.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Framingham, MA, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
How long before a Framingham investment property is eligible for cash-out?
About six months of ownership, measured from title recording. Programs vary by lender. Investors who bought recently should confirm the recording date and any renovation timeline with their broker before ordering an appraisal.
Can a Downtown mixed-use building qualify for a standard DSCR cash-out?
It depends on the property and the lender. Buildings with apartments over street-level office space may be underwritten as mixed-use or commercial, and lenders set limits on the commercial share. A pure 2–4 unit residential building is the cleaner fit.
With rents flat to down, how do lenders see Framingham rents?
Lenders tend to view them cautiously. Published sources vary widely in their rent estimates, so underwriters are likely to lean on in-place leases and appraiser rent schedules. Submit current leases rather than asking-rent screenshots.
Does flat appreciation limit how much cash comes out?
Yes. Proceeds rest on the appraised value, capped at 75 percent LTV, minus the existing payoff. There is no appreciation cushion to assume, so the number is whatever the appraisal supports.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire — NMLS# 2371349 — is a DSCR and non-QM mortgage brokerage offering investor loan programs in 41 markets, including Washington, D.C. Lenders commonly review DSCR eligibility around the property’s rental income rather than personal income documentation, subject to lender guidelines. The brokerage helps arrange financing for LLC-owned portfolios beyond conventional financed-property limits. Recognized by Scotsman Guide as a 2026 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2025. See Lendmire’s 2026 Top Workplace announcement.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Homes.com, Framingham multi-family
3. Framingham State University, Quick Facts
4. City of Framingham, Economic Development
5. City of Framingham, Market Analysis
6. Redfin
7. Rent.com
8. Rentometer
9. Zillow
10. Movoto
11. Apartment List
12. Zumper
13. city-data.com
17. a 2026 Scotsman Guide Top Mortgage Workplace
18. Scotsman Guide — Top Workplaces 2025
19. Lendmire’s 2026 Top Workplace announcement
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Framingham Massachusetts · DSCR Cash Out Refinance in Newton, Massachusetts: The 2026 DSCR Guide to Newton Centre · Cash Out Refinance Investment Property in Attleboro, Massachusetts
Guides: Investment Property Cash-Out Refinance in Framingham, MA · Investment Property Cash-Out Refinance in Massachusetts
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.