
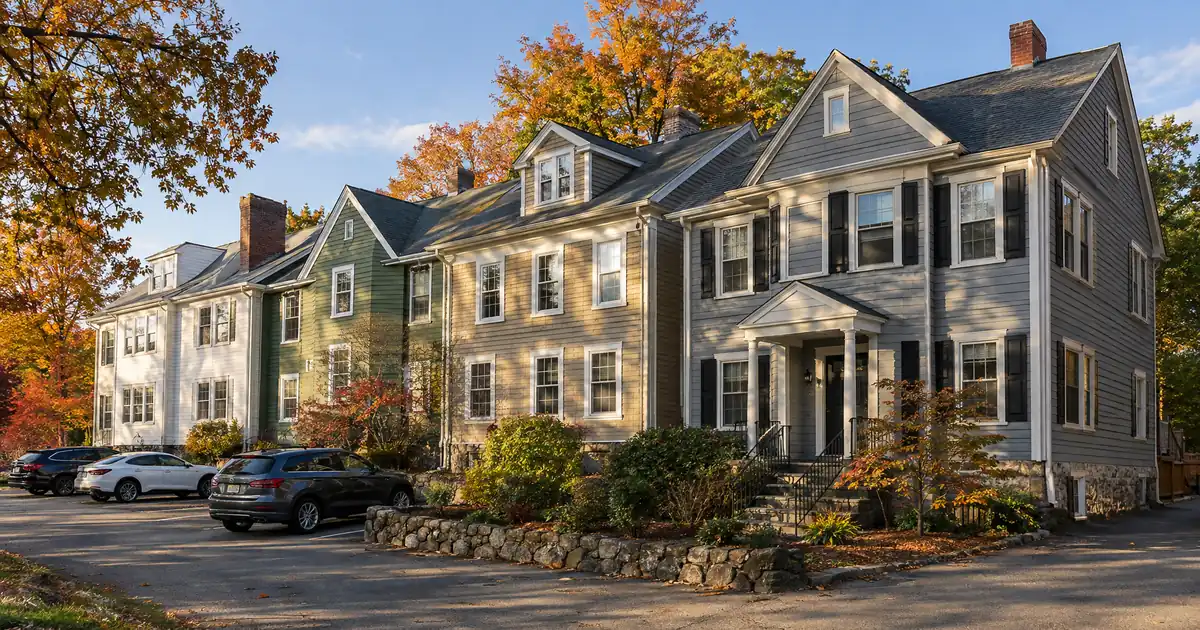
Can a cash out refinance on an investment property in Attleboro, Massachusetts carry itself on rent alone? Usually yes if the building has several units, and usually no if it is a single-family rental. Zillow’s average three-bedroom rent has to cover a large balance on one door, while multi-family listings in the city put several rents behind one loan.
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker. Investors underwriting deals in Attleboro, Massachusetts can use DSCR programs Lendmire arranges — available across 41 markets, including D.C. This article covers the equity side: owners who already hold a rental here and want to pull capital out of it.
DSCR Cash-Out Calculator
Run the cash-out numbers in Attleboro, MA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version: A cash-out refinance on an Attleboro, Massachusetts investment property is underwritten primarily on the property’s rental income measured against its full monthly obligation, after the lender reviews ownership seasoning, appraised value against a leverage ceiling, reserves and credit. At local prices, multi-unit buildings meet that test far more readily than single-family homes.
- Single-family coverage runs thin: a $2,600 three-bedroom rent against a $557,500 median sale price.
- Three-family buildings put three rents behind one loan.
- Cash-out seasoning is about six months from title recording.
- Cash-out leverage tops out at 75 percent of appraised value.
- Downtown station ridership supports older 2–3 family stock nearby.
Attleboro Market Snapshot
A quick read on the Attleboro investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $448,100 median value (Data USA) |
| Employment | 2,000+ employees (Sturdy Health) |
What Does the Math Say on Single-Family?
Single-family rentals are the weak spot. Redfin puts the citywide median sale price at $557,500, up 12.2 percent. Zillow’s home value index sits lower at $477,973, a gap that comes from methodology, since Zillow’s index includes condos. The rent side does not close that gap. Zillow shows the average three-bedroom at $2,600 and the average two-bedroom at $2,000.
Run the numbers on a modeled single-family home valued near the Redfin median, refinanced at the 75 percent ceiling, with taxes and insurance included in the payment. Against a $2,600 rent, coverage lands somewhere between 0.7x and 0.85x. Those are modeled assumptions, not a market statistic. The standard baseline in most DSCR programs is 1.00x, so this file is below it.
Below 1.00x is not automatically dead. A lender may review a sub-1.00 program, an interest-only structure, or lower leverage with more cash left in the deal. Each carries different pricing and conditions, and eligibility depends on lender guidelines, credit and property review. Still, it is a harder file than the multi-unit alternative.
Three-Deckers Stack the Rent
The strongest fit in Attleboro is the older two- and three-family building. Homes.com shows multi-family listings from $419,900 to $999,990. Redfin’s downtown listings include a three-family with two five-room units of two or possibly three bedrooms and a one-bedroom on the third floor. Listings are not closed sales, so treat the range as a ceiling and floor for what owners are asking.
Model a three-family valued at $600,000 (a modeled assumption). Use Zillow’s $2,600 three-bedroom average twice and Apartment Finder’s $1,765 one-bedroom average once. That is $6,965 in gross monthly rent. At 75 percent LTV with taxes and insurance counted, coverage clears 1.5x. Those are average rents, not the rents in any specific building. An appraiser’s rent schedule and the actual leases will decide the coverage figure.
Single-family rent-to-value on these figures is thin. A three-family listed at the bottom of the multi-family range works out to a much higher ratio. Same city. Different building type. That is why how DSCR coverage is calculated matters more here than in markets where single-family rents carry the load.
Working DSCR brokers see a recurring pattern in older-stock, small-multifamily markets like this one: the coverage ratio is rarely the problem. The file stalls on rent-roll clarity. Heat and hot water included in one unit’s rent, a vacant unit with no lease, or an owner-occupied floor all force the underwriter to rebuild the number unit by unit. Clean leases and a utility schedule per unit, in the file before it goes in, remove most of that.
Downtown Gets the Ridership
Downtown and the City Center are the best-supported submarket for stacked rent. The Attleboro commuter rail station recorded 1,220 daily boardings, the third-busiest on the MBTA system outside Boston, with Boston and Providence both reachable by rail. Redfin shows a downtown median near $450K, down 5.3 percent. No sourced rent-to-value ratio exists by neighborhood, so this is inference from listings and ridership, not a measured spread.
The city and the MBTA have also prepared a 6.5-acre transit-oriented development site next to the station, targeting about 600 market-rate and affordable units. No developer or start date is confirmed. For a cash-out borrower this cuts two ways. It signals investment near the platform, and it could add supply that caps rent growth for older units. That one is a toss-up, and underwriting should not assume either outcome. The City of Attleboro describes the site as a neighborhood-scale opportunity with connections to both cities.
South Attleboro Village looks similar on a map. It sits just north of the Rhode Island border on the same rail line. But the station there recorded only 19 daily boardings after a stretch of closure. It is a price-led play, not a commuter-demand play. Don’t assume the rail line fills the units.
Dodgeville and Briggs Corner are described as a mix of single-family homes and apartment complexes, mostly built in the 1970s through the 1990s. No usable rent data turned up for either. Treat them as single-family-style underwriting with the thin coverage that comes with it.
Who Actually Rents Here
Healthcare is the largest resident employment sector. Data USA counts 3,867 residents in health care and social assistance, ahead of manufacturing at 3,238 and retail at 3,166. Sturdy Health employs more than 2,000 people and runs a 142-bed hospital, so two- and three-bedroom demand near it has a steady base. Data USA also shows the average commute at 30.5 minutes, which fits a city where tenants work in Boston, Providence or locally. The city’s population is about 46,762.
Rents are moving up. Zillow shows an all-types average of $2,295, up $295 from a year earlier, and Zumper reports rents up 9.5 percent. The ACS-based median rent is lower, at $1,446, because Census-style figures lag asking rents. That gap matters at appraisal. Asking rents set the hope. The appraiser’s rent schedule sets the number.
One ceiling check: a newer building near the station lists one-bedrooms from $1,925 as a total monthly price, fees included. That overstates base rent. Don’t underwrite a legacy unit at new-construction pricing.
Appraisal Is the Real Gate
Appraisal is where Attleboro cash-out files get tested. The price signals conflict. Redfin’s City-area median was $552K, down 3.1 percent, while price per square foot was up 15.5 percent, and only 16 homes sold in the month behind that figure. Medians on that few sales swing with the mix of homes sold. An appraiser leans on a handful of comps.
So the equity an owner expects and the value the appraisal supports can differ. A value 5 percent light, run through the 75 percent ceiling, takes a real bite out of proceeds. The practical response is an appraisal reconsideration packet: recent in-neighborhood sales, unit-count and condition adjustments, and a rent schedule that matches the leases. Owners should expect to use it.
Two more mechanics shape the file:
- Seasoning. Programs typically require about six months of ownership measured from title recording. Someone who bought a three-decker, renovated it and wants out in month four is early. Settlement statements prove the date.
- Reserves. Programs generally look for about six months of PITIA in reserves, subject to lender guidelines. Reserves documentation, not coverage, is the item that most often gets requested twice.
Equity available depends on rent used for lender review, the full payment, reserves and the 75 percent ceiling. It is not a guaranteed cash figure. The DSCR cash-out refi mechanics page lays out the full sequence, and the investor refinance options page covers rate-and-term versus cash-out. DSCR files also skip the personal-income stack that conventional investment loans require. That helps self-employed owners and LLC-held portfolios, though the property still has to carry the debt. Older buildings also bring compliance items. Verify current local rules, taxes and insurance with qualified local professionals before committing.
Where the Proceeds Go
The point of pulling equity is the next deal. A seasoned three-family that clears coverage at the 75 percent ceiling can fund the down payment on a second building, with the new purchase underwritten on its own rents. The risk is stacking leverage. Two multi-unit buildings both at the ceiling leave little cushion if one unit sits empty, and reserves requirements apply to the new property too. Investors holding properties across the state can review the broader program page for DSCR loans in Massachusetts. Questions on a specific building can go to 828-256-2183.
The Choice in Front of an Attleboro Owner
An owner with a seasoned downtown three-family can refinance now and take proceeds against rents that stack cleanly, accepting that an appraisal built on thin sales may come in light and that new supply near the station could cap rent growth. Or the owner can hold the equity in place, skip the appraisal risk and the added leverage, and wait to see whether the transit-oriented site near the platform lifts values or just adds competition for tenants.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Attleboro?
The property’s rent used for lender review has to cover its full monthly payment, with taxes and insurance included, at a typical minimum of 1.00x. On most files the lender also looks at credit (a typical floor is 620), about six months of seasoning, and about six months of reserves. In Attleboro, a multi-unit building usually gets there more readily than a single-family home. All of it is subject to lender and program guidelines.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Attleboro, MA, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for cash-out on an Attleboro investment property?
Cash-out leverage generally tops out at 75 percent of appraised value, and the required ownership period is typically measured from title recording. Loan amounts run up to $3,000,000 on standard programs. Manufactured homes, log homes and barndominiums fall outside these programs. Terms vary by borrower, property and loan scenario.
Why does a three-decker cash-out better than a single-family here?
Three units put three rents behind one loan, while a single-family home puts one rent behind a balance priced near the citywide median. On modeled figures, the single-family sits well under 1.00x and the three-family clears 1.5x. Utilities included in rent can narrow the gap, so each unit gets underwritten separately.
How risky is appraisal value in Attleboro?
The risk is real because sales volume is thin and sources disagree. Redfin’s recent City-area median fell while price per square foot rose, on only 16 sales in the month. Plan for an appraisal that lands below the number you hoped for, and keep a reconsideration packet of comps ready.
Can an LLC-owned Attleboro rental be reviewed for DSCR financing?
Yes, subject to lender program eligibility. Lendmire arranges DSCR investor loans and reviews are built around the property’s rental income rather than personal income documents. Entity documents and operating agreements should be ready before submission.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income rather than personal income, subject to lender and program guidelines, which suits self-employed investors and LLC-owned portfolios. The brokerage was recognized by Scotsman Guide as a 2026 Top Workplace and was a top-ranked workplace in 2025.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Rental Manager: Attleboro
2. $419,900
3. Redfin: Attleboro housing market
6. $477,973
7. ApartmentFinder — Massachusetts Attleboro Apartments
9. MBTA: Attleboro redevelopment announcement
10. City of Attleboro: Transit-Oriented Development District
11. Wikipedia — South Attleboro Station
12. massachusetts-demographics.com — Attleboro Demographics
13. Zumper reports rents up 9.5 percent
14. Apartments.com — 75 Main LLC Attleboro MA
16. recognized by Scotsman Guide as a 2026 Top Workplace
17. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Attleboro, Massachusetts: How DSCR Coverage Works on an Attleboro Refi · DSCR Cash Out Refinance in Lynn, Massachusetts: Triple-Decker Equity After Seasoning · DSCR Cash Out Refinance in Plymouth, Massachusetts: Equity From Cordage Park Multi-Units
Guides: Investment Property Cash-Out Refinance in Massachusetts
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.