
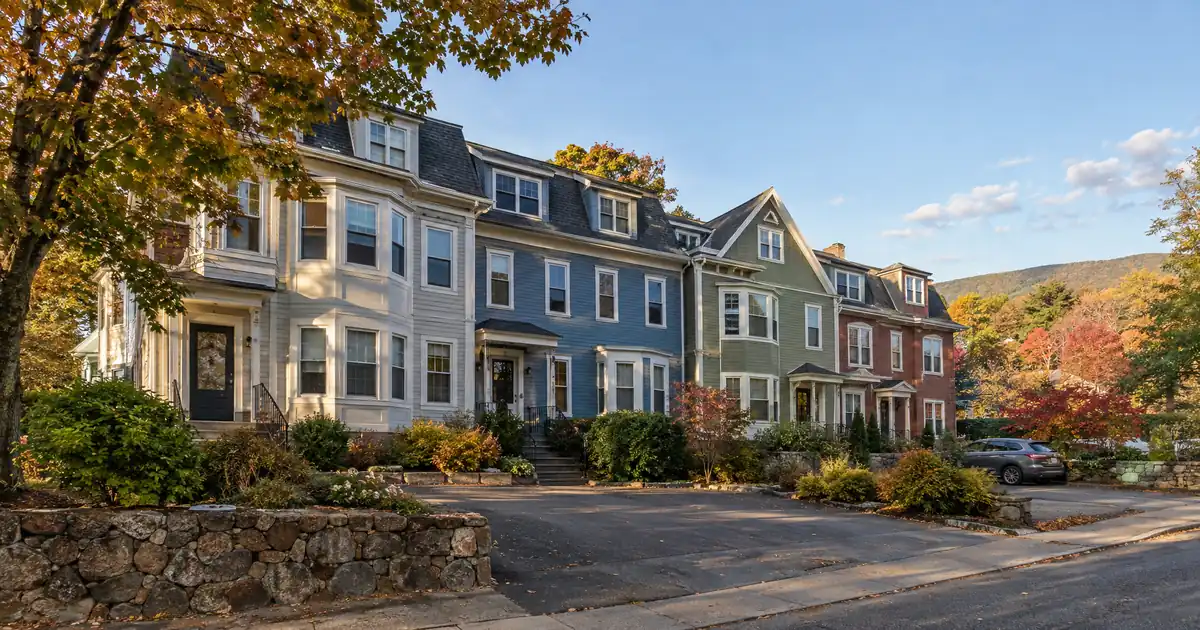
An out-of-state investor scrolling Pittsfield listings usually fixes on price per unit and assumes a soft market. What gets missed is the tenant side. The Berkshire Eagle reported a home vacancy rate of 0.6 percent, against a “healthy” 1.5 percent, with rents climbing faster than values. For an owner already holding a duplex or triplex here, that is the backdrop for a cash-out refinance on an investment property: pull equity from a building you own, keep the rent roll intact, and redeploy. The real questions are about appraisal, seasoning, and paperwork, not whether tenants exist.
TL;DR: A DSCR cash-out refinance on a Pittsfield, Massachusetts rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with the lender reviewing seasoning from title recording, an appraisal, reserves, and a 75 percent loan-to-value ceiling rather than the owner’s traditional personal-income documentation, subject to lender guidelines.
DSCR Cash-Out Calculator
Run the cash-out numbers in Pittsfield, MA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Morningside two-family flats with matching two- or three-bedroom units give the cleanest coverage math.
- Rents rose 10.3 percent in the latest year against 10 percent for values, per the Berkshire Eagle.
- Sources disagree on price growth, so size proceeds to appraisal comps, not headlines.
- Buildings of five or more units commonly route to commercial lending instead.
- Seasoning runs about six months from title recording, and equity is never a guaranteed figure.
Pittsfield Market Snapshot
A quick read on the Pittsfield investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | 118 sales in may (Redfin Pittsfield housing market) |
| Recent appreciation | +10% (Berkshire Eagle, 2026 Berkshire) |
| University enrollment | Over 2,000 students (Berkshire Community College) |
| Employment | 4,000+ employees (Berkshire Health Systems About) |
| Vacancy | 0.7% homeowner (UMass Donahue Institute coverage) |
Morningside Is Where the Product Is
Morningside is the strongest cash-out submarket in Pittsfield for 1-4 unit DSCR files. It is older, primarily residential stock with a lot of two-family flats, and Redfin shows a median near $280,000 on pending listings there. Those are listing snapshots, not a clean neighborhood median, but they tell you where the price per unit sits.
What matters is the unit mix. Listings on Homes.com describe a fully rented two-family flat with three bedrooms and one bath per unit, heat and hot water included. Others describe a duplex with three bed/one bath on each side, or a two-family with two bed/one bath per unit. Two larger units on one loan means two rents against one payment. That is the practical route to coverage in this city.
Look at who pays utilities. Owner-paid heat and hot water won’t change the rent used for lender review much, but they will change your actual cash flow. Check that before you decide how much equity to pull.
The neighborhood sits near Pittsfield Common and Silver Lake, per a Williams College report, and the Homes.com multi-family listings cite proximity to the medical center. Demand is workforce renters. That fits long leases and low turnover better than it fits appreciation speculation.
West Side: The Hospital Does the Work
West Side duplexes serve a different tenant mix. Berkshire Health Systems is the largest employer in Berkshire County, with more than 4,000 employees. Berkshire Medical Center is a Level III Trauma Center running three residency programs, with clinical partnerships that include Baystate Health, Dana-Farber, and Mass General Brigham. It also hosts students from UMass Chan, the University of New England’s osteopathic college, and Boston University.
That pipeline of staff, residents, and rotating trainees adds demand on top of permanent employment. One West Side listing pitches a six-bed, two-bath side-by-side duplex as walkable to downtown and the hospital. The tradeoff: trainees rotate, so expect some turnover even on 12-month leases. Berkshire Community College adds a small but steady layer, serving roughly 2,000 students on an 180-acre campus on West Street. Enrollment figures vary by source, so treat that as an approximate number.
Downtown and the Upstreet Cultural District are a third lane. Pittsfield Economic Development points to a 45-room boutique hotel and more than 50 restaurants, and downtown multi-family listings carry a median asking price around $289,000, per Redfin. Those buildings sit on the market for a median of 79 days.
What the Rents Actually Support
Rent sources for Pittsfield disagree, so use a range. Zumper puts the all-property median at $1,550, up 5 percent year over year. Rentometer shows a two-bedroom at $1,804 across all property types, while its own narrative text runs lower. Apartments.com shows a two-bedroom at $1,318, an older figure that likely skews toward larger buildings.
Run the numbers this way, as a modeled example, not a market rent roll. Assume a two-family downtown-style building valued at $289,000, refinanced at 75 percent LTV, with two 2BR units. At $1,318 per unit on the low end, and including taxes and insurance at Massachusetts averages, coverage lands around 1.4x. At $1,804 per unit, it approaches 1.9x. Both clear the standard 1.00x benchmark, though exact eligibility depends on lender guidelines, credit, reserves, and property review.
Here’s the catch, and it’s a good one: at those coverage levels, the binding constraint isn’t the rent. It is the 75 percent LTV ceiling and the appraisal. A strong coverage number doesn’t buy you more proceeds.
Working DSCR brokers see a recurring pattern in older-stock, small-balance multi-family markets like this one: the rent side of the file is rarely the problem, and the appraisal side often is. Files stall on thin comps, unclear unit counts, missing leases, or an owner who can’t document which tenant pays which utility. Getting the rent schedule and lease copies in order before the appraisal is ordered prevents most of the friction.
Three Prices, One Appraisal
Pittsfield’s appreciation story depends on which source you read. The Berkshire Eagle, citing Berkshire County Board of Realtors data, reported median prices up 10 percent, to $327,450. Redfin shows a $320,000 median, up 10.5 percent. Zillow’s index puts the average home value at $309,464, up only 1.1 percent. Those are different measurements, and an appraiser will use comparable sales, not any of them.
The market is also cooling at the edges. Redfin shows homes selling after 41 days on average versus 27 a year earlier, with 118 sales in May. That is plenty of volume for comps. But longer days on market suggest less bidding-up, so a value-add refinance shouldn’t assume the appraisal lands above what was paid.
Do the equity math in percentages. Say an owner’s existing balance equals 55 percent of the value they expect. At the 75 percent ceiling, that leaves 20 points of value as the maximum available. If the appraisal comes in 10 percent short, the room shrinks to about 12.5 points of the original value. A 10 percent miss cuts proceeds by more than a third. This is why underwriting to the conservative number beats underwriting to the best headline.
Rent growth does cushion this. Per the UMass Donahue Institute, Berkshire County rents have climbed sharply over a roughly four-year stretch. The same source also projects the county’s population to decline by 2035. Rising rents against a shrinking population is a tension worth sizing, not ignoring. For a hold-and-extract strategy, that favors stable workforce rentals over a bet on continued price jumps.
The Paperwork Side
Most friction in a Pittsfield cash-out comes from documentation, not credit. A short checklist of what lenders typically review:
- Seasoning. About six months of ownership, measured from title recording. Count from the recording date, not the closing statement.
- Rent evidence. Executed leases for each unit plus the appraiser’s rent schedule. Month-to-month tenants on a two-family can complicate things.
- Credit. A 620 floor, with tiers at 660, 680, and 700 that typically improve the options available.
- Reserves. About six months of the full monthly obligation (principal, interest, taxes, insurance) held after closing.
- Loan size. Up to $3,000,000 on standard programs, with smaller balances routed through select lenders. Most Pittsfield two-families land well below that.
- Vesting. LLC-titled properties are workable, subject to lender program eligibility.
One local note. Manufactured-home communities, including the new Allendale Pines North, fall outside these programs. Skip them for DSCR cash-out purposes.
Five Units and Up Is a Different Lane
Pittsfield’s multi-family inventory runs well beyond 2-4 units. Homes.com lists a six-unit downtown building and an eight-unit building near downtown, and Redfin shows an 18-unit Morningside building with two 2BR units, eleven 1BR units, and five studios. Buildings of five or more units are commonly underwritten as commercial loans rather than 1-4 unit DSCR products. That is general lending practice, so verify it with lenders. Duplexes, triplexes, and fourplexes are where this loan fits most cleanly.
DSCR or Conventional?
For a W-2 borrower with one or two financed properties and clean returns, conventional financing may win on cost, and the guide “Where DSCR and Conventional Diverge” is worth reviewing before committing. DSCR gets more practical for LLC-held portfolios, self-employed investors, or anyone running into financed-property limits. Both sides depend on the borrower’s file. The DSCR qualification mechanics and the equity-extraction mechanics are each laid out in their own guides. For a state-level view, see DSCR loans in Massachusetts. Investors can reach Lendmire at 828-256-2183 to talk through a Pittsfield file. As a general reminder, verify current local rental rules, taxes, and insurance with qualified local professionals.
Pull Now or Wait?
The real choice for a Pittsfield owner comes down to two options. Refinance now, while the 10 percent price headlines are still fresh and rents are climbing, and accept the risk that appraisal comps soften as days on market stretch. Or hold a season, let rent growth lift rent used for lender review and the appraisal picture settle, and accept that the equity sits idle while you wait. Neither is wrong. In a market with 0.6 percent vacancy and slowing sales, the tenants aren’t the uncertainty. The comps are.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Pittsfield, Massachusetts?
Coverage starts with rent against the full monthly obligation, with 1.00x the standard minimum on most files. Beyond that, lenders typically look at a 620 credit floor, about six months of seasoning from title recording, and roughly six months of reserves. Everything is subject to lender guidelines and property review.
What are the requirements for an investment property loan in Pittsfield, Massachusetts?
The property typically needs to be a 1-4 unit rental, since larger buildings commonly route to commercial lending. Cash-out is capped at 75 percent LTV, and loan amounts run up to $3,000,000 on standard programs. Manufactured homes, log homes, and barndominiums are not eligible.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Pittsfield, MA, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
How much equity can I pull from a Pittsfield duplex?
It depends on the appraisal, the existing balance, and the rent. The ceiling is 75 percent of appraised value, and you subtract the current payoff and any reserve requirement. A lower-than-expected appraisal can shrink proceeds more than proportionally, as the 10 percent example above shows. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Do rotating medical trainees near Berkshire Medical Center make West Side leases riskier?
They add some turnover, but they also add a steady stream of tenants. Duplexes near the hospital draw staff, residents, and students, so vacancy is more likely to be short than long. Lenders review the file on the rent schedule and leases, not on tenant type.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349), a non-QM mortgage broker serving investors in 41 markets including Washington, D.C., helps structure DSCR scenarios commonly evaluated around a property’s rental income rather than personal income paperwork, subject to lender guidelines. Recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2025, Lendmire places loans through wholesale investor lenders and is not a direct lender.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Berkshire Eagle: Rising Rents in Pittsfield
2. Redfin
3. reported
4. Berkshire Community College
6. UMass Donahue Institute coverage
7. Redfin
8. Homes.com
9. Williams College Morningside/Westside report
11. Pittsfield Economic Development
12. Redfin
13. Zumper
14. Rentometer
15. Apartments.com
16. Zillow’s index
17. Homes.com
18. Redfin
19. a 2026 Scotsman Guide Top Mortgage Workplace
20. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Peabody, Massachusetts: How Three-Family Rents Clear a 1.20 DSCR · DSCR Cash Out Refinance in Plymouth, Massachusetts: Equity From Cordage Park Multi-Units · DSCR Cash Out Refinance in Gloucester, Massachusetts: How Seasoning and LTV Work in Gloucester
Guides: Investment Property Cash-Out Refinance in Pittsfield, MA · Investment Property Cash-Out Refinance in Massachusetts
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.