
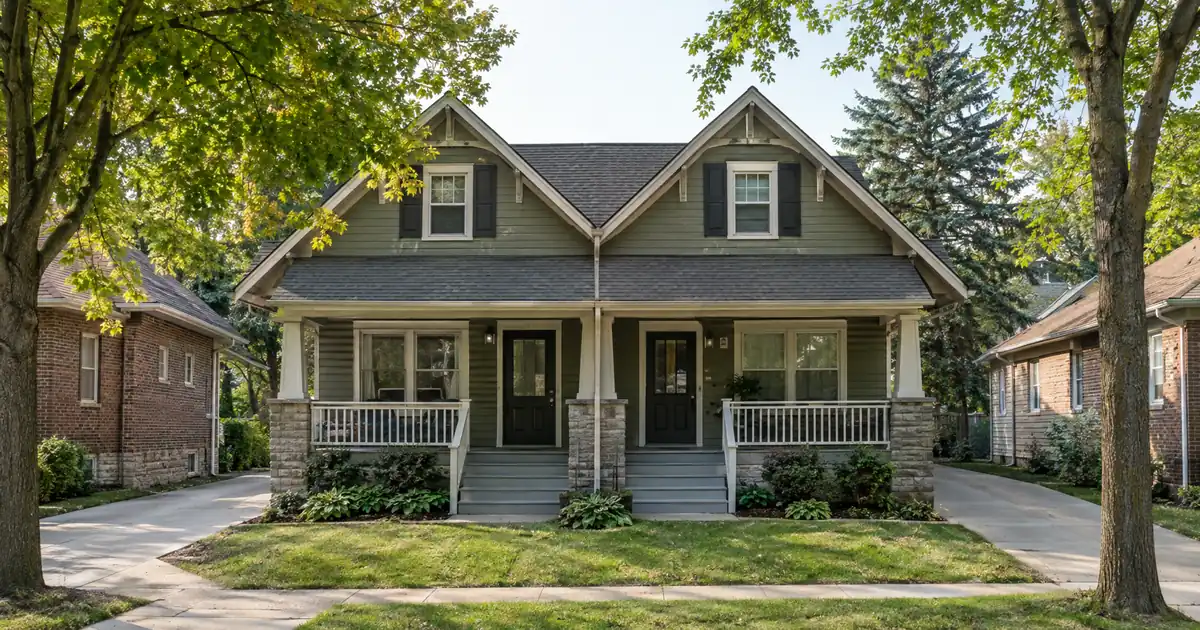
The loudest objection to Greenfield is that the single-family math is thin, and it is. Homes.com puts the median home rent at $1,100 a month and the price-to-rent ratio at 28.4, which is a number that generally favors renting over owning. An investor looking at that and walking away has read it correctly. But a DSCR cash out refinance in Greenfield is a different question from whether a house cash flows. The play here is older two- to four-unit stock where the second unit does the heavy lifting, and the real constraints are comp depth and appraisal, not demand. This piece takes the objection head-on and then shows where the equity extraction math holds up.
The Short Version: A DSCR cash-out refinance in Greenfield, Wisconsin fits investors who already own an older duplex or small multifamily and want to pull equity into the next deal, because the loan is underwritten primarily on the property’s rental income measured against its full monthly obligation, with 45 percent of local households renting per RentCafe.
DSCR Cash-Out Calculator
Run the cash-out numbers in Greenfield, WI
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out leverage tops out at 75 percent LTV, with about 6 months of seasoning from title recording. Redfin puts the median at $318,000, up 11.5 percent year over year, on a thin sample of sales.
- Small-multifamily inventory is thin: Homes.com shows three multi-family listings. Zillow shows 3BR house rents from $1,550 to $2,300, so underwrite to the low end.
Greenfield Market Snapshot
A quick read on the Greenfield investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $1,100 median (Homes.com, Greenfield rentals) |
| University enrollment | Marquette 11,160 students (Spinoso Real Estate Group) |
| Population | 37,345 population (Census Reporter, Greenfield) |
| Vacancy | Low-4% (Marcus & Millichap, Milwaukee) |
The Older Blocks Near the Milwaukee and West Allis Edges
The strongest cash-out candidates in Greenfield are older duplexes and small multifamily on the north and east edges of the city, in the 53220 and 53221 ZIP codes, where the mid-century housing stock sits closest to Milwaukee and West Allis. Asking rents there are workforce-level, and a second unit is what lifts coverage.
Start with the rent levels. Apartments.com shows 53220 asking rents of $1,068 to $1,250 for a one-bedroom and $1,380 to $1,500 for a two-bedroom. ForRent.com lists flat-style units across Greenfield-area ZIPs from roughly $1,295 to $1,795 per unit, including a 3BR upper unit in 53220 at $1,795 and a 2BR lower unit in 53221 at $1,500. Put two of those under one roof and you can model a gross somewhere between $2,600 and $3,600 a month. That is a modeled range built from asking rents, not sold-lease data, but it is the right order of magnitude.
Why does this matter for a refinance? Because the lender is measuring rent against the full monthly obligation on the new loan, and a duplex has two rent checks working against one set of taxes, insurance, and principal and interest. A house has one. That structural difference, not any neighborhood magic, is why the older blocks pencil.
The S. 43rd St corridor in 53220 is worth knowing by name. Zumper shows a cluster of apartment listings along it, which tells you renters already treat this stretch as a rental address. The S. 27th St corridor on the eastern side runs similar workforce stock. Neither is a prestige location (that’s the point). Tenants here are commuting to jobs across the metro, and the city sits at the crossroads of I-41 and I-43, about 15 minutes from downtown Milwaukee, per ApartmentFinder. Treat that as support for steady workforce demand, not as a growth catalyst.
A word on the housing-age data. Third-party data from an older vintage suggests roughly a third of Greenfield’s homes date from the 1940s through the 1960s, which is typical of the Milwaukee area’s duplex and small-multifamily conversions. Confirm the actual count of 2- to 4-unit buildings locally before you build a thesis around it. No source in the research counts them.
Skip the West Side for Cash-Out Math
The newer townhomes, condos, and amenity-heavy complexes in the west and southwest, around 53228, carry higher prices, and that lowers rent-to-value. The rents look healthy: Apartments.com shows 53228 one-bedrooms from $1,348, with a 4401 S 110th St-area complex asking up to $2,094 for a two-bedroom. But those rents are set by newer buildings on higher-priced ground, which is exactly where a 75 percent LTV cash-out squeezes hardest.
Not ideal for equity extraction. If you already own a unit there, a refinance can still make sense on a coverage basis. If you’re shopping for the next cash-out candidate, look east and south instead.
What the Houses Actually Cover
Single-family rentals in Greenfield land between roughly 0.7 and 1.0 coverage at a median-type price, so the loan only works when a house sits at the high end of the rent spread. Duplexes run about 1.1 to 1.6 on the same modeled basis. The difference between those two bands is the whole article.
Here is the spread. Zillow lists one 3BR/1BA house in the 53221 ZIP at $1,550 and a 3BR/1.5BA house of about 1,600 square feet in 53219 at $2,300, a gap near $750 a month. Run the numbers on a modeled $332,000 value (the July median listing price per Movoto) at 75 percent LTV:
| Property (modeled) | Modeled monthly rent | Coverage incl. Taxes and insurance |
|---|---|---|
| 3BR house, low comp | $1,550 | Low 0.7 range |
| 3BR house, high comp | $2,300 | About 1.0 |
| Duplex, two smaller units | $2,600 | About 1.1 to 1.2 |
| Duplex, mid case | $3,000 | About 1.3 |
| Duplex, two 3BR units | $3,600 | About 1.6 |
These are modeled assumptions, not sourced market facts. Coverage is rent divided by full PITIA, meaning principal, interest, taxes, and insurance, using Wisconsin-average tax and insurance loads and rounded down. Using the $332,000 value for the duplex rows is a simplification, since the brief has no sold-price data for duplexes, so swap in your actual appraised value.
The low-comp house is the cautionary tale. At that rent, the file lands in the 0.7 territory, and a sub-1.00 file gets harder: lower leverage, stronger credit, and extra lender review come into play. Select lenders may review sub-1.00 scenarios, and an interest-only structure or a lower LTV may change the picture, but each of those is a lender decision with its own pricing and requirements. The cleaner path is to underwrite to the low comp, not the average, and let the duplex carry the file.
DSCR files in markets like this one typically look like a thin comp set, a seasoned owner with equity built by paying down or by buying below value, and a rent roll that is a few hundred dollars short of the optimistic number. The ones that move forward cleanly are underwritten on in-place leases rather than projected rents, hold documented reserves, and come in with a realistic value expectation instead of a Redfin headline. Files that stall are usually the ones where the borrower assumed the appraisal would match a nearby suburb’s prices.
If this is new to you, the guide “What Is a DSCR Loan” is a two-minute read, and most standard programs are built around a 1.00 benchmark because rent covers the payment at that level. Lendmire (NMLS# 2371349) is a mortgage broker that arranges these loans through wholesale lending channels, so lenders, not the brokerage, review and approve the file.
Does Appreciation Actually Make the Cash-Out Work?
Appreciation helps, but on its own it rarely produces a big check at a 75 percent LTV cap. Redfin’s data shows Greenfield’s median up 11.5 percent year over year at $318,000, with 44 days on market versus 63 the prior year. That is a real move. It is also based on only 16 sales in the month, so treat it as a directional signal, not a valuation.
Do the percentage math. If a property’s value rises 11.5 percent, 75 percent of the new value is roughly 84 percent of the original purchase price. Now compare that against how the original deal was financed. An investor who bought at 80 percent LTV would see only a few points of the original price come out, before costs. An investor who bought at 65 percent LTV, or who paid the balance down, or who bought below value and improved the units, sees a lot more.
This is the appreciation-versus-cash-flow tension in a nutshell. Greenfield’s population is flat, with Census Bureau QuickFacts showing about 37,345 residents over 11.5 square miles and a median age of 42. That is a stable market, not a growth market. You are not buying here because the city is booming. You are buying because the in-place rent supports the debt, and equity is a bonus.
On the mechanics, expect about 6 months of seasoning from title recording, a 75 percent ceiling on cash-out LTV, and reserves around 6 months of PITIA on most files. Credit tiers typically start at a 620 floor, with better terms commonly tied to higher scores. Equity available depends on rent used for lender review, PITIA, reserves, and that LTV cap, so it is not a guaranteed cash figure. If the property sits in an LLC, financing is subject to lender program eligibility. The cash-out qualification details cover seasoning and the cash-out structure in more depth.
The Appraisal Problem Nobody Mentions
Thin duplex inventory is the most underrated risk in Greenfield cash-outs. Homes.com shows three multi-family listings and Trulia shows four at the time of research, and listing counts change daily. Few 2- to 4-unit sales means few close comps.
When comps are scarce, appraisers reach. They may pull from West Allis or south-side Milwaukee, which can pull the appraised value, and therefore the available proceeds, below what a Greenfield owner expects. The practical answer is to build a conservative value assumption into the refinance. If the number comes in higher, great. If it comes in at a more modest figure, the deal still works.
Honestly, this one’s a genuine judgment call. A seller or a listing agent will tell you duplexes in Greenfield are scarce, so values should hold. An appraiser working with three comps will tell you scarce means uncertain. Plan for the second voice.
Rent Softness, Metro Headwinds, and Who Rents Here
The rent trend in Greenfield is mixed, so underwrite a refinance on current in-place rents with a cushion, not on projected growth. RentCafe reports an average rent of $1,455, up 6.17 percent year over year, though its data skews toward larger buildings of 50 or more units. Zumper shows an average of $1,425, down 8 percent from a year earlier, and its monthly figures swing with listing mix. Apartments.com’s one-bedroom average of $1,185 is up 2 percent. Three sources, three directions.
At the metro level, Marcus & Millichap describes a sticky renter base, with vacancy in the low-4 percent range. REJournals summarizes a forecast of 3.9 percent vacancy and effective rents up 2.5 percent. That is supportive. But WisPolitics notes the metro ranked 47th among 50 for multifamily, citing employment headwinds and limited population growth. No Greenfield-specific vacancy figure surfaced, so don’t assume the metro numbers translate neatly.
What holds the demand together is the renter share. Roughly 7,866 households in Greenfield rent, 45 percent of the total, which is deep for a suburb marketed as a bedroom community. Employment runs through Milwaukee-area health systems, retail, manufacturing, and services, with the Southridge Mall cluster straddling the Greenfield and Greendale line as a retail and job anchor. Wikipedia describes the mall as a regional mall in both suburbs, and Spinoso, the owner, says it is the only shopping center serving the southern metro Milwaukee market and notes a parcel slated for redevelopment. That redevelopment could support workforce housing demand, but it is a possibility, not a forecast.
Putting the Proceeds to Work
The point of pulling equity is the next acquisition, and Greenfield’s structure suggests two sensible uses: buy another small multifamily in the same corridor, or stack proceeds toward a property in a market with better rent-to-value. A Milwaukee-area broker blog notes duplexes, triplexes, and fourplexes offer scalability and names South Side neighborhoods and West Allis, which border Greenfield, as places investors are looking. Treat that as qualitative color, not evidence.
If you want to compare structures, Lendmire’s guide to your investment property refinance options lays out how rate-and-term compares with cash-out, and the side-by-side comparison covers where a DSCR file differs from a conventional one. For a broader view of state programs, see Lendmire’s Wisconsin DSCR financing page. And if you already own a Greenfield duplex and want to talk through the file, the team can be reached at 828-256-2183. Review details are subject to lender overlays, and loan amounts up to $3,000,000 on standard programs are the typical ceiling, with smaller balances routed through select lenders in the network.
One generic reminder, and then it’s done: verify current local rental rules, taxes, and insurance with qualified local professionals before you commit.
Frequently Asked Questions
Does a Greenfield duplex really cover better than a house?
Yes, on a modeled basis. A two-unit building at a similar value can land around 1.2 to 1.6 coverage including taxes and insurance, while a single-family rental lands closer to 0.7 to 1.0, depending on which end of the rent spread it sits. The second rent check against one set of ownership costs is the difference. Actual results depend on the appraised value and in-place leases.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Greenfield, WI, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
How much equity can I pull from a Greenfield rental?
The ceiling is 75 percent of appraised value on a cash-out, minus the existing loan, costs, and any reserve requirement. Seasoning is typically about 6 months from title recording. Because the equity available depends on rent, PITIA, reserves, and the 75 percent cap, it is not a guaranteed figure.
Will an appraiser value my duplex using Greenfield comps only?
Not necessarily. Greenfield has very few 2- to 4-unit sales, so appraisers may reach into West Allis or south-side Milwaukee for comparables. That can limit the appraised value and the available cash-out, so build a conservative value assumption into your plan.
Is Greenfield a growth market for rent increases?
No, it’s a stable one. Census Reporter shows about 37,345 residents, and population is flat to slightly declining. Rent trend sources conflict, so underwrite on in-place rents rather than projected increases.
Do I need to wait six months before a cash-out refinance?
Generally yes, about 6 months of ownership measured from title recording, though specifics vary by program and lender. If you bought recently and improved the property, ask about how value and seasoning are treated before assuming the number.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
The One Step Worth Doing First
Before you refinance anything in Greenfield, pull the actual lease rolls on your own building and then count how many 2- to 4-unit sales have closed in Greenfield, West Allis, and the nearby south-side Milwaukee blocks over the past year. That comp list, not a median listing price, is what an appraiser will start from, and it tells you whether your equity is as large on paper as it feels.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage built around DSCR investor lending, with programs available in 41 markets, including Washington, D.C. DSCR lenders commonly evaluate rental-income coverage instead of personal income paperwork, a practical fit for LLC-owned and multi-property investors. Terms vary by lender, property, leverage, and program. The brokerage has been recognized as a 2026 Scotsman Guide Top Workplace and a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Homes.com
2. RentCafe
3. Redfin
4. Homes.com
5. Zillow
6. Spinoso
7. Census Reporter, Greenfield
10. ForRent.com
11. Zumper
12. ApartmentFinder
13. Movoto
15. Trulia
16. REJournals
17. WisPolitics
18. a 2026 Scotsman Guide Top Workplace
19. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Greenfield, Wisconsin: Pulling Equity From Older Duplex Blocks · DSCR Cash Out Refinance in West Allis, Wisconsin: Six Points Duplex Equity Strategy · Cash Out Refinance Investment Property West Allis Wisconsin
Guides: Investment Property Cash-Out Refinance in Wisconsin
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.