
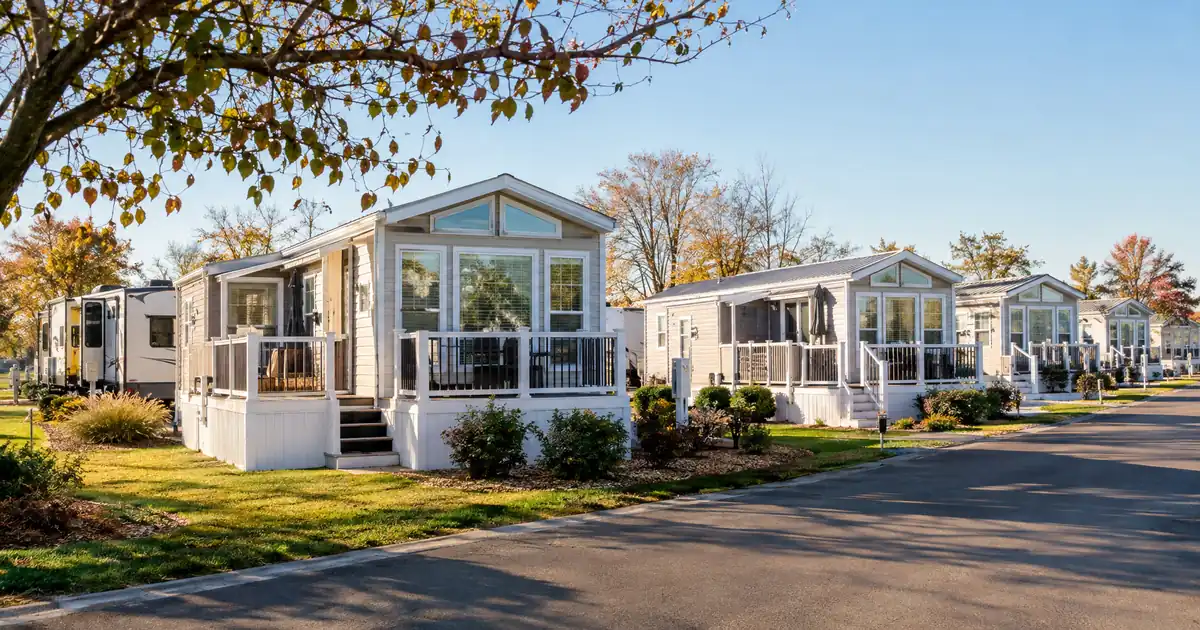
The Quick Read: Usually not as a standalone unit, because a park-model RV is built and sold as a recreational vehicle, which is personal property rather than the real estate a DSCR loan is secured by, though a unit permanently set on owned land and legally converted to real property can be reviewed under the property-type rules. Eligibility is confirmed against program guidelines file by file.
- A park model on a chassis with a vehicle title is typically financed as personal property, not through a DSCR mortgage.
- The realistic exception is a unit set on land you own, on a foundation, with utilities, and retitled as real property under your state’s process.
- If a unit does qualify, short-term rental purchases typically run up to 75% LTV on an investment property, with a 640 credit score and a 1.00 coverage floor.
- A leased pad has no real-property collateral to mortgage, so it fails the test regardless of income.
- Clearing 1.00 coverage never means a property makes money. Repairs, vacancy, and management sit outside the ratio.
What Is a Park-Model Unit, and Why Does the Label Decide the Loan?
A park model is classed as a recreational vehicle, and that label drives which loan products exist for it. The RV Industry Association defines a park model RV as a unit on a single trailer chassis, mounted on wheels, with no more than 400 square feet of gross trailer area in set-up mode. Manufacturers certify these units to the ANSI A119.5 standard.
Short-Term Rental Calculator
Run the STR numbers in your market
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 15, 2026
Prefilled with starting assumptions — enter your nightly rate, occupancy, taxes, and insurance for a more accurate picture.
Short-term rental income is documented with a 12-month history or a market data report. Program parameters update from Lendmire’s centralized guideline source.
As of Oct 15, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Nightly rate, occupancy, taxes, and insurance are editable estimates. Qualifying income for short-term rentals varies by program — some use appraisal market rent, others use documented STR history or projections — and is confirmed in underwriting. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The same page says RVs are not meant to be affixed to real property or built for permanent residence. Park models are most often sited in RV parks and campgrounds for seasonal use. A tiny house is a different thing, since the association notes a tiny home is not an RV and has no set construction standard.
That distinction matters because the people who sell park models often market them as cabins. They look like cabins, and they photograph well for booking platforms. A lender’s underwriter looks at the paperwork instead, and a vehicle identification number plus an RV certification seal point to a vehicle.
Size does not settle it either. Plenty of investors assume 400 square feet is the line between a house and a park model. The certification and the title are what count, and the footprint is just a side effect.
How Does a DSCR Loan Look at a Property?
A DSCR loan qualifies primarily on property-level rental income covering the payment, subject to lender guidelines. DSCR stands for debt service coverage ratio. You divide the property’s monthly rent by its monthly PITIA, which is principal, interest, taxes, insurance, and any association dues.
DSCR loans are designed for non-owner-occupied investment properties. Because they are business-purpose investor loans, they are reviewed differently from a standard owner-occupied mortgage.
The product is a mortgage, so there has to be real estate to secure it. Lendmire’s complete DSCR loans guide describes the usual collateral as investment one-to-four-unit residential and small multifamily. A titled vehicle is not on that list.
Across the wholesale network Lendmire works with, the same logic shows up in the ineligible property list. Manufactured homes, log homes, and barndominiums are not offered through these DSCR programs. Park-model RVs are not listed as standard eligible collateral either, and Lendmire confirms each case against the network’s guidelines instead of assuming a yes.
The Gating Test: Five Questions Before Any Lender Reviews the Income
Run these five checks before you spend a dollar on an appraisal. A unit that fails the first one rarely needs the other four.
| Check | What a lender looks for | If it fails |
|---|---|---|
| Classification | Real property, not a titled vehicle | Personal-property loan route |
| Land | You own the land under the unit | No real-property collateral |
| Foundation | Permanent placement, wheels removed | Needs site work first |
| Utilities | Permanent water, power, septic or sewer | Needs hookups first |
| Unit count | Within a one-to-four-unit residential file | Commercial underwriting |
Each row is a gate and not a score. Passing four of five does not average out.
The retitling piece is state-specific. Some states have a process that converts a unit to real property, and some do not make it simple. No single national procedure applies, so your county recorder or title company is the first call, and a lender’s property review is the second.
What If You Convert the Park Model to Real Property?
If the unit is permanently placed on land you own and retitled as real property, the standard DSCR mechanics apply. The appraisal sets value and market rent. The coverage ratio runs on that rent against the full monthly obligation.
This is the only mainstream path, and it is narrow. It asks for owned land, a foundation, utility connections, and a clean retitling record. It also asks for an appraiser who can find comparable sales for a unit type that rarely trades.
Thin comps are a real risk. Park-model sales are sparse in most areas, so an appraiser may lean on cabins, tiny homes, or small site-built homes for support. The appraised value can come in lower than your purchase price, which cuts into leverage, and no one can promise how a given appraiser will see it.
Even after conversion, the file is still reviewed individually. Lender acceptance is program-specific, and some lenders in the network will decline a converted unit on property-type grounds. Treat conversion as a way to earn a review, not as a way to earn an approval.
How Do You Prove STR Income on Any Unit?
Short-term rental files qualify on documented income under the applicable program, subject to lender guidelines. Typical evidence includes an appraiser’s short-term rental analysis, a property manager’s statement, twelve months of bank statements showing booking deposits, or a market-data projection. The method a lender accepts varies by program.
Network programs for short-term rentals generally expect about 12 months of hosting history. They also expect a credit score of 640 or better. Purchase leverage on an investment property tops out at 75% LTV on the strongest files. Refinance and cash-out on short-term rental collateral run up to 70% LTV. Coverage floors are 1.00 on a purchase and 1.00 on a refinance, subject to lender guidelines. Standard loan sizes go up to $3,000,000.
Notice that history requirement. A portfolio operator expanding into new park-model units has a hosting record on other properties, but a brand-new unit has none of its own. Lenders vary on how they treat that, so the strongest files document the operator’s track record clearly.
The appraisal form matters too. The standard rent schedule, Form 1007, measures long-term rent. An appraisal-industry write-up from Class Valuation argues the form is a poor fit for short-term rental income. Form 1025 is the equivalent for two-to-four-unit properties, and it carries the same long-term focus.
Short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income.
What Changes When You Run a Portfolio?
A portfolio operator carries a problem a single-unit buyer does not: mixed collateral. Your site-built cabins and houses can sit in DSCR files, while the park models usually cannot. That split changes how you plan growth.
Say you operate eight units. Five are site-built houses on owned lots, and three are park models on chassis. Run the numbers on the two groups separately. The five houses can each be arranged as a DSCR file, with coverage clearing roughly 1.2x on the stronger ones. The three park models likely need a different loan type with different terms.
DSCR loans are written one property at a time. Many operators hold properties in LLCs, and loans to LLC-titled entities are available subject to lender program eligibility. A personal-property loan on a unit often works differently. Some RV-type lenders will not lend to an entity at all, so you can end up with one asset class in an LLC and another in your personal name. Keep that in mind before you restructure anything.
The practical danger is scaling math. If you count park-model pads as DSCR-eligible units in your growth plan, you overstate how many properties you can finance on property income alone. The pads may still be good businesses. They just run on a different financing track.
One option is to fund the pads with equity from your eligible properties. If you hold seasoned site-built rentals, a cash-out refinance on short-term rental collateral runs up to 70% LTV, and standard rentals run up to 75%. Lendmire’s piece Can an STR Portfolio Operator Cash Out Before Six Months of Seasoning? covers the timing side. Some operators use the proceeds to buy park models outright. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
What If the Pads Sit Inside a Campground You Own?
Several park models on pads inside an RV park or campground you own is commercial financing, not residential DSCR. The collateral is a hospitality business with land, hookups, and a pad count. Underwriting looks at operating history and site count, and those are different questions from rent against payment.
Commercial campground loans and government-backed small-business loans exist for this. They carry their own rules, which are not the rules of the DSCR programs here. A commercial broker is the right conversation.
A leased pad is simpler. If you do not own the land under the unit, there is no real property to mortgage. The unit is personal property sitting on someone else’s dirt. That structure cannot go into a DSCR file.
What Are Your Financing Paths If DSCR Does Not Fit?
When a park model fails the property test, financing moves to products built for personal property or for commercial assets. Each has a different tradeoff.
| Path | Who it suits | Main tradeoff |
|---|---|---|
| RV or chattel loan | Single unit, titled as vehicle | Higher cost, weaker protections |
| Personal loan | Small purchase, strong credit | Short terms, entity limits |
| Cash or cash-out from other assets | Operators with equity | Ties up capital |
| Commercial campground loan | Owner of a multi-pad park | Operating-history demands |
The federal consumer finance regulator’s report on manufactured-housing finance explains why personal-property loans differ from real-property loans. Chattel loans tend to carry higher interest costs and give borrowers weaker consumer protections. That report covers HUD-code manufactured homes and not park-model RVs, so use it for the real-versus-personal-property split and not for park-model specifics.
Builders who sell park models often say these units cannot get a conventional mortgage and are financed with RV or personal loans. That matches the classification logic above, though a seller’s blog is not a lending guideline.
A Worked Example With Modeled Ratios
Consider an operator who owns a cabin-style house on a half-acre lot and wants to add a park-model unit beside it. Treat everything below as an illustration and not as cited market data.
Option one leaves the park model as a titled RV. The rental income is real, but the unit cannot go into a DSCR file. The operator pays for it with cash or an RV loan.
Option two converts the unit. The operator pours a foundation, connects permanent utilities, and retitles under the state process. The property is then a two-structure parcel, which a lender reviews as an investment property. Assume the short-term rental analysis supports rent that clears about 1.1x against the full obligation, and assume the operator has the 12 months of hosting history. On a purchase, the file could be reviewed at up to 75% LTV with a 640-plus score.
Option two looks better on paper. It also adds site work, retitling, and appraisal risk, and the appraised value could land under the purchase price. A prudent operator stress-tests the coverage ratio with a haircut to projected income before committing.
A note on what the ratio means. Clearing 1.00 means rent covers the housing payment, and that is all it means. Cleaning, utilities, repairs, platform fees, vacancy, and management all sit outside the calculation, and the deal still has to pay for them.
DSCR vs. conventional financing
There are two common ways to finance an investment property, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Where Operators Get It Wrong
Treating a tiny house and a park model as the same thing. The RV association says a tiny home is not an RV, and park models are RVs. The label on your unit matters more than its looks.
Assuming a deck and a driveway make it real estate. Not automatically. Real-property status depends on your state’s titling process and a lender’s willingness to accept it.
Assuming DSCR has no property-type limits. The program reviews the file on property income, but the property still has to be eligible collateral.
Using the 1007 as the short-term income number. It measures long-term rent, so an STR-focused file needs additional income evidence.
Mixing the two loan types without planning the entity structure. Real-property and personal-property financing do not always fit in the same LLC.
Tax treatment can depend on how the funds are used and how the property is held; investors should keep clear records and speak with a qualified tax professional before relying on any deduction.
Key Terms Defined
DSCR (debt service coverage ratio): monthly rent divided by the full monthly housing obligation, used to see whether the property pays its own way.
PITIA: principal, interest, taxes, insurance, and association dues, which together make up the monthly obligation in the ratio.
Real property: land and anything permanently attached to it, which is the collateral a mortgage is written on.
Personal property (chattel): movable property, such as a titled vehicle, which is financed with different loan products than a mortgage.
Seasoning: the waiting period a lender wants between buying a property and refinancing it.
Park-model RV: a recreational vehicle on a single chassis, no more than 400 square feet in set-up mode, built for seasonal use.
What Should You Do Next?
Start with the land and the title. If you own the ground and the unit has a vehicle title, ask your county and title company whether conversion to real property is available. Then bring that answer to a broker before you build the plan around it.
If you are buying or refinancing a rental property and want to see how the numbers work, Lendmire can help you compare DSCR loan options based on the property income, credit profile, leverage, and investor goals. The brokerage arranges these loans through select lenders in its wholesale network across 41 markets, including Washington, D.C. It is not a commitment to lend, and every file is reviewed individually. You can reach the team at 828-256-2183.
Frequently Asked Questions
Can I use a DSCR loan to buy a park model I plan to put on Airbnb?
Usually not if the unit is titled as a vehicle. A DSCR loan is a mortgage on real property, and a titled RV is personal property. If the unit is permanently placed on land you own and retitled as real property, a lender can review it, subject to program guidelines.
What if I already own the land under the park model?
Owning the land is the first requirement and not the last. The unit also needs a permanent foundation, permanent utilities, and real-property status under your state’s process. Even then, acceptance varies by lender and by property type.
Does my existing STR portfolio help me qualify for a park-model loan?
Your hosting record helps with the experience expectation, which is about 12 months for short-term rental programs. It does not change the property-type rules. A strong portfolio helps the file, but it cannot turn a titled vehicle into real estate.
Can I finance several park models inside one campground with a DSCR loan?
No, that is a commercial campground financing question and not a residential DSCR file. Underwriting there focuses on operating history, site count, and the business itself. A commercial lender is the right conversation.
Does a higher down payment make a park model eligible?
No. More equity lowers the monthly payment and can lift coverage, but it never overrides property eligibility. The strongest files pass both tests: eligible collateral and enough rental coverage.
Investors focused on short-term rentals can review DSCR loans for Airbnb and short-term rentals.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage built around DSCR investor lending, with programs available in 41 markets, including Washington, D.C. DSCR lenders commonly evaluate rental-income coverage instead of personal income paperwork — a practical fit for LLC-owned and multi-property investors. Terms vary by lender, property, leverage, and program. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. RV Industry Association: What Is an RV?
2. Class Valuation: Appraisal Form 1007 and Short-Term Rentals
3. Consumer Financial Protection Bureau: Manufactured-Housing Consumer Finance
This article is part of Lendmire’s short-term rental loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: How DSCR STR Entity Rules Work for Portfolio Operators Scaling Past Conventional · One Blanket DSCR Loan vs Individual Loans for a High-W-2 STR Operator · STR Projection vs Long-Term Rent Fallback on a Condotel DSCR Loan
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.